
W. P. Carey (WPC) Stock Looks Undervalued Despite Its 44% Three Year Run
W. P. Carey has delivered a 3 year gain that many income-focused real estate investors will notice. The question now is whether the current share price still lines up with what its earnings can reasonably support. With new financial updates in 2026 and an active dividend profile, the stock invites a closer look at what investors are effectively paying for each dollar of profit.
- The share price has risen 43.7% over the past 3 years, which puts real weight on whether that move is anchored by the REIT's underlying earnings power.
- Recent financial updates, including higher adjusted funds from operations and a raised dividend, may support the idea that W. P. Carey's earnings base and cash flows are evolving in ways that matter for how its P/E is interpreted today.
- Your read on W. P. Carey is one view; the desks covering it have another. See what analysts think W. P. Carey's shares could be worth.
The issue now is whether W. P. Carey's current valuation is adequately explained by its earnings, given that recent share price performance and business updates.
If you are comparing W. P. Carey with other income-oriented opportunities, a focused stock screen built around dividend strength can be a useful second lens alongside its earnings story, starting with 5 dividend fortresses.
Does W. P. Carey Look Undervalued on Earnings?
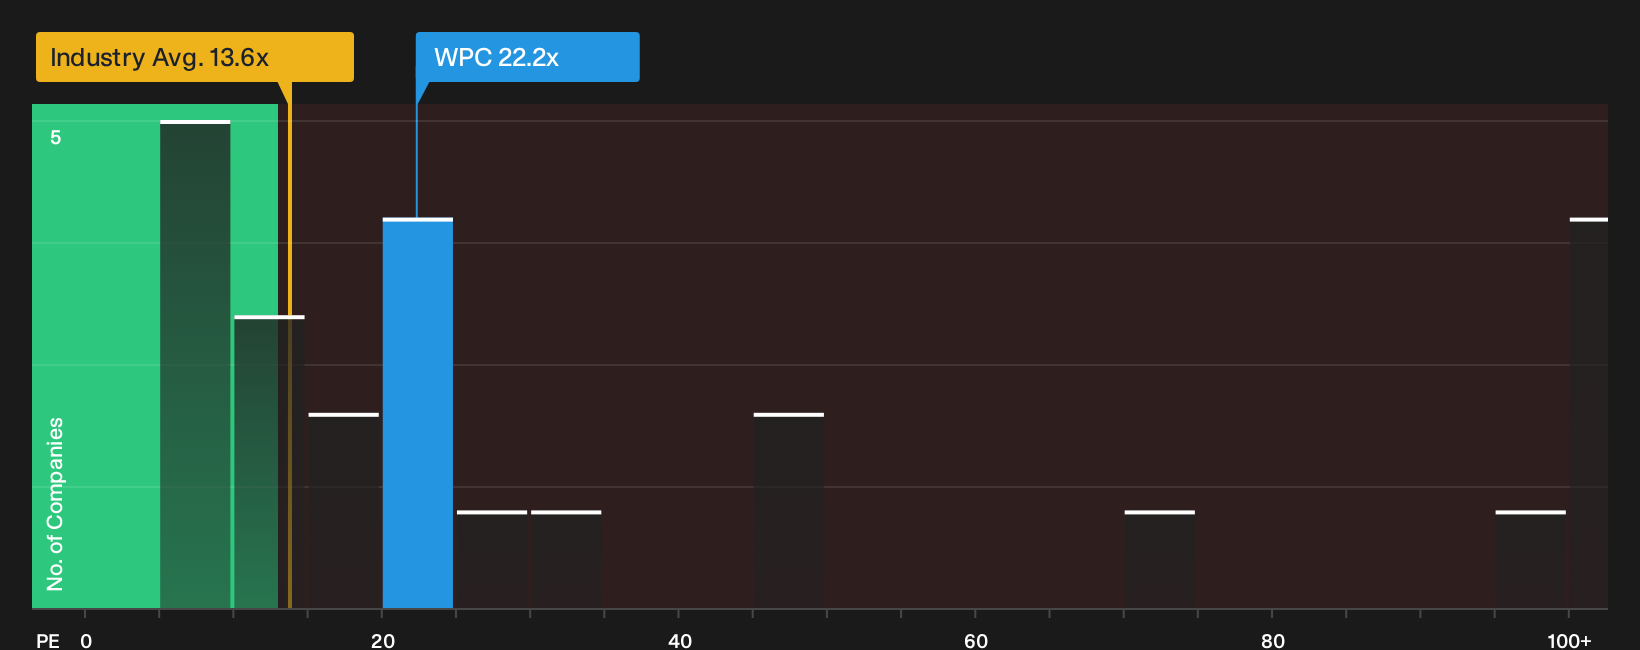
The P/E ratio suits W. P. Carey because earnings are a central anchor for how investors assess a mature, income-focused REIT. On this lens, the stock trades on a P/E of 22.2x, compared with an industry average of 13.6x and a peer group around 73.2x. It therefore sits above the broader REIT pack but well below some higher priced rivals. For a holder, that gap indicates that W. P. Carey is not being treated as a bargain-bin option, yet the market is also not assigning it the richest multiples seen in the peer set.
The latest modelled fair P/E, which blends W. P. Carey’s profitability profile, risk and scale, comes out higher than the current 22.2x. On this metric, the shares screen as undervalued. The recent third quarter 2026 update, with higher AFFO guidance and a lifted dividend, fits into that picture because it helps explain why the market is still paying more than the REIT average for each dollar of earnings, while the multiple remains below what the model implies could be justified. Explore the numbers behind W. P. Carey's P/E valuation.
The W. P. Carey Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for W. P. Carey pick up where the P/E puzzle leaves off. They explain what would need to happen to W. P. Carey's future earnings, margins and growth profile for the stock to be worth meaningfully more or less than today’s market price. They also turn a single valuation output into a set of underlying assumptions you can monitor over time on the Community page.
Community views on W. P. Carey are split between those who see more upside in the current setup and those who think the price already reflects a lot of good news.
Bull case: 17% undervalued
"Current valuation implies the share price does not fully reflect the raised 2026 AFFO guidance, the prefunded investment pipeline of up to $2.1b, and the company’s shift toward long-lease industrial, warehouse and retail properties…"
Discover why this Narrative puts W. P. Carey at 17% undervalued.
Bear case: 24% overvalued
"What holds me back is price: the stock trades above fair value and above my entry filters, so the buy signal stays Risky…"
Explore why this Narrative puts W. P. Carey at 24% overvalued.
W. P. Carey’s valuation still leaves one crucial issue on the table
Price and earnings only tell part of the story for W. P. Carey, because separate checks have highlighted specific areas of concern that could matter for long term holders. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com