
Is Sportradar Group (SRAD) Undervalued Going Into Its November 3 Earnings?
Sportradar Group (SRAD) is drawing fresh attention as investors focus on the upcoming November 3 earnings release. Expectations for higher year-over-year earnings and revenue are shaping short term sentiment around the stock.
Recent trading tells a mixed story for Sportradar Group. The share price has slipped to US$12.23 and is down 7.63% over the past month and 18.19% over the last 90 days. The year-to-date share price return has fallen 47.56% and the 1-year total shareholder return is down 54.09%. However, the 3-year total shareholder return remains positive at 38.51%, which suggests that sentiment has cooled recently even as some longer-term investors are still ahead.
Scan beyond Sportradar Group before earnings season hits full speed by reviewing our hand picked 29 high quality undervalued stocks that combine solid balance sheets and meaningful cash generation.
Recent price pressure on Sportradar Group could be read as a warning sign about the business itself, or as sentiment cooling after earlier gains. The valuation now needs to be tested against the underlying earnings power.
Most Popular Narrative: 32% Undervalued
Sportradar Group's most followed narrative pegs fair value at $18.07, well above the last close of $12.23. This frames the current weakness as a valuation gap rather than just a sentiment story.
Integration of IMG sports rights and long term exclusive data and AV deals such as Wimbledon and Euroleague Basketball, combined with multi year prediction market agreements that extend Sportradar Group data into new use cases, provide multi year visibility on content monetization and can support revenue and margin resilience.
See why 23 investors see Sportradar Group as 32% undervalued.
Result: Fair Value of $18.07 (UNDERVALUED)
Still, the 2026 guidance cut and ongoing securities fraud class actions could disrupt Sportradar Group's revenue mix and pressure profitability assumptions that underpin this undervaluation story.
Find out about the key risks to this Sportradar Group narrative.
Another View On Sportradar Group’s Valuation
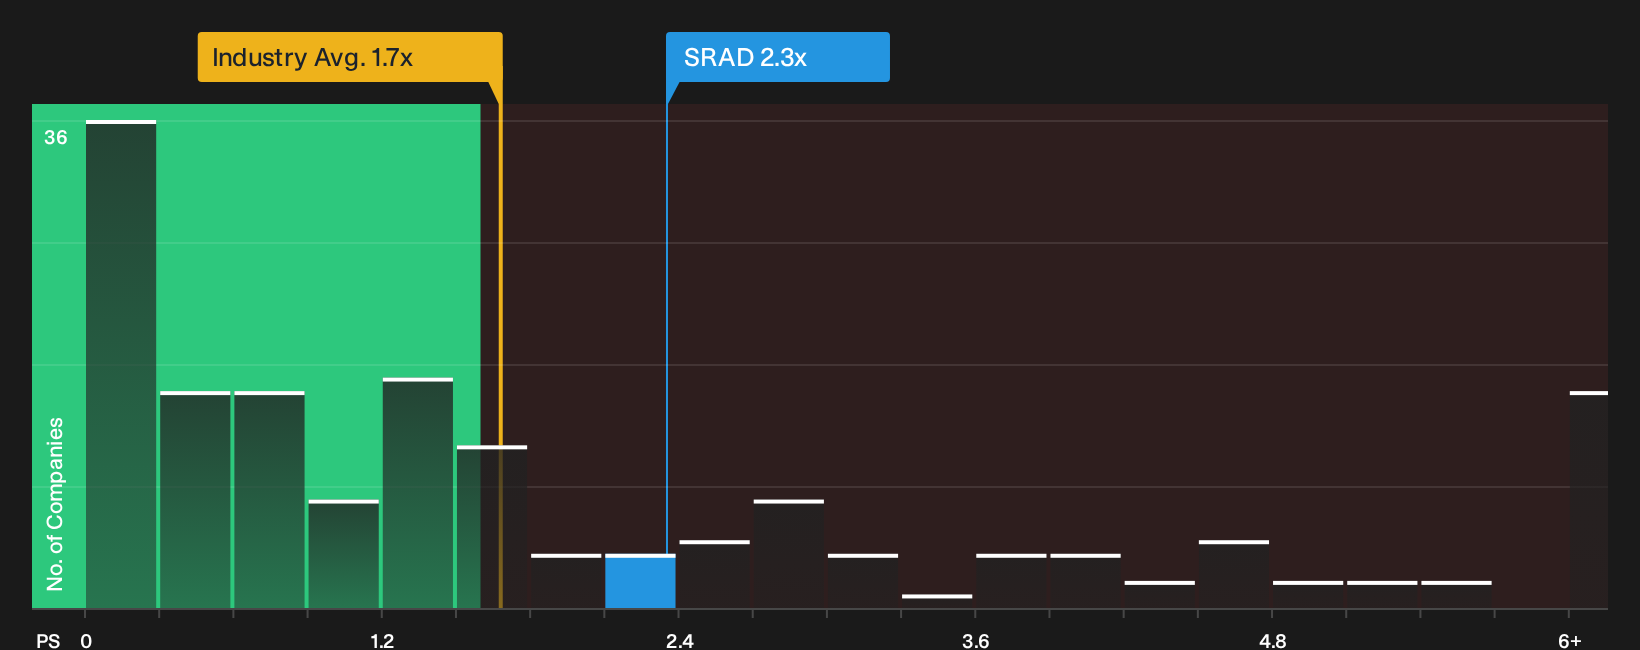
The DCF narrative presents Sportradar Group as undervalued, yet the market is pricing the stock very differently based on simple sales metrics. The P/S ratio is 2.3x, compared with 1.7x for the US Hospitality industry and peers, while the fair ratio is cited as 1.2x. This gap indicates that investors are paying a higher price for each dollar of Sportradar Group revenue. The key question is whether future execution will align this premium with fundamentals or lead to a wider divergence.
To see how this price tag compares with detailed cash flow assumptions and earnings scenarios, take a look at our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sportradar Group's story so far. Act while sentiment is still recalibrating and weigh the 2 key rewards and 2 important warning signs against your own view.
Looking for more Sportradar Group sized opportunities?
Do not stop with Sportradar Group. Use this earnings window to widen your watchlist and pressure test fresh ideas before the market moves without you.
- Spot potential mispricing early by scanning our 29 high quality undervalued stocks that combine quality fundamentals with marked down share prices.
- Strengthen capital preservation by reviewing a 30 resilient stocks with low risk scores that filters for resilient operations and cleaner balance sheets.
- Get ahead of the crowd by searching a 21 high quality undiscovered gems packed with underfollowed companies that still show solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com