
Learn Why The Bull Case For United Therapeutics Stock Could Change Following FDA Trial Clearance
- United Therapeutics received past FDA clearance to begin a phase 1, open label, single ascending dose trial of Treprostinil-Iloprost SMI in healthy volunteers, assessing safety, tolerability, and pharmacokinetics for a potential as needed inhaled treatment for pulmonary arterial hypertension symptom flare ups.
- The new soft mist inhaler candidate extends United Therapeutics' prostacyclin analogue toolkit and aims to address acute symptom gaps between maintenance prostacyclin doses for pulmonary arterial hypertension patients.
- We will now see how United Therapeutics' investment narrative could be influenced by FDA clearance for Treprostinil-Iloprost SMI clinical testing.
Scan 21 high quality undiscovered gems that, like United Therapeutics, are pushing new therapies through the clinic while still flying under most investors' radar.
United Therapeutics Investment Narrative Recap
To own United Therapeutics, you really have to believe the prostacyclin franchise can hold its ground while newer pulmonary fibrosis, COPD and xenotransplant programs mature. The big near term swing factor is how well treprostinil based therapies defend share against competitors as commentary points to pressure on the base business and quarterly revenue. The Treprostinil Iloprost SMI phase 1 clearance looks more like pipeline depth than a near term needle mover.
The biggest operating risk is that ongoing investment into larger pulmonary fibrosis and COPD opportunities does not translate into the high revenue per patient that management has outlined. That would leave United Therapeutics holding substantial R&D and commercial costs without the expected scale benefits, and could limit how much the buyback and high net margin profile support earnings per share in the shorter term.
The recent announcement that resonates most with this soft mist inhaler update is the FDA clearance for the SUMMIT trial of treprostinil SMI in PH COPD. Both projects lean on inhaled treprostinil delivered via portable devices, so execution across these trials will shape how much practical mileage United Therapeutics gets from its soft mist platform beyond core PAH.
If SUMMIT reads out well on safety, tolerability, exercise capacity and NT proBNP, that would feed directly into the key catalyst of expanding treprostinil use into broader pulmonary populations and reinforcing lifecycle management of the prostacyclin portfolio. Any issues in enrollment, tolerability or long term extension data could instead reinforce existing concerns about dosing burden in real world pulmonary fibrosis and COPD settings.
United Therapeutics' narrative projects US$4.4b revenue and US$1.8b earnings by 2029. This implies 11.9% yearly revenue growth and an earnings increase of about US$500m from US$1.3b today.
Uncover how United Therapeutics' fair value indicates a potential upside of 10% to its current price before the market closes that discount.
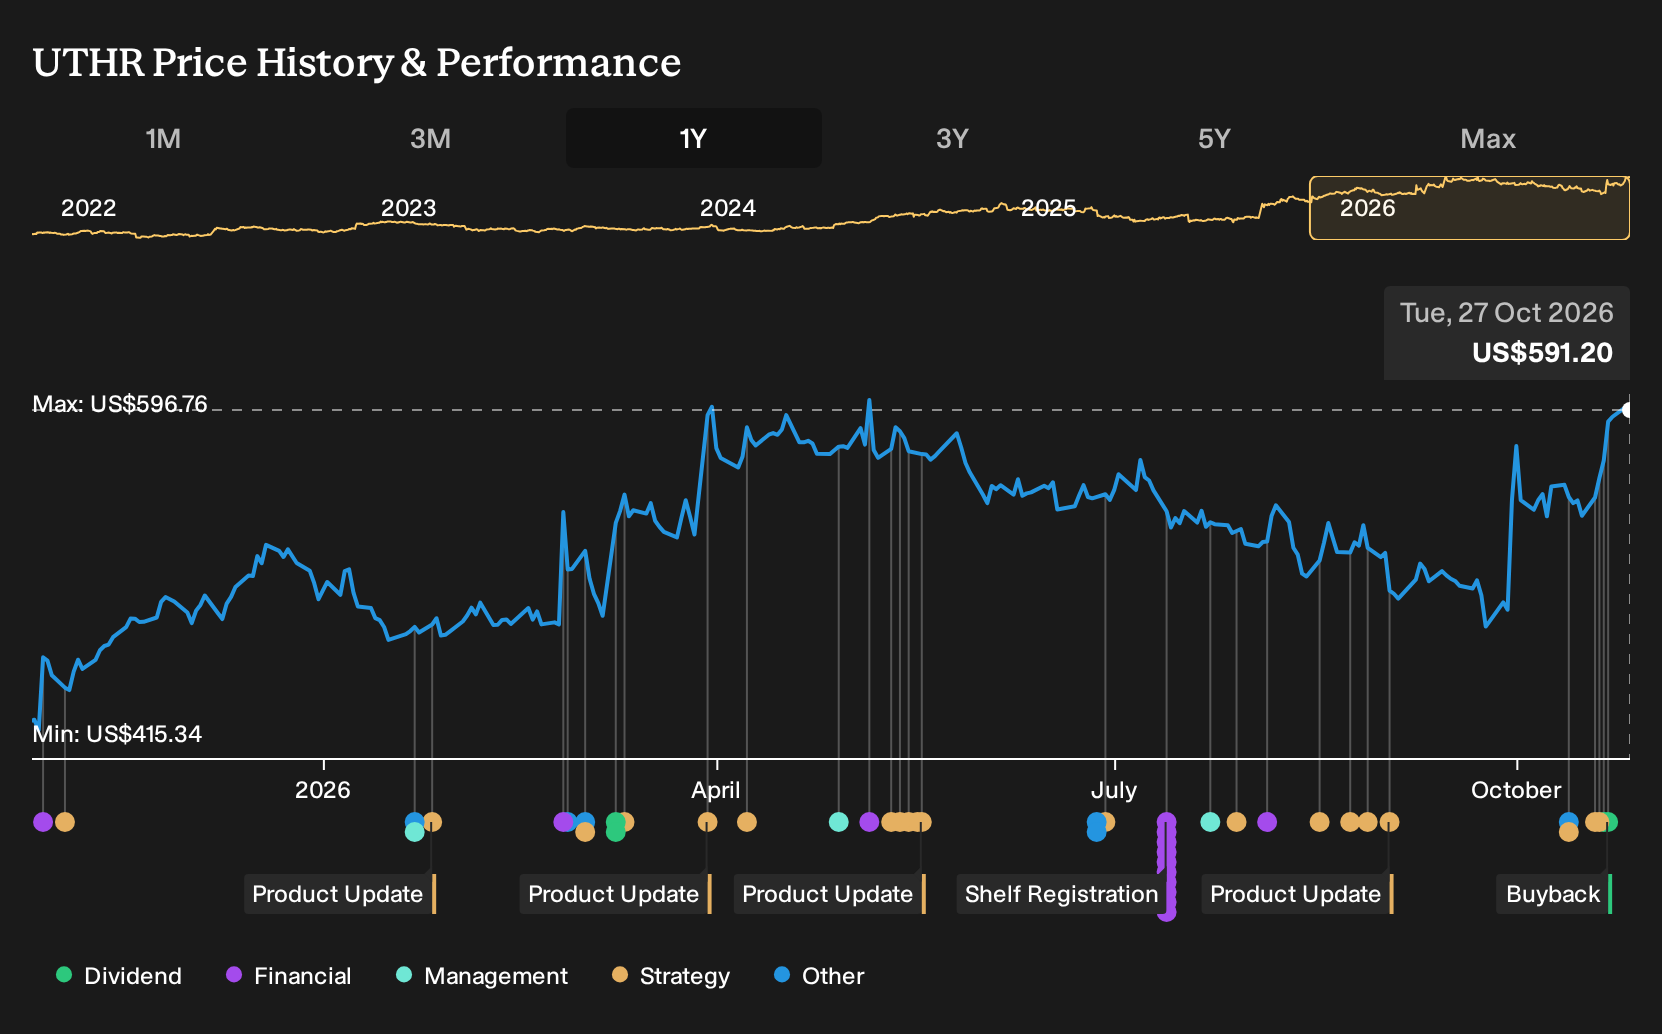
Exploring Other Perspectives
Some of the most optimistic analysts already framed United Therapeutics as a fibrosis and xenotransplantation story, with projections of US$5.4b in revenue and US$2.4b in earnings by 2029 before this Treprostinil Iloprost SMI news. You can treat this new inhaler trial as a fresh test of that bolder vision and compare multiple viewpoints yourself.
Explore 3 other United Therapeutics fair value estimates, including one that suggests as much as 259% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Therapeutics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for United Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Therapeutics?
If the United Therapeutics story has you thinking about how to build a broader watchlist, it can help to scan for other businesses with clear financial profiles and distinct risk reward trade offs using the Simply Wall St Screener.
- If you want potential mispriced opportunities with quality still front and center, start by scanning 29 high quality undervalued stocks that combine strong fundamentals with what our models flag as attractive pricing.
- For investors who care most about resilience through different market conditions, it can be useful to filter for 30 resilient stocks with low risk scores that screen well on balance sheet strength and volatility measures.
- If steady income is a key part of your plan, focus on companies in 5 dividend fortresses that currently offer higher yields while still passing our basic fundamental checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com