
Did HD Korea Shipbuilding's Fall Catch You Out? What Investors Missed
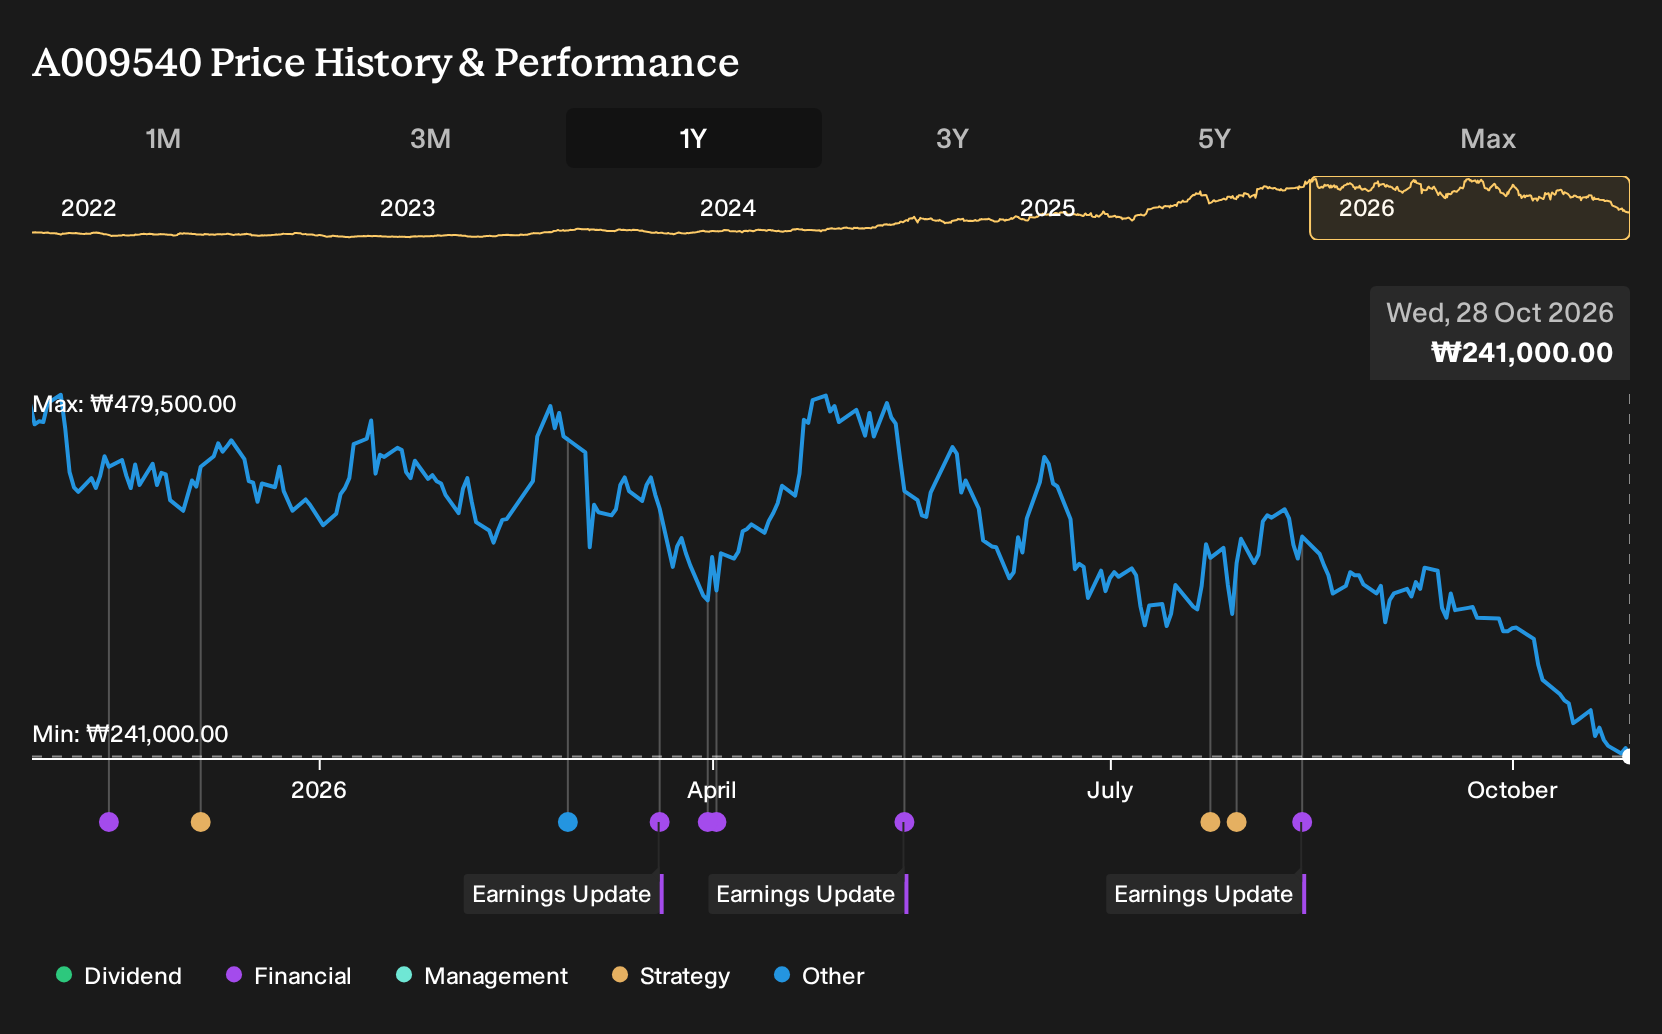
When HD Korea Shipbuilding & Offshore Engineering reported Q2 2026 revenue of ₩8,927,046.477m and net income of ₩1,287,492.189m, with net margin rising to 14.4%, it looked like the story had finally clicked. Holding HD Korea Shipbuilding & Offshore Engineering over the past year would have meant a 45.9% loss, including dividends. If you had bought in back on 28 October 2025, how should that gap between upbeat numbers and weak shareholder outcome be explained?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind HD Korea Shipbuilding & Offshore Engineering. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Argument HD Korea Shipbuilding Investors Were Really Weighing
The shares cost ₩460,500 at the start of the period, and anyone looking at HD Korea Shipbuilding & Offshore Engineering then had to decide which story sounded more convincing.
The bullish narrative put fair value at ₩494,000 and leaned on a decarbonization surge. That view assumed revenue growth of 12.3% a year and profit margins climbing from 5.6% to 15.5%, helped by eco-friendly vessels and offshore projects.
The more cautious narrative pointed to a fair value of ₩423,067. That camp still assumed 8.4% annual revenue growth and 9.9% margins but stressed risks such as weaker commercial vessel demand and LNG pricing pressure.
What The Results Changed For HD Korea Shipbuilding & Offshore Engineering
The clearest development came from the Q2 2026 report for HD Korea Shipbuilding & Offshore Engineering. Revenue reached ₩8,927,046.477m and net income was ₩1,287,492.189m, compared with ₩7,428,417.053m and ₩356,438.676m in Q2 2025. Net margin moved from 4.8% to 14.4%, which gave more support to the optimistic profitability view than to a more cautious interpretation.
The key lesson is simple. When an investment thesis leans on margin expansion, treat net margin as the central assumption to test and track how much of the move actually shows up in audited results over time.
What Today’s HD Korea Shipbuilding Price Already Assumes
With HD Korea Shipbuilding & Offshore Engineering now at ₩241,000, this selected Narrative’s Fair Value sits above the current price. That view leans on the idea that today’s weaker share price and the earnings profile described by analysts are out of sync.
The Narrative’s edge is the focus on higher margin engines, richer vessel mix and new offshore and defense work. For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that productivity gains and high margin projects can be sustained through future ordering cycles.
"Key Takeaways: Bullish analysts expect HD Korea Shipbuilding & Offshore Engineering to convert its long-duration backlog in high value-added vessels, engines and offshore projects into structurally higher earnings power over the coming years. The main factor that has to go right is continued execution on productivity gains and a high margin mix, including LNG and LPG carriers, dual fuel and HiMSEN engines, and profitable offshore and defense projects, despite cyclical swings in ordering and regional project delays."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where HD Korea Shipbuilding’s World Connects
HD Korea Shipbuilding pushes the hardware side of heavy industry. You could also look at what happens much higher up.
Orbit is where infrastructure becomes information. Rockets and on board hardware turn launch pads into communication, imaging and navigation tools.
One specialist works on both sides of that bridge. It designs and flies its own small and medium rockets, then supplies the satellites riding on them.
The same customers who order complex vessels or offshore projects also need accurate signals, pictures and timing. As those needs spread, this twin launch and satellite builder could face very different tests.
One Narrative has already put a figure on it. → Uncover the company trading 40% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com