
Rio Tinto Group (LSE:RIO) Shares Moved, What Is Behind The Latest Attention?
Rio Tinto Group (LSE:RIO) has put fresh capital behind its aluminium chain by committing US$1.9b to the Kangwinan bauxite project in Queensland and advancing Rondo Heat Battery plans at its Yarwun alumina refinery.
These commitments arrive after a softer stretch for the Rio Tinto Group share price, with a 30-day share price return of down 9.71% and a 90-day share price return of down 8.27%. At the same time, the 1-year total shareholder return of 24.17% and 5-year total shareholder return of 102.54% point to long-run gains that recent news on Kangwinan, Yarwun and the Liamu joint venture may now be testing against fading short term momentum.
Scan beyond Rio Tinto Group and compare its latest aluminium and copper moves with a curated set of miners and materials stocks in the list of solid balance sheet and fundamentals (10 results).
Rio Tinto Group is focusing on long term aluminium and copper growth plans just as the share price has cooled in recent months. Does that create a case for buying now, or does patience on entry price still matter more?
Most Popular Narrative: 15% Undervalued
On the most followed view, Rio Tinto Group screens as undervalued, with a fair value of £75.57 against the latest £64.00 close. This puts fresh attention on whether the current pullback matches that thesis.
Diversification into battery metals (lithium, copper) through acquisitions and organic project delivery positions Rio Tinto to capture rising demand in electric vehicles, stationary energy storage, and grid infrastructure. These segments are expected to have structurally higher pricing and margins than mature bulk commodities, driving earnings and improving margin resilience.
Strong operational efficiency improvements evident in reduced unit costs, workforce rationalization, and automation have enabled Rio Tinto to grow volumes while keeping cost inflation contained. This enhances net margins and earnings stability in cyclically soft pricing environments.
See why 285 investors see Rio Tinto Group as 15% undervalued.
Result: Fair Value of £75.57 (UNDERVALUED)
Still, the Rio Tinto Group story can be knocked off course if weaker pricing for iron ore and lithium persists, or if higher capital needs squeeze profit margins and cash generation.
Find out about the key risks to this Rio Tinto Group narrative.
Another Take On Rio Tinto Group’s Valuation
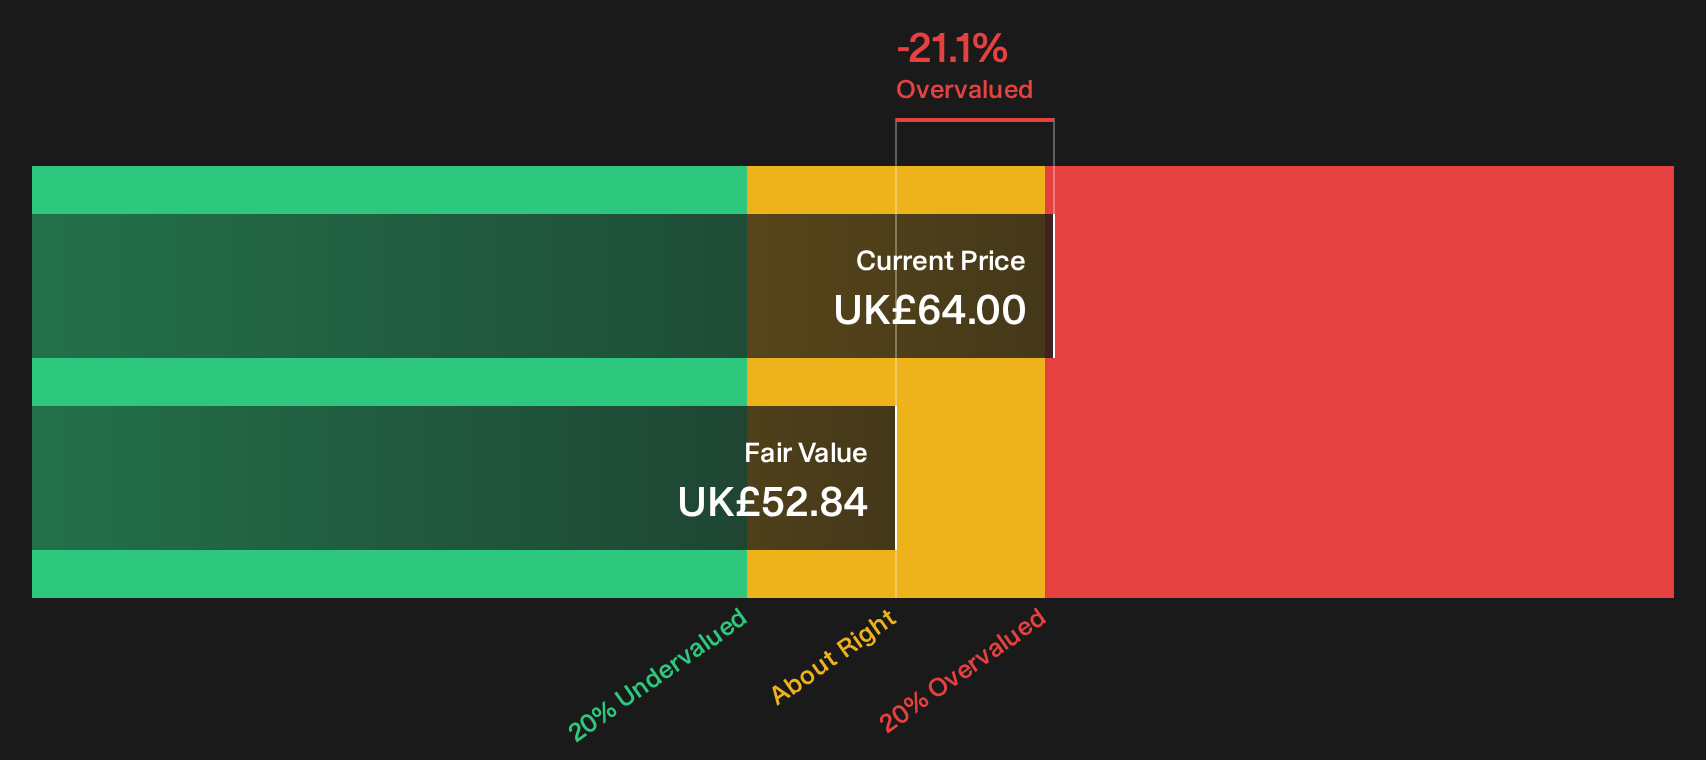
That £75.57 fair value view leans on analyst forecasts and future earnings assumptions. The SWS DCF model tells a different story. On that approach, Rio Tinto Group screens as overvalued, with the current £64.00 price sitting above an estimated future cash flow value of £52.84. Which lens do you trust more when cash flows and forecasts disagree?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split between fair value models and market price leaves you undecided, consider quickly testing Rio Tinto Group against your own checklist using the 2 key rewards and 1 important warning sign.
Want more ideas beyond Rio Tinto Group?
If Rio Tinto Group still leaves you on the fence, broaden your watchlist with a few focused sets of companies that match different investing angles.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (10 results) before capital moves somewhere else.
- Hunt for potential mispricing by reviewing the 10 high quality undervalued stocks so you do not miss candidates trading below their assessed quality.
- Lock in income focused opportunities by checking the 5 dividend fortresses while yields and payers that fit your criteria are still on the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com