
Shimano Stock In Focus After Raised Earnings Guidance
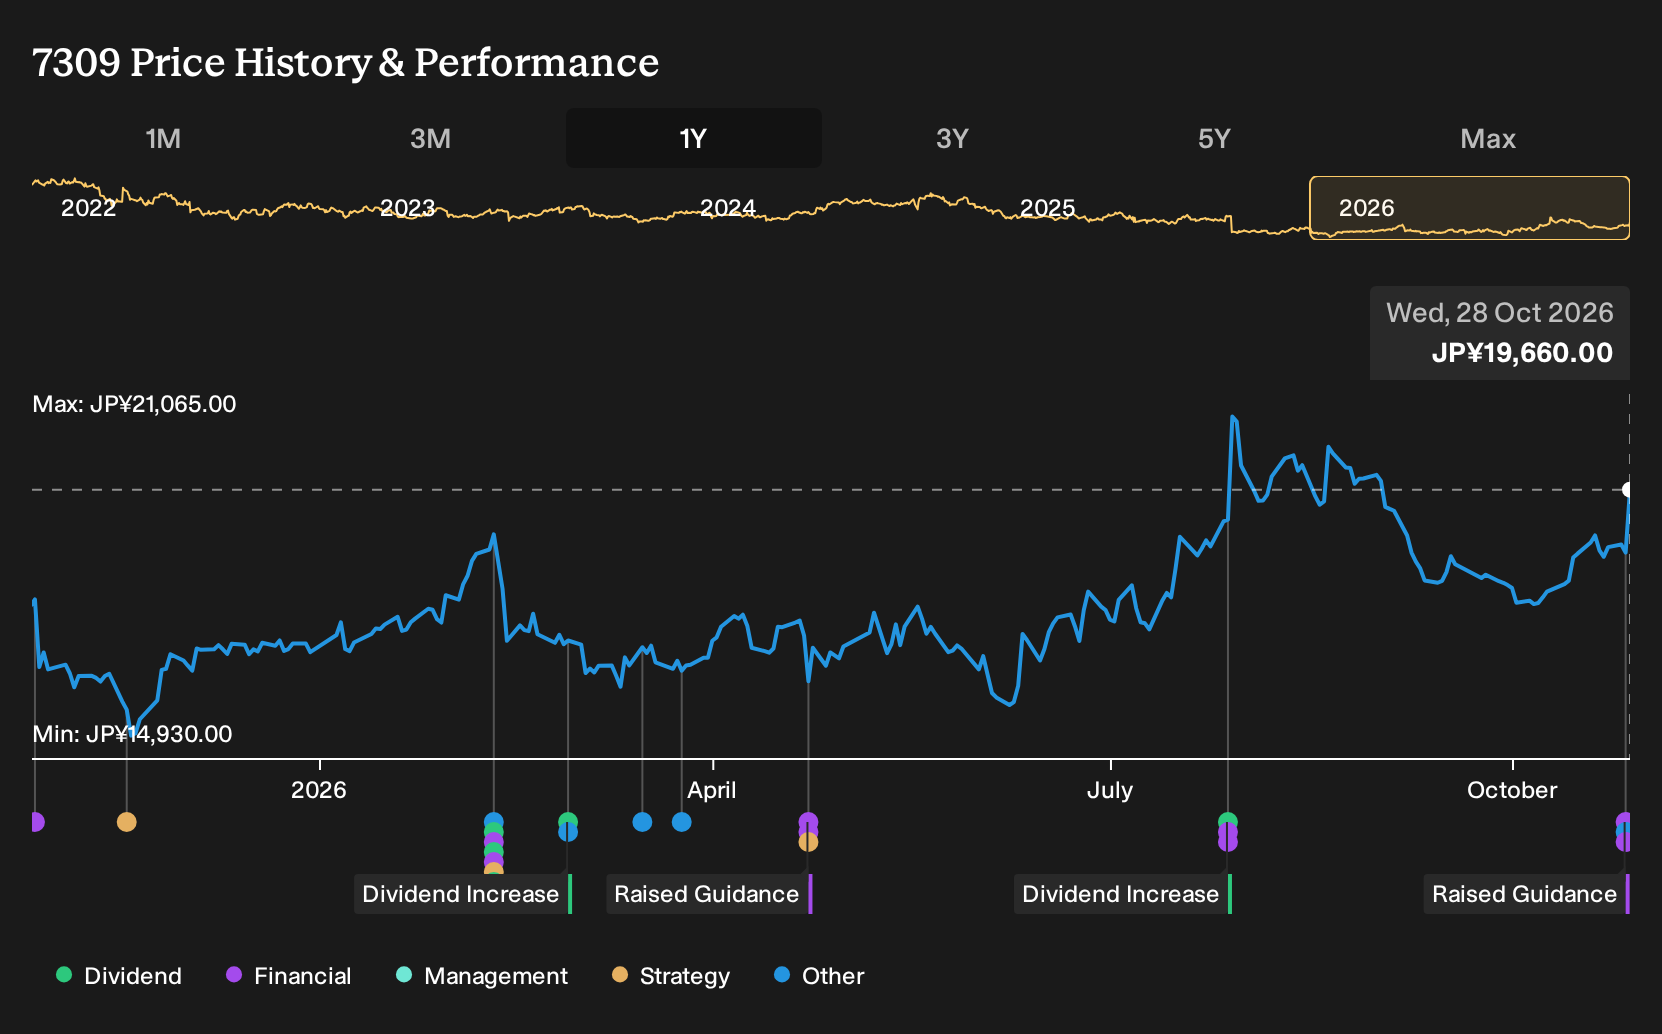
- Shimano reported nine-month 2026 sales of JPY 375,248 million and net income of JPY 40,022 million, and raised full-year guidance while also proposing to shorten director terms to one year at the March 2027 AGM to reinforce accountability.
- Higher earnings guidance is linked to increased demand after inventory adjustments in Europe and China and currency driven profitability. This gives investors a clearer view of how Shimano’s operations are responding to current market conditions.
- The next step is to examine how Shimano’s raised guidance, and the demand and currency factors behind it, could influence the broader investment narrative.
What Is Shimano's Investment Narrative?
To own Shimano, you need to believe this is a resilient specialist in bicycles and fishing gear that can convert product reputation into steady cash generation rather than chasing explosive expansion. The latest guidance lift, tied to demand after inventory adjustments in Europe and China and currency effects, keeps the near term story anchored in operational execution and pricing discipline. Shorter director terms fit that story, since annual re election can keep management more closely aligned with how the business is really performing, not just with a two year rhythm.
In the short term, the key swing factors are how clean those channel inventories stay, how Shimano manages profitability if exchange rate support fades, and how capital is allocated with a seasoned board reviewed every year. The stock already trades on a higher P/E than peer averages, so any wobble in demand or earnings quality can matter quickly. Board accountability may help address that, but it does not remove the biggest operational question that hangs over the next phase of this recovery.
That said, there is one pressure point in the Shimano story that could still catch investors off guard if ...
There's only one way to know the right time to buy, sell or hold Shimano. Head to Simply Wall St's company report for the latest analysis of Shimano's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly JPY 19,414 to JPY 23,529 per share, which already shows how far apart views on Shimano can sit. These retail investors have not yet baked in the new guidance or the tighter director terms, so treat their work as starting points and compare several viewpoints before you decide how Shimano fits your own framework.
Explore another Shimano fair value estimate, including one that suggests it could be worth just ¥19,414.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Shimano research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Shimano. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shimano's overall financial health at a glance.
Looking For More Ideas Beyond Shimano?
If Shimano sits on your watchlist, it can help to compare it with other companies that share similar quality traits or different risk and income profiles. Use the Simply Wall St Screener to widen that view and pressure test your thesis against a broader set of listed businesses.
- For investors who care most about balance sheet strength and fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) that keeps financial resilience front and center.
- If you want to focus on quality that is not yet widely followed, scan the 72 high quality undiscovered gems that match solid financial characteristics with lower market attention.
- For readers prioritizing stability and regular cash returns, filter opportunities through a hand picked set of 29 dividend fortresses that concentrate on income potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com