
What Rockwell Automation Doubters Missed
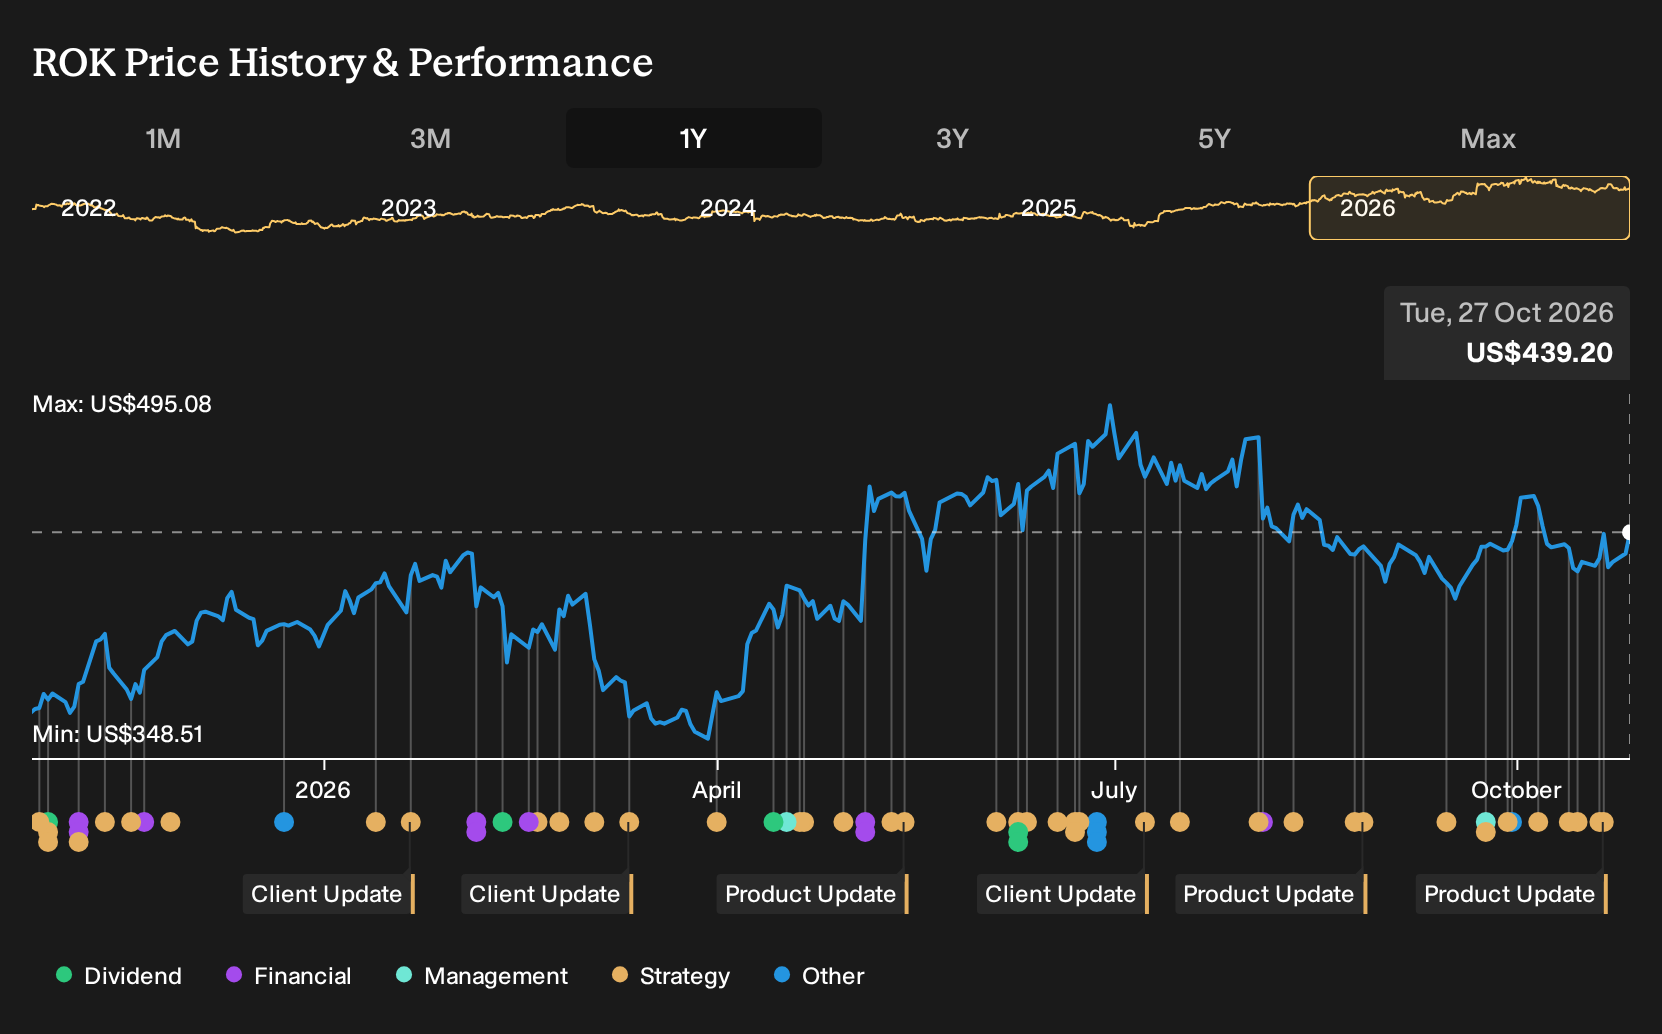
If Rockwell Automation sat on a watchlist instead of in a portfolio over the past year, the result may feel like a miss. Investors who held Rockwell Automation over the past year are up 23.0%, including dividends. That return arrived during a period when earnings reports, guidance raises, and new AI-focused product launches kept hitting the news. The real question is whether the original bet on Industry 4.0, reshoring, and higher recurring software income was visible enough at the start to justify owning it.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Rockwell Automation has already moved. Pinpoint other ways to investigate the theme among 94 robotics and automation stocks.
The Argument Rockwell Automation Investors Had To Weigh
The shares cost US$362 at the start of the period, so anyone considering Rockwell Automation had to decide which story felt more realistic.
The bullish narrative put Fair Value at US$410, 13% above the start price. It leaned on the idea that Industry 4.0, reshoring and a US$2 billion investment plan would support recurring software revenue and recurring margin expansion.
The bearish case set Fair Value at US$229, 37% below the start price. It focused on open-source automation and geopolitical risk as threats that could pressure gross margins and limit international sales growth.
What The Results Changed For Rockwell Automation
Rockwell Automation reported Q3 2026 revenue of US$2.313b and net income of US$407m, higher than US$2.144b and US$294m a year earlier. Net margin moved from 13.7% to 17.6%. That mix of higher sales and a fatter margin lined up more with the optimistic case that focused on recurring software and efficiency, although cyber and geopolitical worries were not really tested here.
The useful takeaway is simple. When a story leans on better profitability, track whether net margin and absolute profit both move in the direction the pitch implied rather than relying on headlines about guidance or new products.
What Rockwell Automation's Price Already Assumes
Today Rockwell Automation trades at US$439, with the current Narrative placing Fair Value below that level rather than above it. The argument leans on a strong installed base, software subscriptions and a leaner cost structure after recent restructuring.
The key question is what must keep going right for that price to hold. A buyer today would need to be comfortable that premium valuation persists even if large capital projects stay slower to convert than hoped.
"What makes Rockwell special is the installed base. Its Logix controllers (ControlLogix and CompactLogix, programmed in Studio 5000) run production lines in thousands of North American plants."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Rockwell
Rockwell shows how factories automate. Your next question is what keeps the digital side running.
Every AI project still needs physical infrastructure that can handle rising heat and intense power demand.
One specialist focuses on the gear that keeps data centres cooled, powered and stable for those workloads.
Its hardware and software help operators manage power flows, control temperature and maintain uptime as server racks get denser.
As AI projects scale, that kind of behind the scenes provider could see its role quietly expand.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 96% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com