
Are Strong Earnings Altering The Investment Case For Inwido (OM:INWI)?
- Inwido reported third quarter 2026 sales of SEK 2,724 million and net income of SEK 202.6 million, with higher basic earnings per share from continuing operations than a year earlier.
- The nine month figures show sales of SEK 7,527.8 million and net income of SEK 410.1 million. This indicates that earnings quality and scale play an increasingly important role in how investors judge Inwido’s operating model.
- We will now examine how Inwido's investment narrative is influenced by the third quarter uplift in sales and profitability.
Compare Inwido's third quarter earnings strength with other businesses that show similar financial resilience by scanning our curated list of list of solid balance sheet and fundamentals (207 results).
Inwido Investment Narrative Recap
To own Inwido, you need to be comfortable with a renovation heavy story that leans on energy efficiency rules, social housing projects and e commerce channels to support earnings. The recent third quarter, with SEK 2,724 million in sales and SEK 202.6 million in net income, points to resilient operations rather than a radical shift in trajectory.
The key near term swing factor is still how well Inwido converts its order backlog into profitable delivery while managing cost inflation. The main risk continues to be weaker consumer demand in the UK and Finland and any ongoing material cost pressure that squeezes margins despite the stronger recent earnings.
Among the broader drivers around this update, project and social housing activity looks closest to the current earnings story. Inwido has long term Scottish contracts including a £50 million five year Sidey Solutions order and an additional £10 million project booked in the third quarter of 2026, which can provide factory base load as deliveries progress.
For you as a shareholder, these frameworks matter because they relate directly to execution risk and earnings stability. If Inwido keeps fulfilling these contracts efficiently and maintains its higher margin e commerce contribution, the recent EPS performance gives more data on how the business handles demand pockets and cost pressures across its regional mix.
Inwido's analyst narrative points to revenues of SEK 12.3b and earnings of SEK 993.3 million by 2029, built on forecast yearly top line growth of 7.4% and an earnings increase of SEK 416.6 million from SEK 576.7 million today.
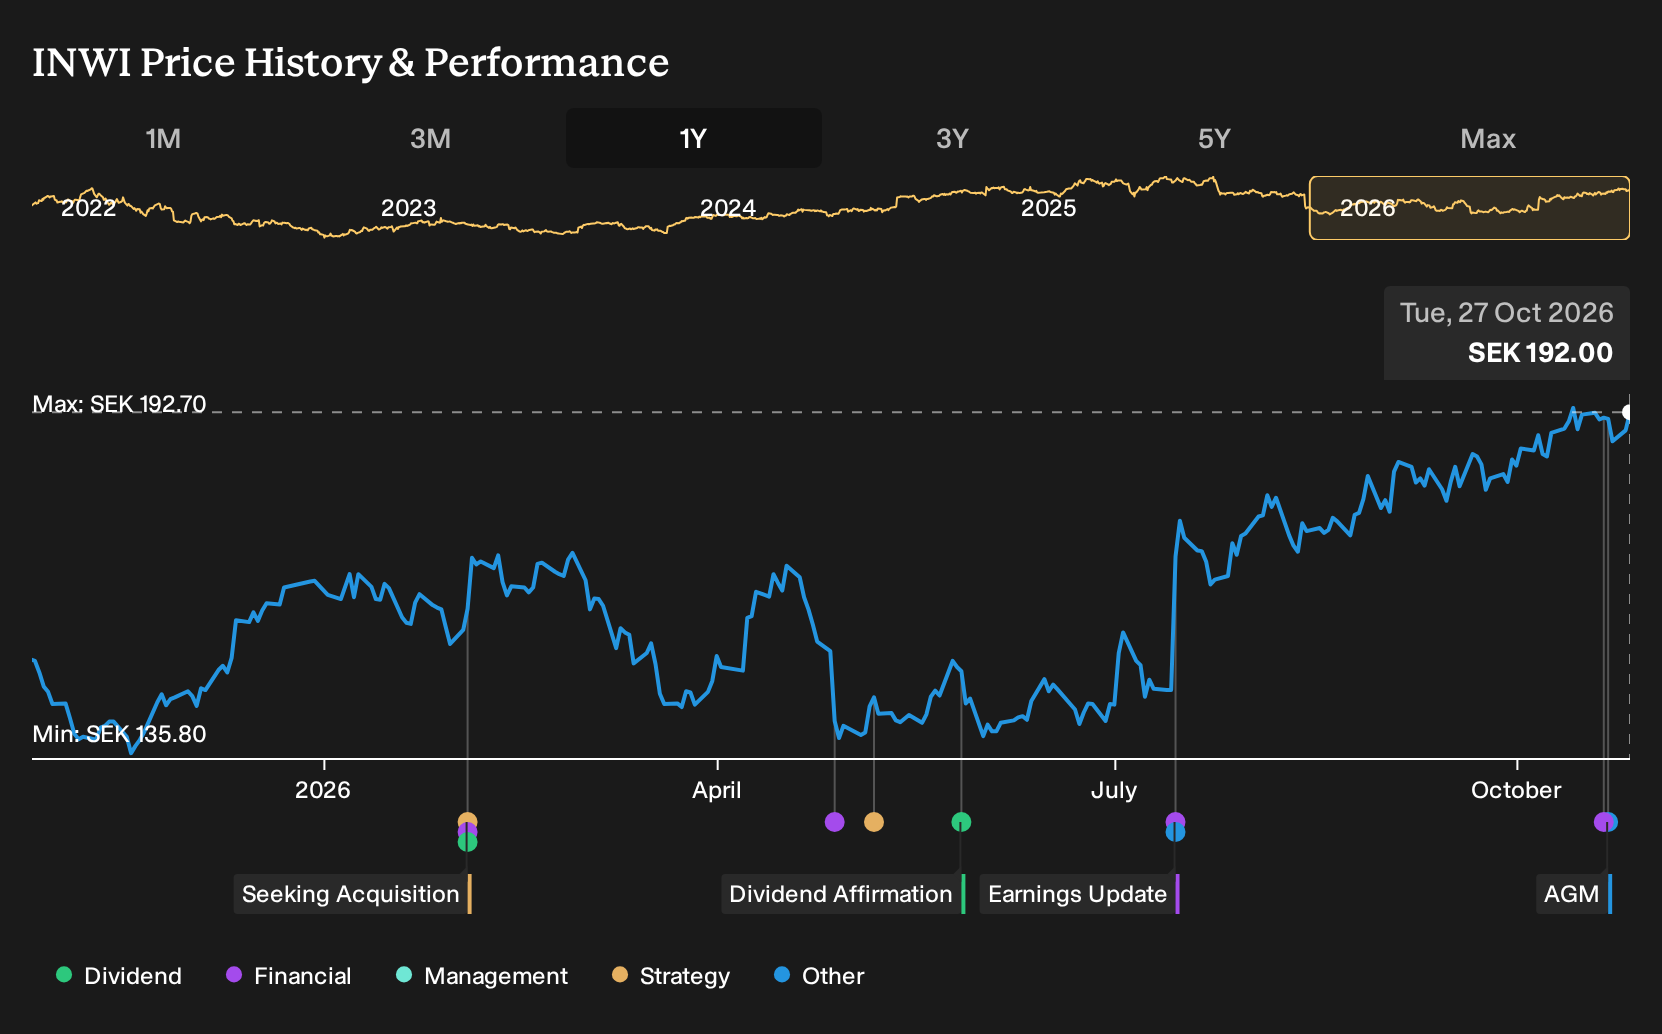
Uncover how Inwido's fair value indicates a 17% potential upside to its current price before the gap closes.
Exploring Other Perspectives
Fair value estimates for Inwido from 2 members of the Simply Wall St Community range from SEK 225.33 to SEK 338.76 per share, so opinion already stretches widely before the latest earnings. When you set that against risks around UK and Finnish demand or material cost pressure, you have clear reasons to explore several alternative viewpoints.
Explore another Inwido fair value estimate, including one that suggests as much as 76% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Inwido research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Inwido. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Inwido's overall financial health at a glance.
Looking for more Inwido sized investment ideas?
If Inwido's profile appeals to you, it can help to line it up against other companies with clear financial traits, then decide where the risk and reward balance feels right for your portfolio.
- If capital preservation matters most, consider a screener focused on resilience and steady fundamentals with the 223 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, compare Inwido with other potential opportunities through the 195 high quality undervalued stocks.
- If you want to expand beyond familiar tickers, widen your research funnel by scanning the 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com