
Skandinaviska Enskilda Banken (OM:SEB A) Could Be 10% Undervalued As US Review Ends
Skandinaviska Enskilda Banken (OM:SEB A) is in focus after resolving historic US anti money laundering reviews tied to its Baltic operations, while releasing third quarter results that show relatively stable interest income and earnings.
Recent moves in Skandinaviska Enskilda Banken’s share price tell a mixed story. The stock has slipped about 11% over the past month and is down roughly 5% over 90 days, even though the year-to-date share price return is positive at 5.33% and the 1-year total shareholder return of 22.22% builds on very strong 3-year and 5-year total shareholder returns of 107.33% and 117.10%. This pullback around the time of the US anti money laundering settlement, fresh earnings and a new NOK 2b floating rate bond issue suggests some investors are reassessing short term risk, while longer term holders have still seen substantial value creation through both price gains and distributions.
See how Skandinaviska Enskilda Banken compares with peers by reviewing our hand picked 223 resilient stocks with low risk scores that also show resilient performance through regulatory headlines and earnings seasons.
Skandinaviska Enskilda Banken now trades below both its average analyst target and one estimate of intrinsic value, after a sharp pullback around the US settlement. So where does fair value realistically sit within that range?
Most Popular Narrative: 10.2% Undervalued
Against the last close of SEK208.5, the most followed narrative anchors Skandinaviska Enskilda Banken’s fair value at SEK232.25, framing today’s pullback as a discount that hinges on fee income growth and tight cost control actually playing out.
SEB's cost consolidation, reflected in a lower 2026 full year cost target of SEK 33.3b and a current run rate tracking below that level with fewer FTEs, underpins the earlier aim to keep a tight grip on the cost base and sustain positive jaws, which feeds through to earnings.
See why 24 investors see Skandinaviska Enskilda Banken as 10% undervalued.
Result: Fair Value of SEK232.25 (UNDERVALUED)
Still, that storyline can crack if fee heavy capital markets and card activity cool meaningfully, or if rising levies and compliance expenses erode the cost discipline behind it.
Find out about the key risks to this Skandinaviska Enskilda Banken narrative.
Another View: What Skandinaviska Enskilda Banken’s P/E Is Telling You
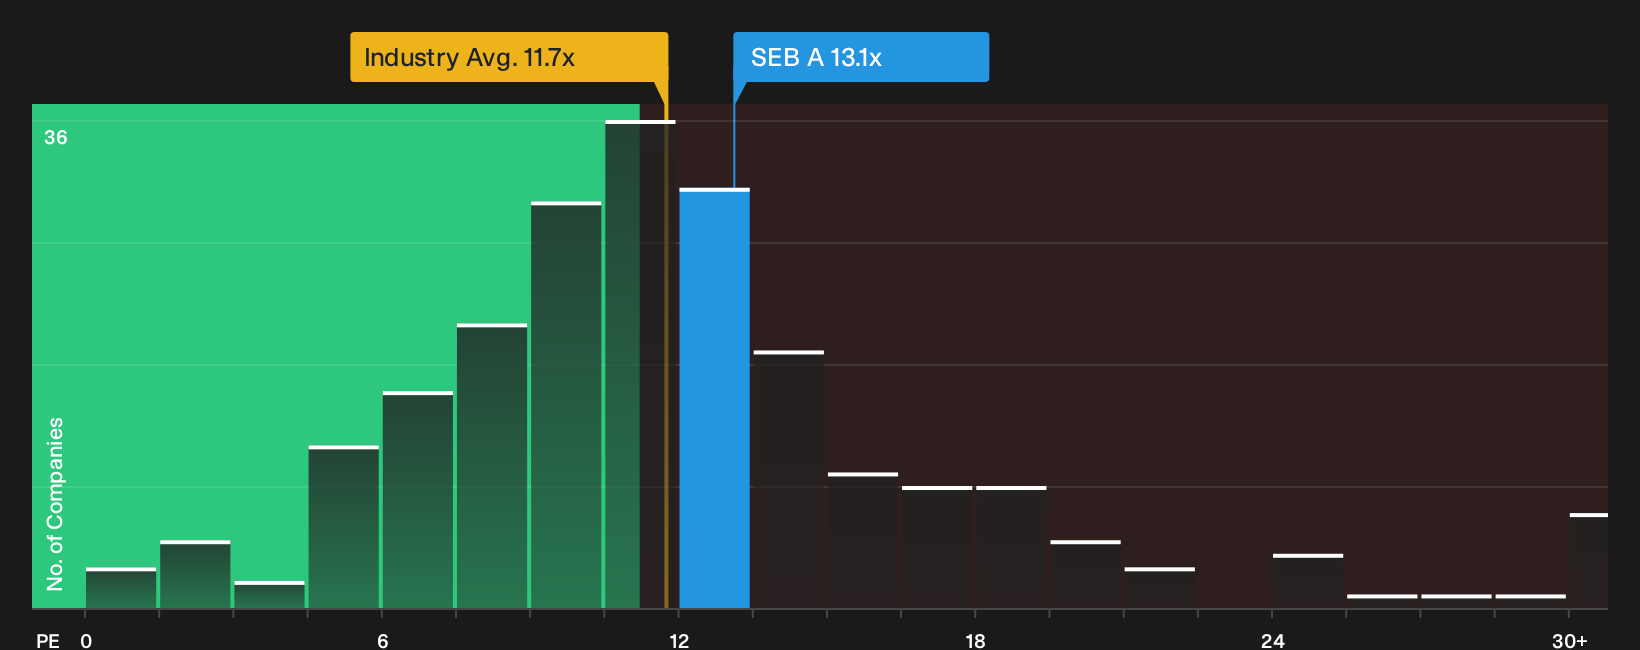
The first storyline presents Skandinaviska Enskilda Banken as 10.2% undervalued against a SEK232.25 fair value. A different lens uses the P/E ratio. At 13.1x, the shares trade richer than both the European banks industry on 11.6x and a fair ratio of 13.4x, which narrows the margin for error. If sentiment on banks cools, how much patience would you really have for that premium?
To pressure test that premium and see what the numbers imply, take a look at the valuation breakdown in our detailed P/E view. Then compare it with your own expectations for earnings resilience and risk before you place too much weight on any single metric, including our own fair ratio view from See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Skandinaviska Enskilda Banken is clearly mixed, so treat this as your cue to move fast, check the data and weigh both sides yourself, then go straight to the breakdown of 2 key rewards and 1 important warning sign
Looking for more Skandinaviska Enskilda Banken style investment ideas?
If you are serious about sharpening your watchlist, use the same data driven tools across sectors and let fresh ideas come to you, not the other way around.
- Target potential mispricing by scanning a curated pool of high quality companies using the 195 high quality undervalued stocks and see which ones deserve a closer look.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (207 results) that can help anchor a more resilient portfolio when conditions change.
- Spot opportunities others might ignore by filtering through a focused set of 610 high quality undiscovered gems before they appear on every investor’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com