
3 Dividend Stocks With At Least 3% Yield
Higher interest rates are back in focus after the Bank of Canada lifted its key policy rate again and flagged that further hikes remain possible. When borrowing costs stay higher, dependable cash payouts suddenly look more attractive. Reliable dividend payers with yields above 3% and solid coverage can offer a steadier stream of income. This article highlights three such income workhorses from our high yield, quality focused filter.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding businesses where the dividends look well covered and consistent. However, if you want the absolute best, these 5 dividend aristocrats stocks are the cream of the crop.
NIKE (NKE)
Overview: NIKE is a global sportswear group that designs, makes, and sells athletic footwear, apparel, and gear, using those cash flows to fund its regular dividend.
Operations: NIKE generates most of its revenue from the NIKE Brand in North America at about US$20.6b, with additional multi billion dollar sales across Europe, Middle East and Africa, Asia Pacific and Latin America, Greater China, and Converse.
Market Cap: US$56.3b
For a dividend screen built around yield and consistency, NIKE matters because its regular payout depends directly on how effectively its sport focused business converts sales into cash.
"The biggest risk is that "restored" settles at a 9 to 11% margin, not 13%. If the dividend is defended out of cash, net cash could turn to net debt by around FY29 in the bear case."
What happens if a single pressure on NIKE’s cash generation shifts will do a lot to determine how reliable that income stream feels.
That uncertainty around cash generation is exactly why reading the full narrative for NIKE can help you see where NIKE’s payout risk and upside might be quietly shifting.

Hershey (HSY)
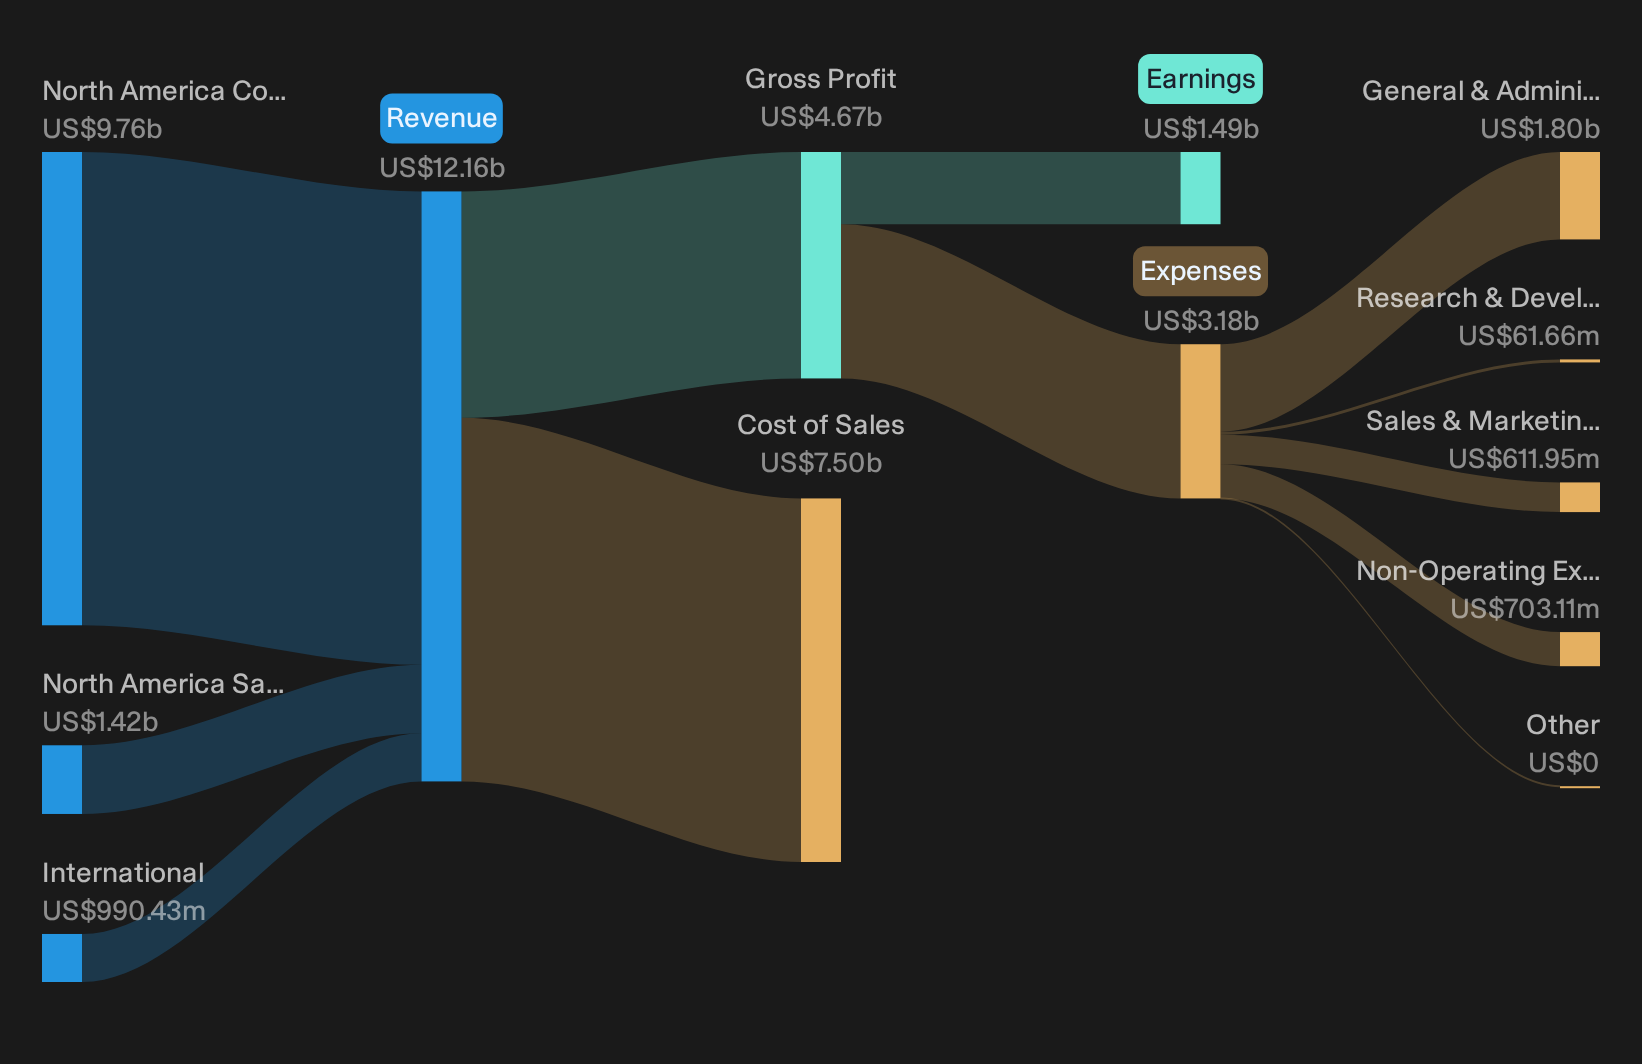
Overview: Hershey is a global confectionery and snacking group whose cash-rich chocolate and snack brands support a well-covered dividend yield above 3%.
Operations: Hershey generates about US$9.8b from North America Confectionery, US$1.4b from North America Salty Snacks, and roughly US$1.0b from International markets.
Market Cap: US$33.8b
Hershey matters for income investors because its everyday chocolate and salty snacks convert into steady cash flows that can fund reliable, growing dividends.
"The forward thesis rests on three assumptions: that cocoa is structurally elevated but normalizing, allowing operating margin to recover toward a ~24% ceiling over the decade; that the One Hershey strategy extends the moat into salty, functional, and international adjacencies to sustain mid-single-digit (~3.5%) revenue growth."
What happens if a single pressure point on Hershey’s input costs shifts will do a lot to shape how durable that income stream feels.
If that pressure eases or accelerates, the full narrative for Hershey shows how Hershey’s cash generation, reinvestment options, and dividend ambitions could quietly be reshaped.
Global Ship Lease (GSL)
Overview: Global Ship Lease owns and leases mid sized and smaller containerships on fixed rate contracts, using charter backed cashflows to support its dividend.
Operations: Global Ship Lease generates about US$761 million in revenue from transportation shipping activities, primarily through fixed rate containership charters.
Market Cap: US$1.5b
Global Ship Lease brings something different to this dividend screen, with multi year charter contracts helping to underpin cash payouts for income focused investors.
"The company’s contracted revenue base has expanded to more than US$3.2b with multi year cover, while leverage has fallen sharply and credit ratings remain supportive."
What happens if a single assumption about future charter demand shifts will have a major influence on how secure that payout feels.
If that assumption starts to shift, the full narrative for Global Ship Lease explains how Global Ship Lease’s contracted revenue, capital plans, and payout risk could be quietly decoupling from headline shipping sentiment.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories build momentum while the best entry points quietly drop out of reach. Scan these under the radar lists now and explore potential opportunities.
- Review a curated set of 5 dividend fortresses to evaluate durable income streams before yields change as more investors take notice.
- Check 55 AI infrastructure stocks to observe early infrastructure trends while demand for compute capacity is still being priced in gradually.
- Review 16 top copper producer stocks to track metal producers tied to long term demand before supply conditions and new projects influence expectations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com