
Charter Communications (CHTR) Stock Stays Cheap After an 85% Five Year Slump
Charter Communications has seen its share price fall sharply in recent years, and that slide puts fresh focus on whether the current market value lines up with what the company is earning. With the stock under pressure and investors reassessing the story after major corporate moves, the central issue is how the earnings profile compares with today's price.
- Over the past 5 years the share price has fallen 84.6%, which puts a lot of weight on the question of what the business is realistically earning for shareholders today.
- The Cox Communications acquisition has lifted both share count and net debt, which can reshape how investors weigh future earnings against a more leveraged balance sheet and a larger equity base.
- Your read on Charter Communications is one view; the desks covering it have another. See what analysts think Charter Communications's shares could be worth.
The stock's next move may depend on whether Charter Communications' current earnings are strong and dependable enough to justify where the share price now sits.
If you want more context around whether Charter Communications' earnings-based story appeals to you, it can help to compare it with 29 high quality undervalued stocks.
Does Charter Communications Look Undervalued on Earnings?
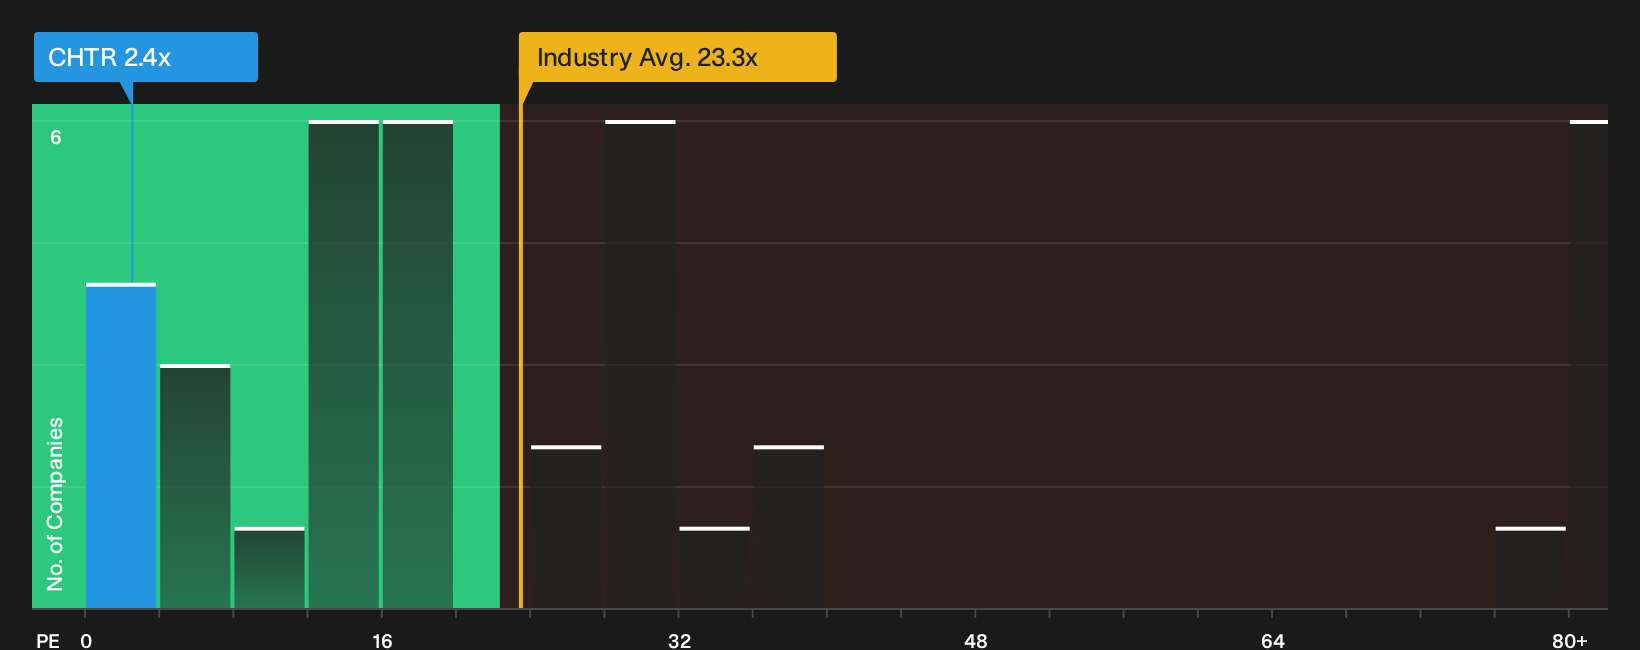
The P/E ratio suits Charter Communications because the story investors are debating is primarily about earnings power versus price. On this measure, the stock trades on roughly 2.4x earnings, which is far below the Media industry average of about 23.3x and also well under the peer group on roughly 15.1x. The gap is large enough that it signals investors are applying a heavy discount to the current profit stream.
That discount comes as the Cox Communications deal has pushed up leverage and coincided with broadband subscriber losses, so the market may be treating today’s earnings as fragile. The fair multiple implied by the valuation framework, which weighs growth potential, margins, size and risk, sits meaningfully above the current 2.4x P/E. As a result, the shares screen as undervalued on this yardstick. Because the Cox integration has brought higher debt and transition costs without lifting near term sentiment, the stock now trades at an earnings multiple that lags both peers and what this model suggests could be justified. Explore the numbers behind Charter Communications's P/E valuation.
The Charter Communications Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Charter Communications pick up where the valuation puzzle leaves off by spelling out which assumptions about future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. They sit on the Community page so that each storyline ties a fair value to a specific mix of potential catalysts and risks that you can track as events unfold.
Community views on Charter Communications split sharply, with one camp arguing the valuation is far too low and the other seeing material downside risk.
Bull case: 64% undervalued
"With the accurate share count and the embedded value in the FMV of the debt, my estimate of EV is roughly 95B…"
Discover why this Narrative puts Charter Communications at 64% undervalued.
Bear case: 54% overvalued
"Although Charter Communications is promoting converged connectivity with mobile and video bundles that reduce churn, the company’s own expectation for around a 1% decline in standalone 2026 EBITDA shows that broadband subscriber and ARPU pressure plus rising controllable costs could prevent the bundle strategy from translating into healthier earnings or margin trends…"
Explore why this Narrative puts Charter Communications at 54% overvalued.
One more Charter Communications check investors should not skip
Valuation only tells part of the story for Charter Communications, because Simply Wall St's broader review has also flagged specific risk checks that deserve your attention before you decide what to do next. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com