
Is Ambarella (AMBA) Undervalued On Edge AI Growth Or Already Fairly Priced?
Ambarella (AMBA) is back in focus after recent trading left the stock down 7.7% over the past month and 3% over the past 3 months, drawing greater attention to its AI-focused semiconductor business.
Across a longer window, Ambarella’s share price is down 10.7% year to date and the 1 year total shareholder return is lower by 22.2%. A stronger 3 year total shareholder return of 49.2% suggests longer term holders have seen periods of better momentum than the recent pullback implies.
Scan how Ambarella compares with other AI hardware players by jumping into a curated list of 55 AI infrastructure stocks that are drawing attention for their role in powering compute heavy workloads.
Ambarella now trades at a meaningful discount to analyst targets and estimated fair value, even after a multi quarter slide. Is that caution grounded in the current fundamentals or has sentiment pushed the stock too far?
Most Popular Narrative: 24.9% Undervalued
Against a last close of $67.12, the most followed narrative pins Ambarella’s fair value at $89.36, pointing to a sizeable valuation gap that rests on edge AI traction and future earnings power rather than current profitability.
Sharply increasing demand for AI-powered edge devices, including portable video, robotics (notably aerial drones), and edge infrastructure, has led to a rapid expansion of Ambarella's addressable markets, as evidenced by record edge AI revenue and multiple recent, diversified design wins. This is catalyzing strong, sustained revenue growth and positions Ambarella to benefit further as additional vertical applications for edge AI proliferate.
See why 42 investors see Ambarella as 25% undervalued.
Result: Fair Value of $89.36 (UNDERVALUED)
Still, that underpinned fair value view depends on Ambarella easing its reliance on cyclical IoT demand and managing customer concentration risk, which could quickly hit revenue.
Find out about the key risks to this Ambarella narrative.
Another View: Ambarella On Sales-Based Valuation
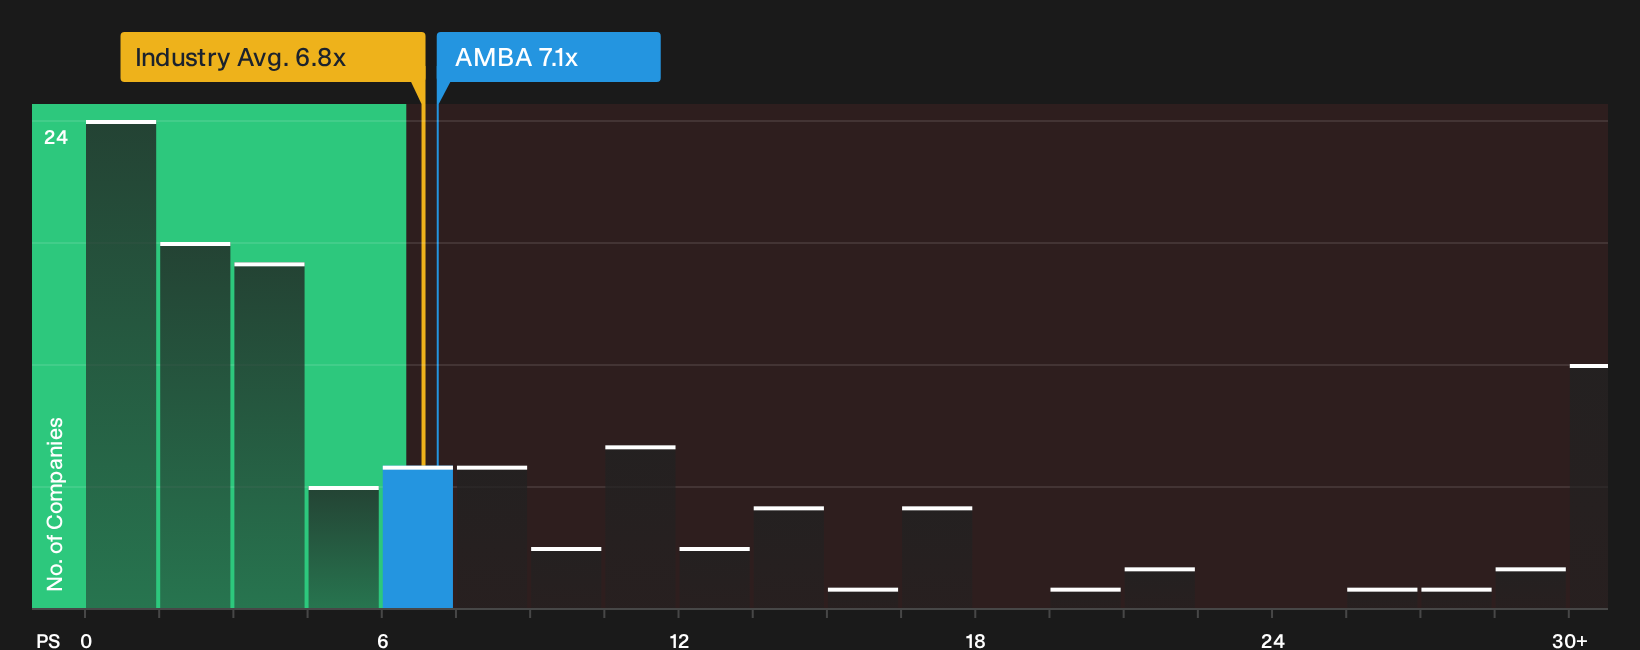
While the SWS model points to Ambarella trading below estimated future cash flow value, the simpler P/S check tells a tighter story. The stock changes hands at 7.1x sales, compared with a 6.8x P/S for the US Semiconductor group and a 5.6x fair ratio based on the model.
That gap means investors are already paying a premium to both sector and peer averages, even as Ambarella is unprofitable and forecast to stay that way over the next 3 years. The question is whether edge AI momentum and projected top line growth justify holding that mark up if expectations wobble.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ambarella can feel confusing, especially when you see both concerns and bright spots in the same chart. Act quickly on that uncertainty by reviewing the 2 key rewards and 2 important warning signs.
Looking for more Ambarella style investment ideas?
If Ambarella has you rethinking where the real opportunities might be, do not stop at a single ticker when a wider menu of ideas is right there.
- Target resilient upside by scanning a curated set of 21 high quality undiscovered gems that pair strong fundamentals with quieter market attention.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard by weak financial footing when conditions turn.
- Lean into value discipline by filtering for 29 high quality undervalued stocks that combine quality metrics with prices that still look reasonable on the numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com