
Air France KLM (ENXTPA:AF) Could Be 86% Undervalued After Route Cancellations
Air France-KLM (ENXTPA:AF) has moved to cancel flights to seven international destinations from November 2026, citing high fuel costs, tougher competition, and shifting demand toward rail on shorter routes.
Recent price action has been weak, with Air France-KLM’s share price down about 11.7% over the past month and roughly 16.6% over 90 days. The 1-year total shareholder return has fallen a smaller 6.1%, signalling fading short term momentum despite milder longer term damage for holders.
Scan beyond Air France-KLM and compare its recent setbacks with a curated group of 223 resilient stocks with low risk scores that may be holding up better under similar industry pressures.
After a share price slide this steep and route cuts this aggressive, are you looking at Air France-KLM with most of the upside still in front of you, or already in the rear-view mirror as valuation resets get tested next?
Preferred Multiple of P/E 2.5x: Is it justified for Air France-KLM?
Air France-KLM currently trades on a P/E of 2.5x, which looks inexpensive against both its peers and the wider airlines sector given the latest close at €10.29.
The P/E ratio compares the share price with earnings per share, so it effectively tells you how many euros investors are willing to pay for each euro of profit. For a carrier like Air France-KLM, where earnings can be sensitive to fuel, demand, and capacity decisions, that multiple often reflects the market’s view of how reliable those profits are.
Based on Simply Wall St’s work, Air France-KLM is described as trading at good value compared to peers and industry, with its 2.5x P/E well below the global airlines average of 11.8x and the peer group average of 18.4x. The estimated fair P/E of 13.2x is also far above where the shares change hands, which indicates a level the market could potentially move toward if earnings hold up and sentiment improves.
Explore the SWS fair ratio for Air France-KLM.
Result: Price-to-earnings of 2.5x (UNDERVALUED)
Still, Air France-KLM faces pressure from high fuel costs and rising competition on long haul routes, which could squeeze earnings and keep investor confidence fragile.
Find out about the key risks to this Air France-KLM narrative.
Another View on Air France-KLM’s Value
The P/E of 2.5x makes Air France-KLM look cheap, yet the SWS DCF model points to a very different picture. On that approach, the share price of €10.29 sits well below an estimated future cash flow value of €73.33. This is a very large gap that raises its own questions about risk and realism.
When two methods both flag undervaluation but with such different magnitudes, it puts the focus on what you trust more: today’s earnings or long term cash flow assumptions.
Look into how the SWS DCF model arrives at its fair value.
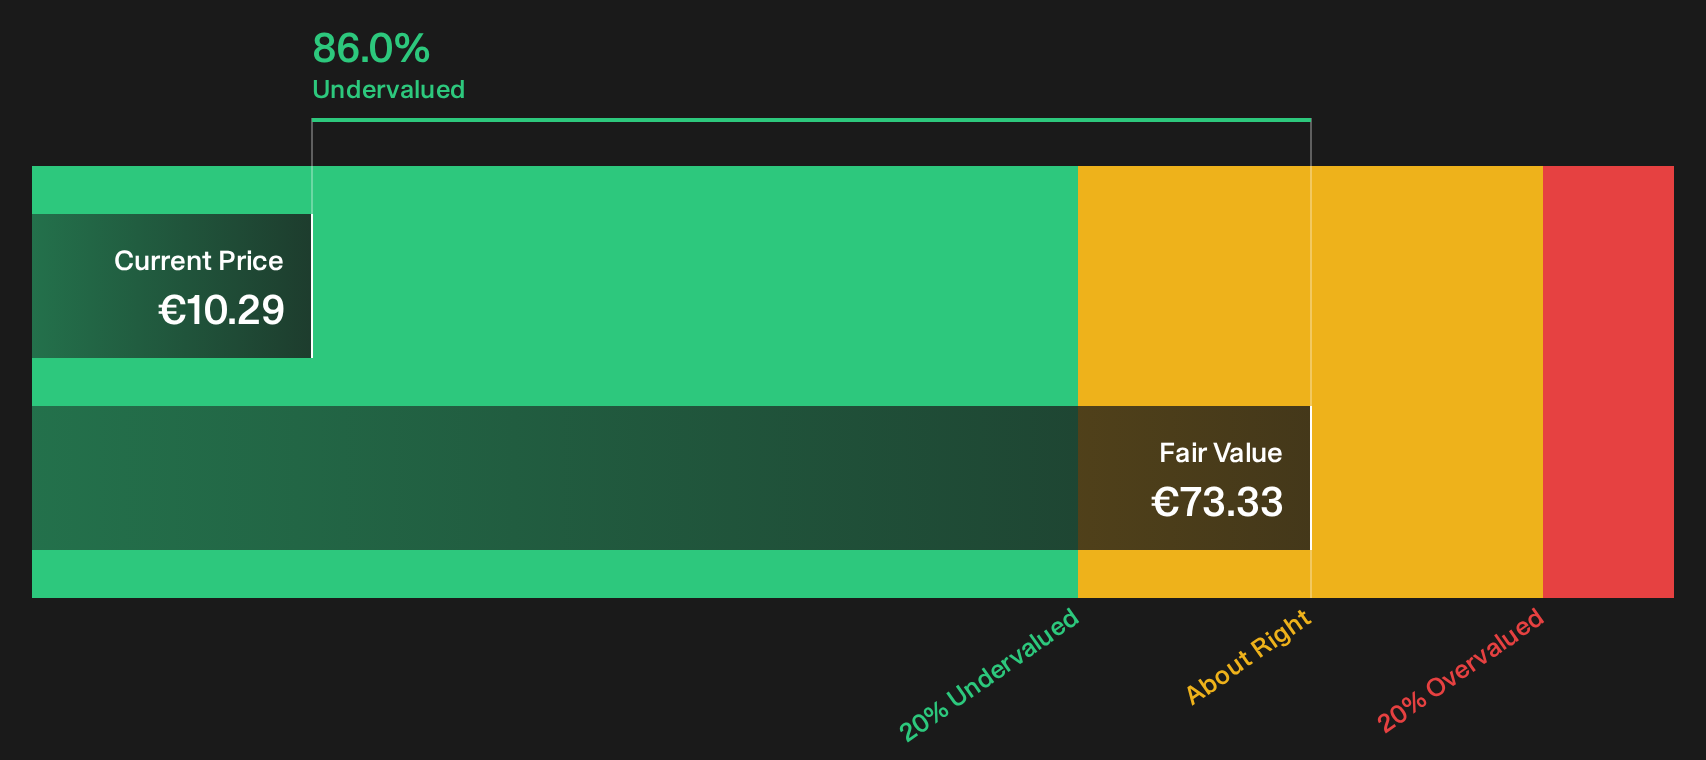
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Air France-KLM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The tone of this piece is cautious for good reason, yet the data can support more than one story depending on what you focus on. Act quickly, review the full picture, and weigh those potential bright spots for yourself by checking the 4 key rewards
Looking for more investment ideas beyond Air France-KLM?
Do not stop with Air France-KLM. Broaden your watchlist with fresh ideas that match your risk profile, income needs, and appetite for mispriced opportunities.
- Target potential mispricings by scanning a curated set of 195 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect underlying performance.
- Build a steadier income stream by focusing on companies from a rigorously filtered group of 224 dividend fortresses backed by consistent payout histories and financial strength.
- Dial back portfolio stress and concentrate on durability by reviewing a hand picked 223 resilient stocks with low risk scores that may hold up better when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com