
Should Higher Nine Month Earnings Require Action From BCP Shares Investors?
- Banco Comercial Português reported net income of €873.7 million for the nine months to 30 September 2026, with basic and diluted earnings per share from continuing operations of €0.057, compared with €775.92 million and €0.05 a year earlier.
- The combination of higher net income and improved earnings per share indicates that Banco Comercial Português converted its operations into profit more efficiently over the period.
- We will look at how Banco Comercial Português's investment narrative is affected by the increase in earnings per share.
Scan how Banco Comercial Português's earnings story compares with other financially solid banks by checking the hand picked list of solid balance sheet and fundamentals (207 results) in the same region.
Banco Comercial Português Investment Narrative Recap
To own Banco Comercial Português, you need to be comfortable with a classic retail and corporate banking story that relies on loan growth in Portugal and Poland, disciplined risk costs and tight expense control. The latest nine month earnings, with net income of €873.7 million and earnings per share of €0.057, support that operating thesis rather than transform it.
In the short term, the key swing factor is how net interest income holds up if rate cuts in core markets press on margins. The biggest near term risk sits in credit quality for SME and corporate books and in Mozambique exposures, where any renewed stress could quickly dilute the earnings progress just reported.
The most relevant information here is the earnings announcement for the nine months to 30 September 2026. Banco Comercial Português reported net profit of €873.7 million, with both basic and diluted earnings per share from continuing operations at €0.057, versus €775.92 million and €0.05 a year earlier. That provides a clearer snapshot of current earning power.
In terms of catalysts, this update ties directly into the existing narrative around loan growth, digital usage and lower legal costs in Poland feeding into higher profitability. On the risk side, it also refreshes the base from which you judge pressures such as potential margin compression, one off items and any future regulatory or tax changes in Portugal, Poland and Mozambique.
Banco Comercial Português' current earnings are quoted at €1.0 billion, while analysts collectively project earnings of €1.5 billion and revenue of €4.6 billion by 2029. This implies forecast revenue growth of 7.7% per year and an earnings increase of about €500 million from today.
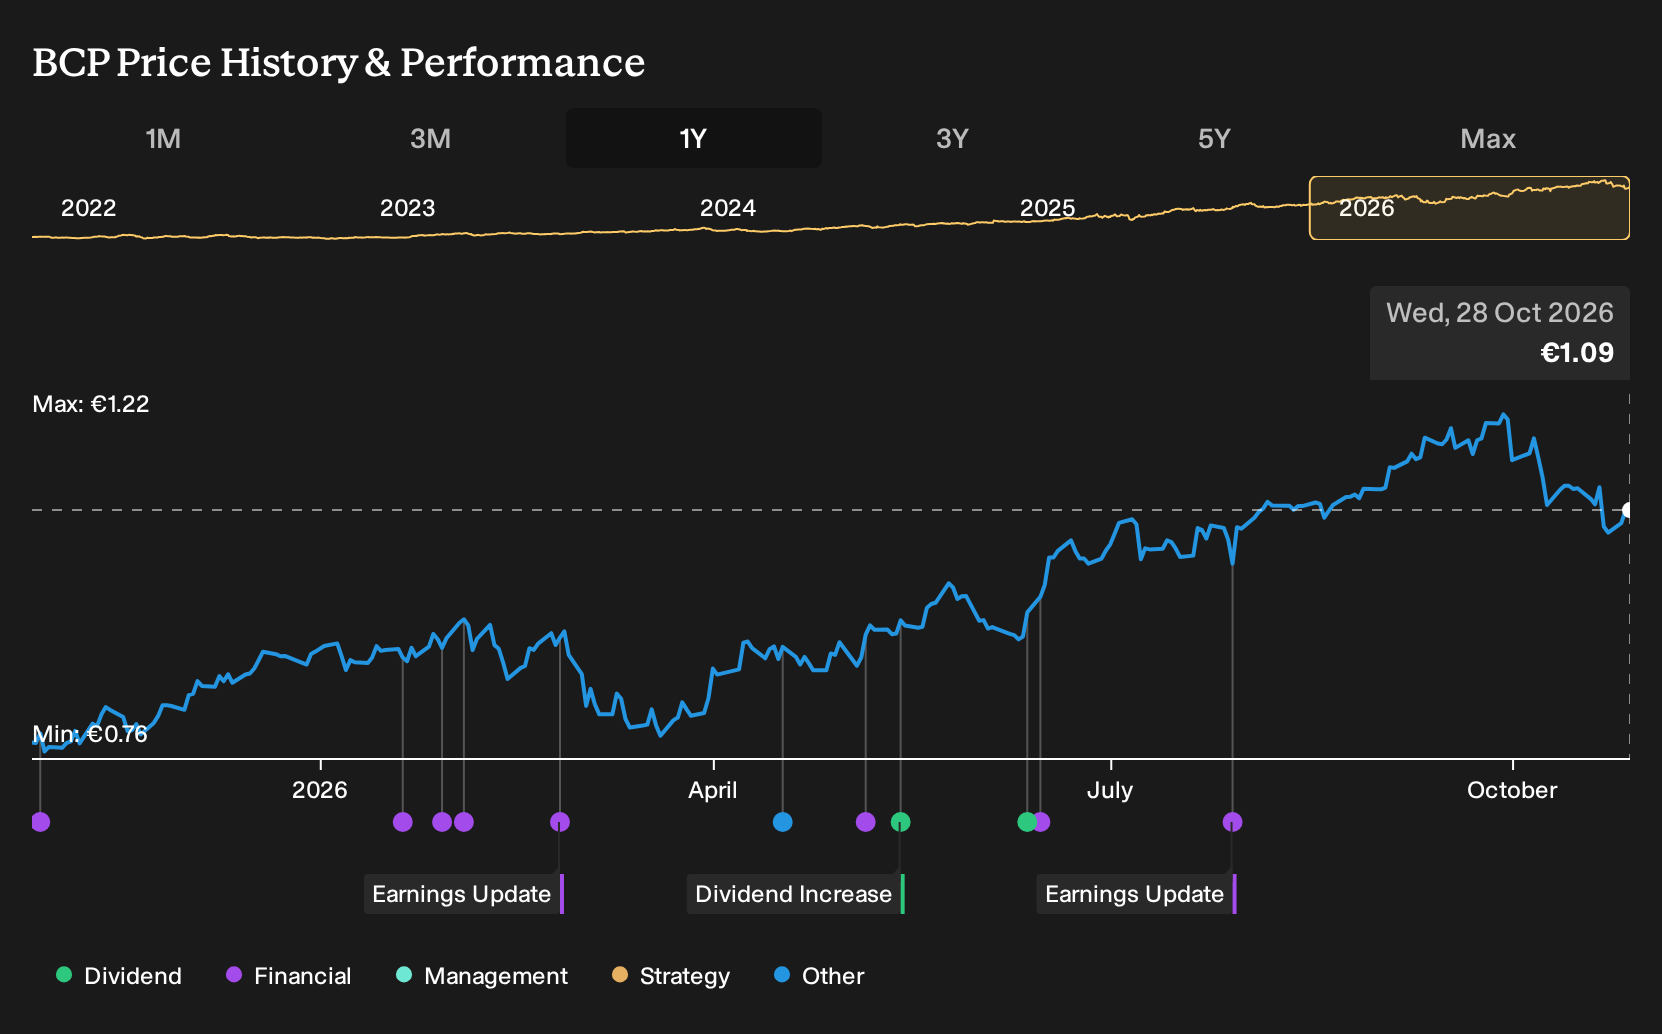
Uncover why Banco Comercial Português' fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between €1.20 and about €1.43 per share, which already shows how far opinions on Banco Comercial Português can spread. These views were set before the latest earnings and interest rate risks, so use them as starting points and compare several alternative takes yourself.
Explore 2 other Banco Comercial Português fair value estimates, including one that suggests as much as 31% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco Comercial Português research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Banco Comercial Português. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Comercial Português' overall financial health at a glance.
Looking for more Banco Comercial Português style investment ideas?
If you want to widen your watchlist beyond Banco Comercial Português, the Simply Wall St Screener can help you quickly filter the market for different types of opportunities that fit your own approach.
- If capital preservation is your priority, start with a group of companies that score well on financial resilience through the 223 resilient stocks with low risk scores.
- If value is your focus, check out businesses that combine quality fundamentals with pricing that may appeal to bargain hunters by using the 195 high quality undervalued stocks.
- If you enjoy hunting for under-the-radar ideas, broaden your search with a curated 610 high quality undiscovered gems that surfaces lesser known stocks with solid numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com