
Clean Harbors (CLH) Stock Ignores Record Q3 Earnings Margin Surge
Clean Harbors came into Q3 2026 with a stock that had gone almost nowhere over the past month and only slightly slipped over the past quarter. The price barely budged on the day of the release, up just 0.2% to about US$313, even as the company posted record profitability.
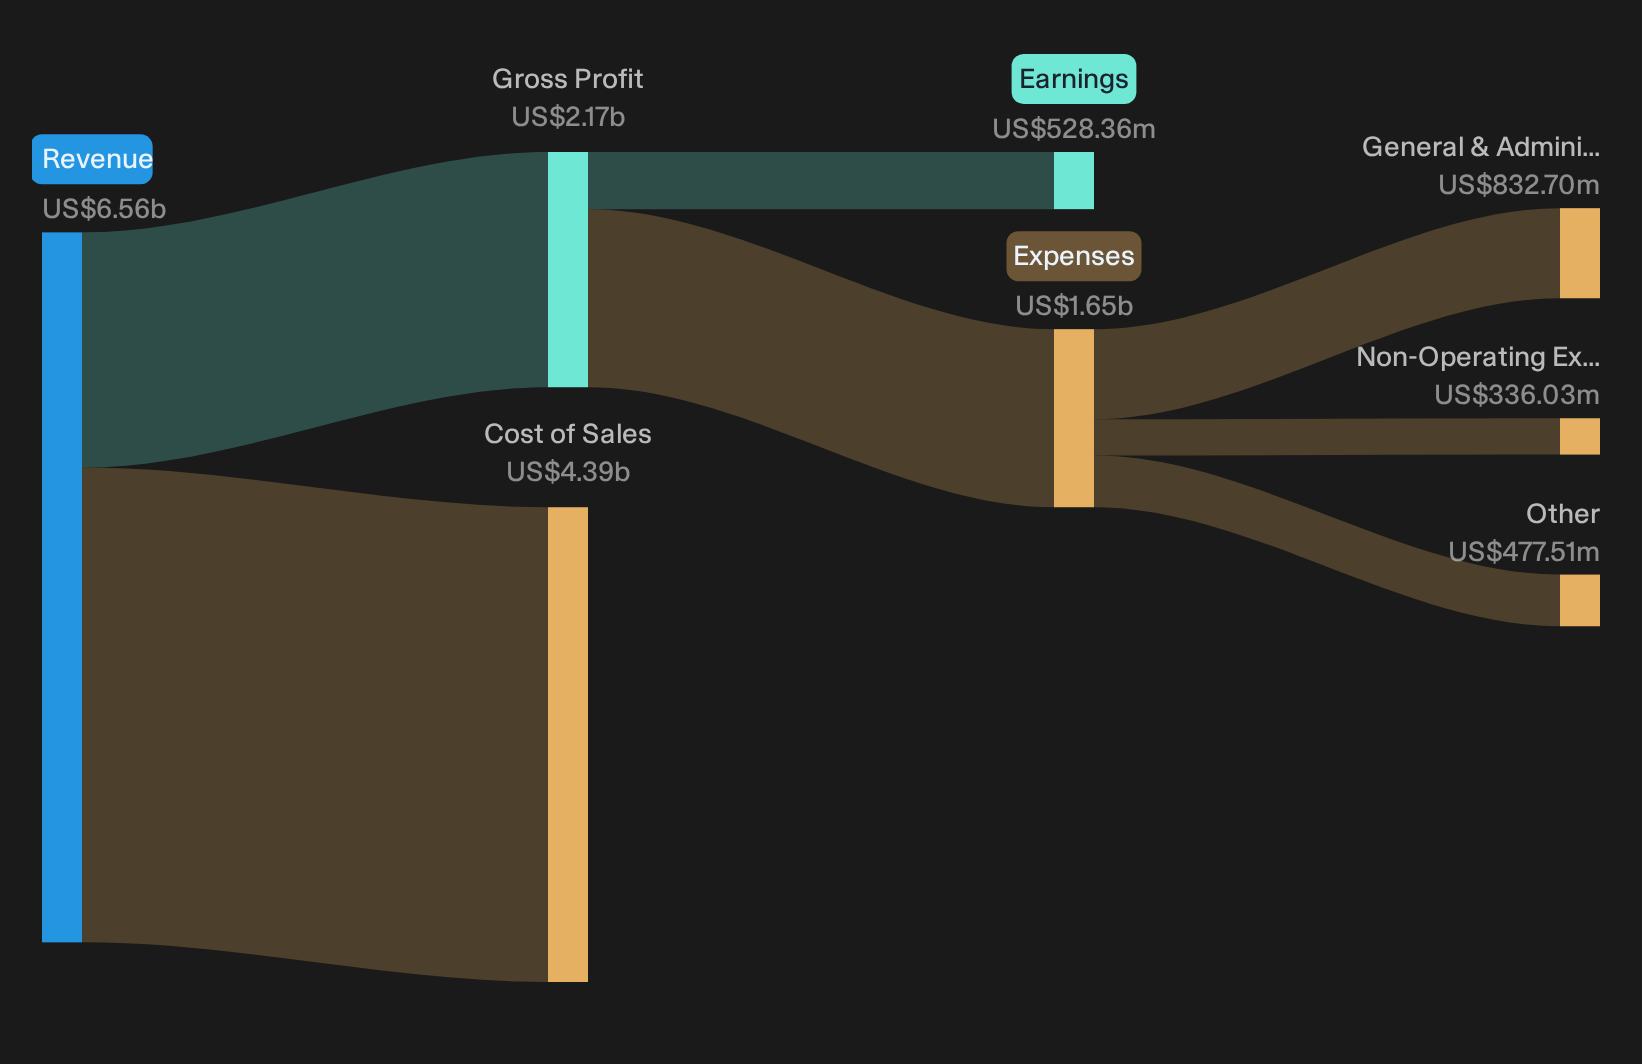
The environmental and industrial services specialist reported Q3 revenue of US$1.87b and basic earnings per share of US$3.94, both paired with the strongest adjusted EBITDA margin the business has ever delivered. The market shrugged. The results did not.
Like the combination of record margins at Clean Harbors but unsure what else in the market offers that mix of quality and financial discipline? Use our screener of stocks with sturdy balance sheets and proven fundamentals as your benchmark through the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,869.4m vs. US$1,549.3m (up about 21%).
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$208.1m vs. US$118.8m (up about 75%).
- Basic EPS (Q3 2026 vs. Q3 2025): US$3.94 vs. US$2.22 (up about 78%).
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 24.4% compared with a lower level in the prior year, described as a 42% adjusted EBITDA increase and the highest quarterly margin in company history.
Earnings show what Clean Harbors reported on paper, but cash flows show the money that actually comes through the door and supports valuation.
Based on Clean Harbors' cash flows alone, the stock could be a dramatic 33% undervalued.
Clean Harbors’ Moat Claims Versus Q3 Delivery
The bullish narrative says Clean Harbors’ hard to replicate infrastructure should turn waste regulation into a long-term compounding machine.
"The company has built a network of specialized facilities, including hazardous-waste incinerators, landfills, treatment and disposal facilities, recycling operations and service locations. Replicating that network would require enormous capital, regulatory approvals, technical expertise and many years of development."
Q3 results largely line up with that claim. Environmental Services logged its 18th straight quarter of margin expansion with segment margin at 27.4%, supported by about 87% incinerator utilization and a very large emergency response event, plus PFAS and data center work gaining traction.
Stress Testing Clean Harbors’ Resilience Pitch
Bears question whether this “resilient” model really holds up when cycles and one off boosts fade.
"One important nuance: I would not literally call the business “recession-proof.” That's too strong. Industrial activity can decline during recessions. A stronger and more credible argument is that Clean Harbors is highly resilient and defensive relative to most industrial businesses."
Recent numbers cut both ways. Q3 depended on roughly US$120m from a single emergency response and elevated spreads in Safety Kleen Sustainability Solutions, which more than tripled segment EBITDA. Those are lumpy and commodity linked, yet management still raised 2026 adjusted EBITDA and free cash flow guidance, pointing to underlying demand breadth.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt Quiet Dislocations In Plain Sight
Clean Harbors just showed how strong reported fundamentals do not always move a share price. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 40% below our estimate - expands protective film manufacturing and installation capacity so higher margin film and service channels capture more value.
- Company 2 - 46% below our estimate - converts a near record backlog of mega-projects into cash as disputed legacy jobs and litigation gradually decline.
- Company 3 - 27% below our estimate - supplies high performance cloud infrastructure that major AI workloads adopt once capacity constraints push demand to multi-cloud superclusters.
Those are three of them. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com