
Galaxy Digital (NasdaqGS:GLXY) Stock Rallies As Q3 Earnings Revive Profit Debate
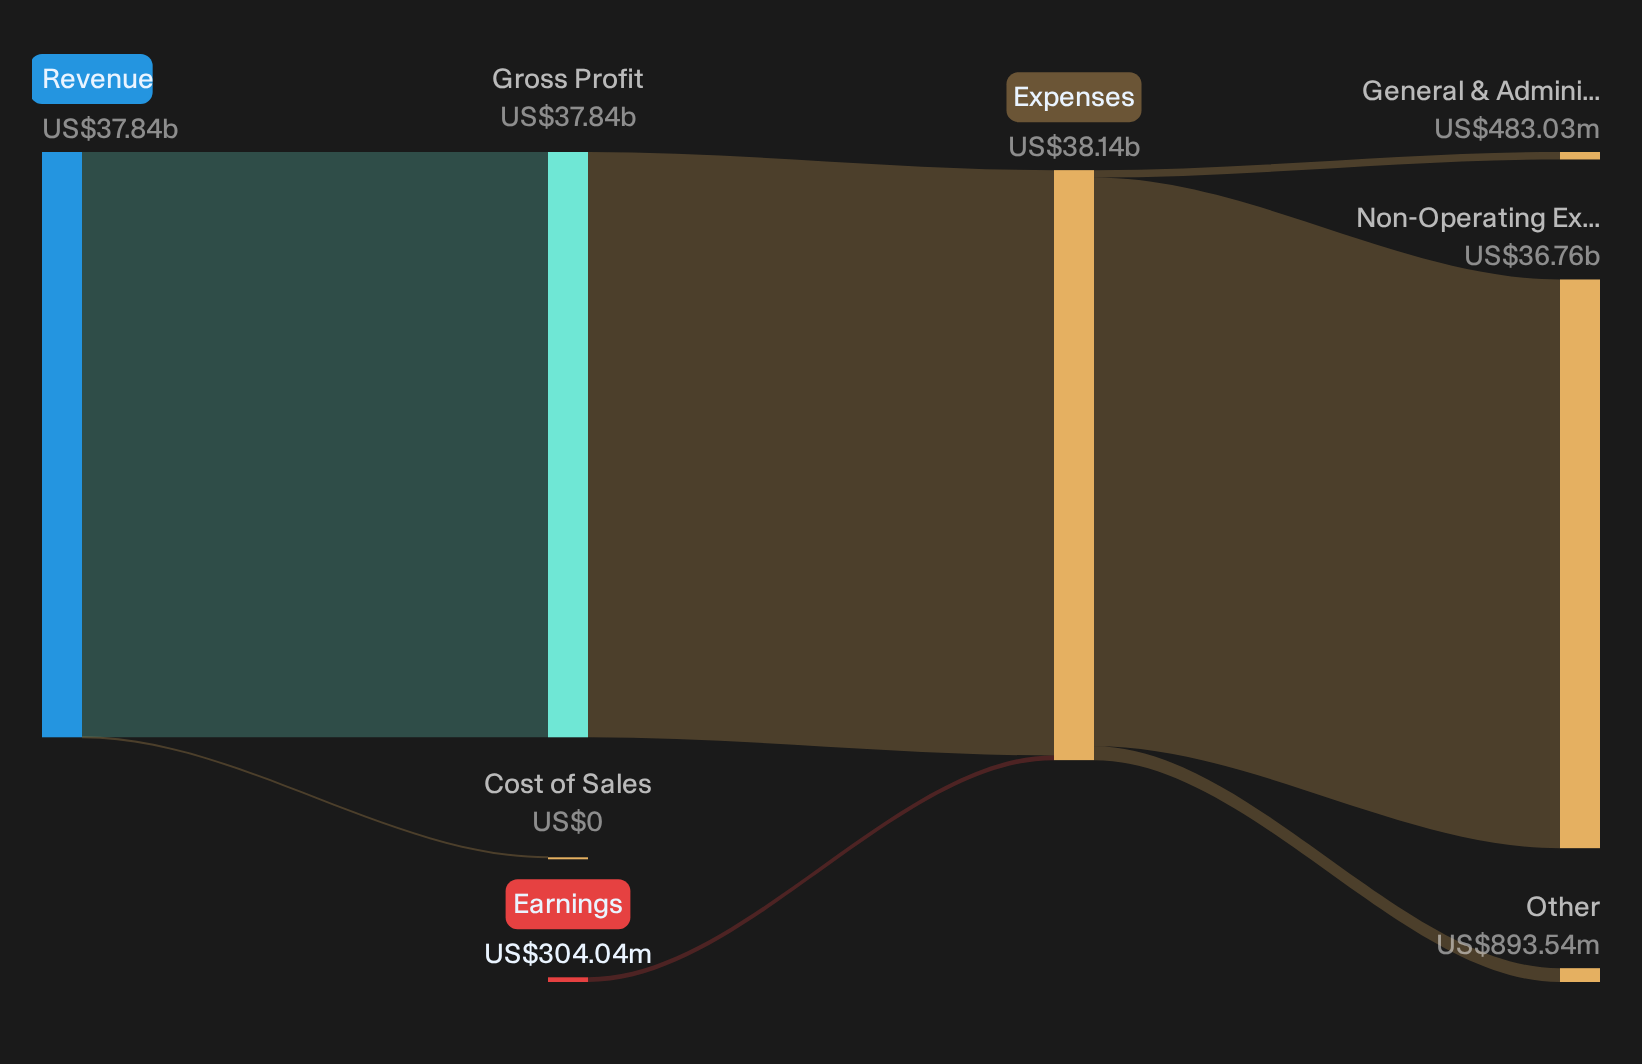
Galaxy Digital stock rose 11.1% to US$19.09 on Wednesday after investors absorbed fresh Q3 2026 numbers. That kind of move grabs attention. The headline inside the release is simpler. The firm reported about US$323 million in net income on roughly US$8.7 billion of revenue for the quarter, a sharp reset after recent losses.
Short term traders see a crypto-tied financial play suddenly back in the black. Longer term holders are looking at the same results and asking a different question: does this burst of profitability meaningfully change a business that is still loss making over the trailing twelve months and carrying material debt obligations?
Love the sharp swing back to profit at Galaxy Digital but concerned that the business is still loss making over the past year and carrying debt? Consider using the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$8,688.05 million vs. US$29,218.85 million (down about 70%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): profit of US$322.77 million vs. profit of US$208.47 million (up about 55%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.67 per share vs. US$1.19 per share (up about 40%)
- Trailing 12 Month Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025 TTM): loss of US$304.04 million vs. loss of US$48.17 million (loss widened more than 5x)
Helios could drive most of Galaxy Digital’s future revenue. Ask Charlie what Galaxy Digital’s Helios Phase II timeline really implies.
Galaxy Digital: Testing The AI Cash Flow Story
The bullish pitch says Galaxy Digital is turning AI infrastructure into dependable, rich cash generation rather than a one off trade on hype.
"The maturation of digital asset infrastructure, evidenced by large-scale, long-term data center developments and multi-phase partnerships (e.g., CoreWeave), is poised to generate significant, high-margin cash flows beginning in 2026, enhance earnings visibility, and improve the company's overall capitalization efficiency as these business lines scale."
Q3 shows early proof. Helios Phase I produced about US$80 million of quarterly leasing revenue with data center adjusted EBITDA of roughly US$69 million, which signals high incremental margins and real progress toward that cash flow goal, even though it is still just one quarter.
Galaxy Digital: Stress Testing Concentration And Funding Fears
Bears argue the same AI buildout could backfire through tenant and financing pressure rather than steady income.
"Galaxy's heavy reliance on a single tenant, CoreWeave, for its initial 800 MW data center capacity introduces significant client concentration risk. If CoreWeave faces financial stress or demand wanes, Galaxy's data center revenue and long-term cash flow growth could be impaired."
That concern shows up clearly. Helios Phase I revenue currently hinges on one counterparty, while data center liabilities of about US$5.3 billion and a US$3.5 billion notes deal underline real balance sheet exposure, even as management shifts future Helios II leases toward investment grade structures.
The price and this Narrative do not agree. → Uncover what this Narrative says Galaxy Digital is actually worth.
Hunt For Mispriced Cash Engines
Galaxy Digital just showed how quickly a single quarter can reshape the debate around a complex balance sheet. The real opportunity could sit in companies where cash generation and market expectations are still out of sync.
- Company 1 - 25% below our estimate - builds networking, connectivity and custom chips that support customers as workloads scale and performance constraints tighten.
- Company 2 - 23% below our estimate - links a cloud platform, workplace software, coding tools and AI partners so enterprises can embed experimentation into recurring productivity.
- Company 3 - 27% below our estimate - supplies high-capacity AI infrastructure and superclusters that model developers integrate as a dedicated extension to existing cloud setups.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com