
AerCap (AER) Stock Jumps After Record Q3 Earnings Lift Guidance
AerCap Holdings entered Q3 2026 earnings with its stock already on a decent run over the past month, yet the real jolt came today. After the release, the share price jumped 3.6% to US$155.48, a strong one day reaction for a global aircraft lessor often treated as a slow compounder rather than a trading story.
The headline was simple and loud. AerCap posted what management called a record quarter, with adjusted earnings per share of US$6.56 and adjusted return on equity of 22%. For an asset heavy leasing platform, that profitability readout is the single line most investors will spend the rest of this report trying to reconcile with the still modest P/E tag.
Like the mix of record EPS and high return on equity at AerCap Holdings but still wrestling with what a modest P/E really signals for quality and resilience? Line this result up against other resilient balance sheet plays using our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$2,415.3m vs. US$2,308.6m (up about 4.6%)
- Net Income (Excl. Extra Items) (Q3 2026 vs Q3 2025): US$948.8m vs. US$1,215.7m (down about 22.0%)
- Basic EPS (Q3 2026 vs Q3 2025): US$6.22 vs. US$7.09 (down about 12.2%)
- Trailing 12-Month Net Profit Margin (Q3 2026 vs prior year): 34.5% vs. 45.4% (compressed by 10.9 percentage points)
AerCap says its order book is already placed through 2027. Ask Charlie what AerCap’s fully placed order book really locks in.
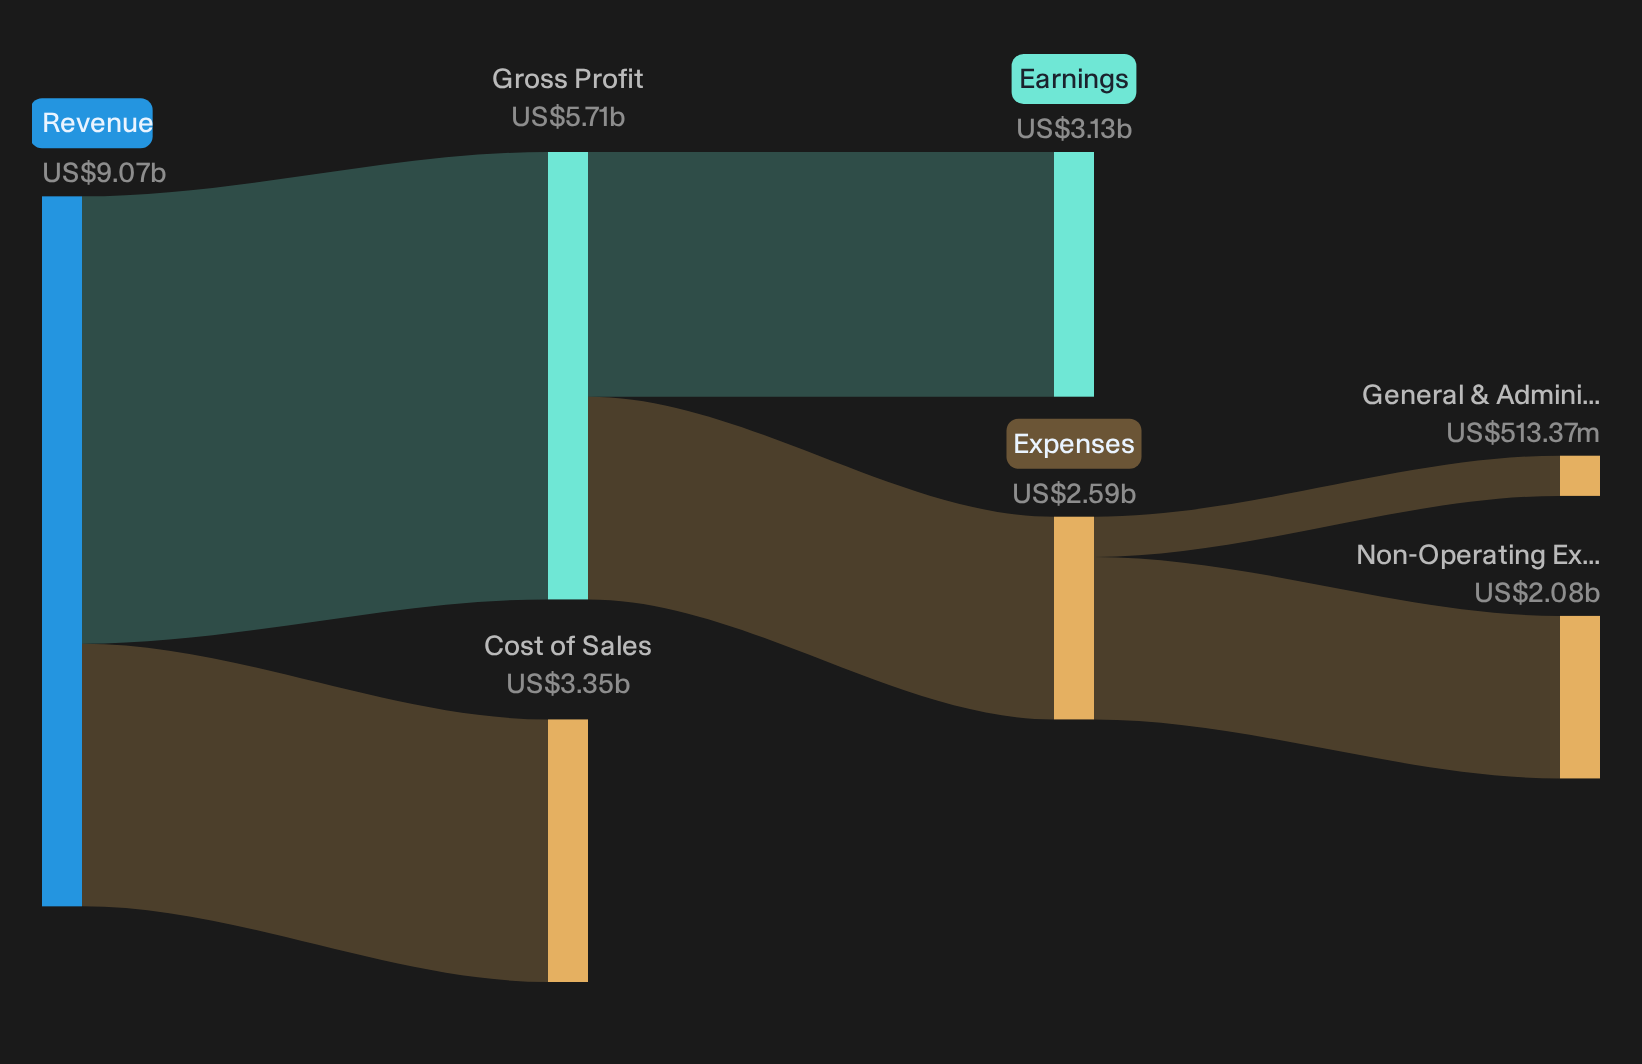
AerCap asset sales and ROE targets under scrutiny
The bullish story on AerCap rests heavily on converting platform breadth and trading activity into durable profitability.
"The main factor that has to go right is that AerCap Holdings continues to convert its scale, diversified engine and helicopter platforms, and record asset sale activity into sustained high returns on equity while managing airline and fuel price risks."
Record Q3 adjusted EPS of US$6.56, a 22% adjusted ROE and US$353m of gains on sale at roughly 45% margins show that, for now, cash realization from disposals is matching that ambition despite compression in trailing net profit margin.
AerCap execution risk and downside scenario tested
The key worry has been that strong execution is already embedded, so even small stumbles could hurt holders.
"The current valuation implies that AerCap Holdings shares already reflect strong execution on aircraft supply constraints, secondary market gains and capital returns, which leaves limited room for disappointment if conditions or earnings weaken."
Q3 brought record adjusted EPS, a guidance lift to about US$20.70 and asset sale gains that management expects to exceed the prior US$4b to US$5b range for 2026. This runs counter to that downside scenario for now, although year on year EPS and margin compression show how quickly sentiment could shift.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Cash Engines
AerCap Holdings just showed how one quarter can reset expectations for a capital intensive business. The real opportunity sits in finding stocks that could be undervalued before the crowd pays attention.
- Company 1 - 25% below our estimate - builds connectivity and custom silicon for demanding computing customers that prioritize performance and reliability.
- Company 2 - 43% below our estimate - connects digital merchants to diverse local pay-in and pay-out options as transaction volumes shift channels.
- Company 3 - 23% below our estimate - embeds AI features into workplace software and cloud tools that enterprises already standardize on for operations.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com