
Northwest Pipe (NASDAQ:NWPX) delivers strong Q3 2026 numbers
Water management company Northwest Pipe (NASDAQ:NWPX) announced better-than-expected revenue in Q3 2026, with revenue up 18.7% year on year to $179.4 million. Its GAAP profit of $1.86 per share was 12.9% above analysts’ consensus estimates.
For more on Northwest Pipe, read our free full research report.
Northwest Pipe (NWPX) Q3 2026 highlights:
- Revenue $179.4 million vs S&P analysts’ consensus estimates of $167.8 million (18.7% year-on-year growth, 6.9% beat)
- EPS (GAAP) $1.86 vs analysts’ consensus estimates of $1.65 (12.9% beat)
- Operating margin 13.6%, in line with the same quarter last year
- Free cash flow margin 11.3%, up from 8.7% in the same quarter last year
- Market capitalization $962.2 million
"The third quarter of 2026 was another outstanding quarter for NWPX Infrastructure, highlighted by record financial performance across several key metrics," said Scott Montross, President and Chief Executive Officer of NWPX Infrastructure. "We generated record quarterly revenue of $179.4 million and record gross profit, representing a consolidated gross margin of 21.3%, along with earnings per diluted share of $1.86. These results reflect the strength and resilience of our businesses, disciplined execution across our operations, and our continued ability to capitalize on favorable market conditions. WTS led our performance, delivering record revenue and record gross profit with a strong gross margin of 20.7%. WTS backlog including confirmed orders reached a record $435 million, even after recognizing $31.0 million in revenue associated with our NDA project during the quarter, providing excellent visibility into future production activity. Precast also delivered solid results, with revenue and gross profit exceeding the prior year, and an approximate 160-basis point improvement in gross margin to 22.9%. We are particularly encouraged by the continued growth of our data center business, which continues to represent an attractive opportunity within our Precast segment."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Northwest Pipe’s revenue grew at a strong 15% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
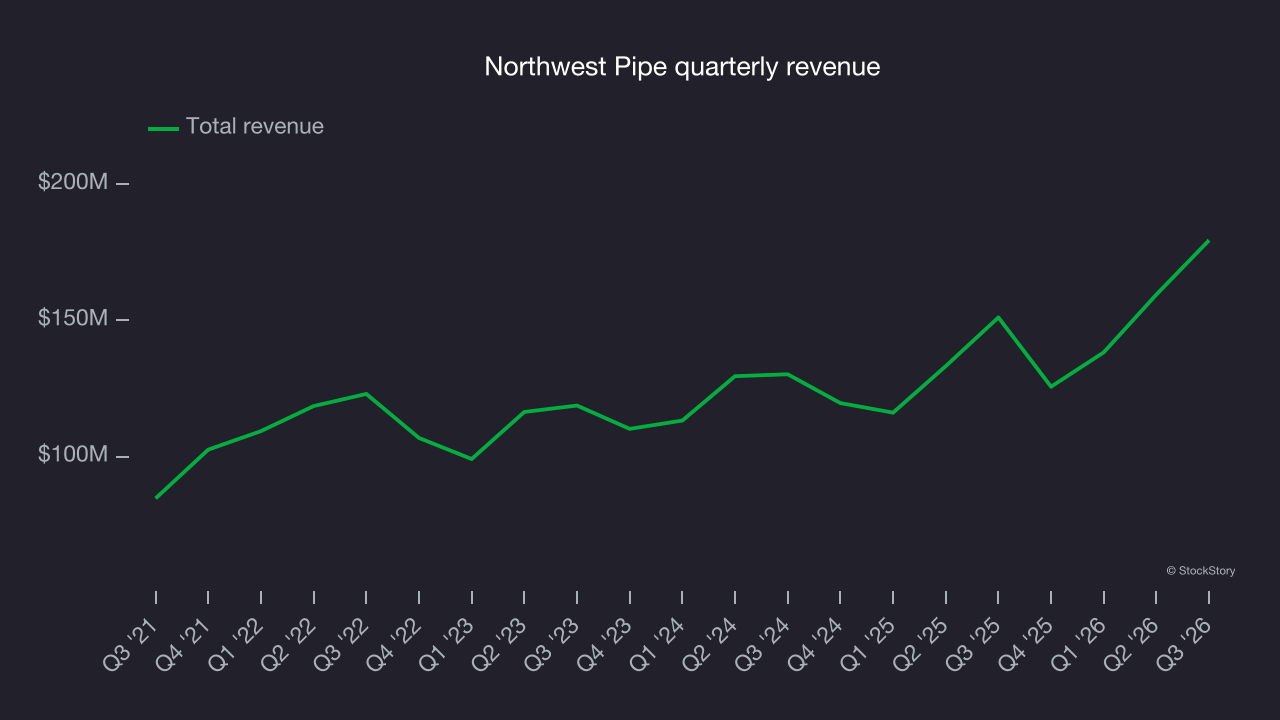
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Northwest Pipe’s annualized revenue growth of 11.7% over the last two years is below its five-year trend, but the results still suggest healthy demand. 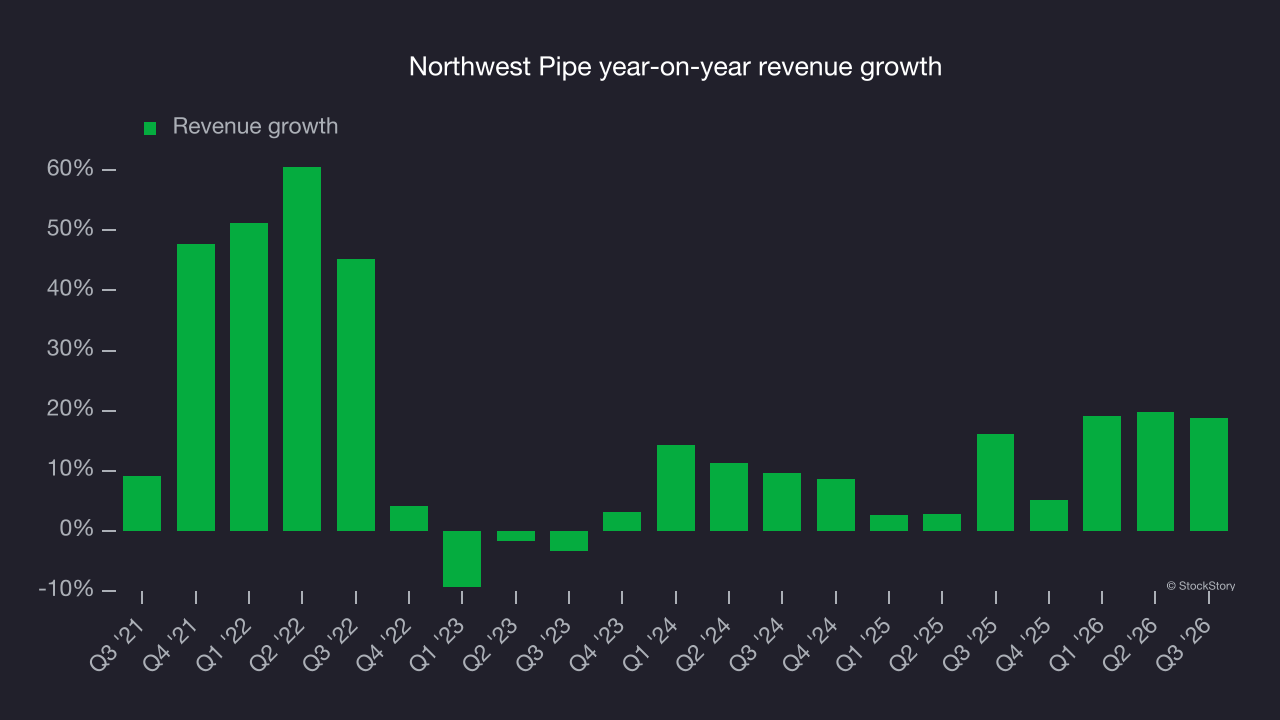
This quarter, Northwest Pipe reported year-on-year revenue growth of 18.7%, and its $179.4 million of revenue exceeded Wall Street’s consensus estimates by 6.9%.
Looking ahead, sell-side analysts expect revenue to decline by 3% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. Still, the company is performing well on other measures of financial health.
Operating margin
Northwest Pipe has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 9.6%, higher than the broader industrials sector.
Analyzing the trend in its profitability, Northwest Pipe’s operating margin rose by 2.8 percentage points over the last five years, as its revenue growth gave it operating leverage.
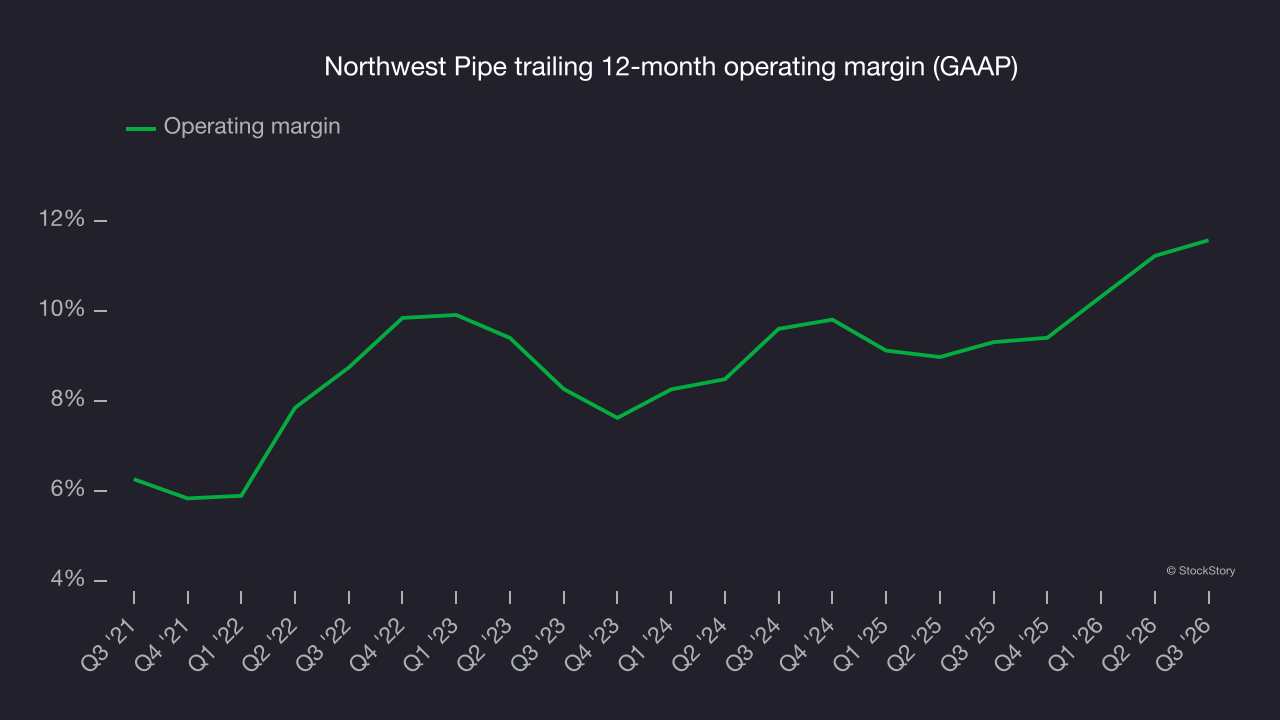
This quarter, Northwest Pipe generated an operating margin of 13.6%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Northwest Pipe’s EPS grew at a 30.2% compounded annual growth rate over the last five years, higher than its 15% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
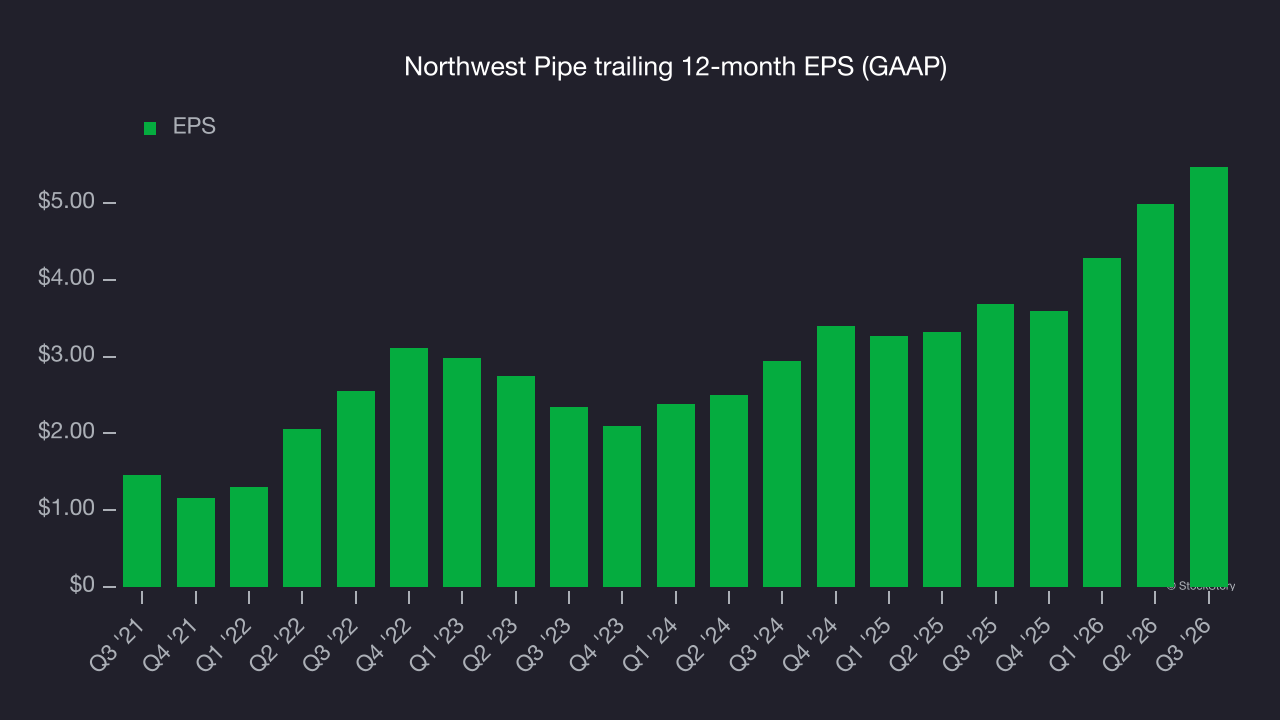
Diving into the nuances of Northwest Pipe’s earnings can give us a better understanding of its performance. As we mentioned earlier, Northwest Pipe’s operating margin was flat this quarter but expanded by 2.8 percentage points over the last five years. On top of that, its share count shrank by 1.2%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 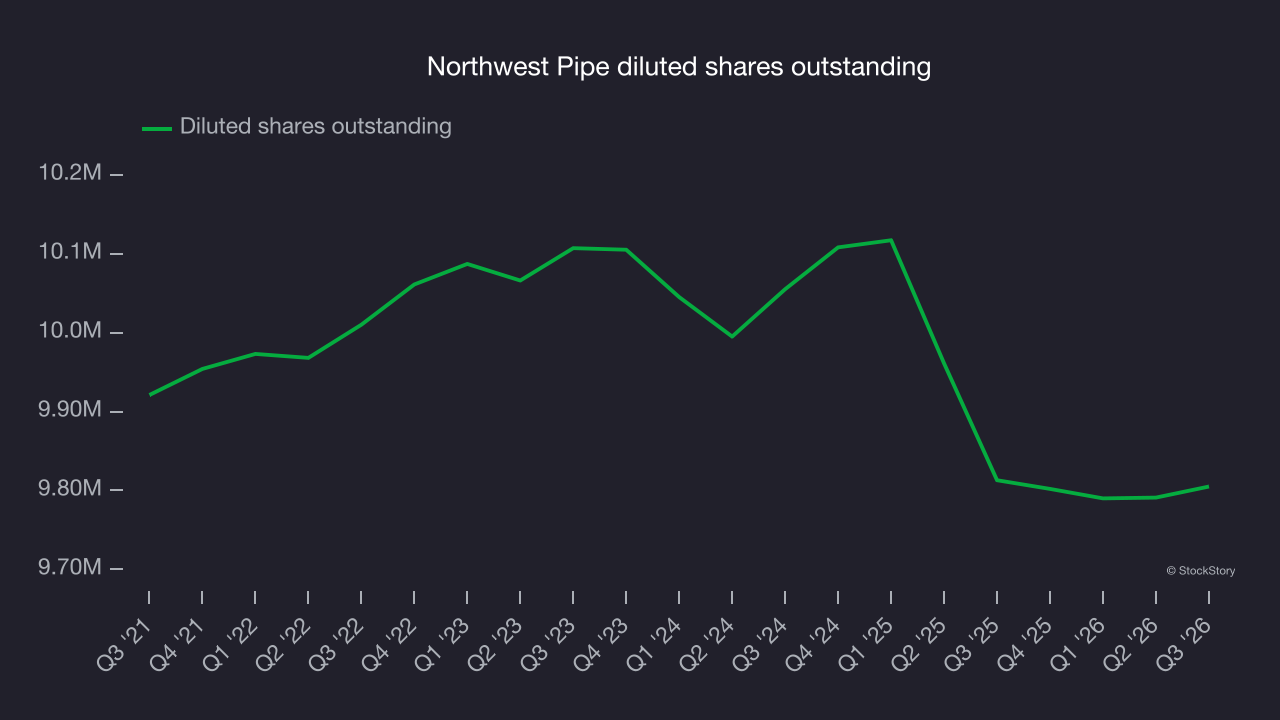
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Northwest Pipe, its two-year annual EPS growth of 36.4% was higher than its five-year trend. That acceleration is a positive sign, especially given the already high base.
In Q3, Northwest Pipe reported EPS of $1.86, up from $1.38 in the same quarter last year. EPS easily cleared analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Northwest Pipe’s full-year EPS to shrink by 10.9% from $5.47 to $4.87, according to S&P.
Key takeaways from Northwest Pipe’s Q3 results
Northwest Pipe delivered a solid quarter, with revenue beating analysts’ consensus estimates by a wide margin and EPS also topping Wall Street’s estimates. Those were the key positives in the report. Shares remained flat at $99.88 immediately after the results.
Northwest Pipe’s latest quarter is only one part of assessing its longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. For more on these factors, read our full research report here (it’s free).