
JLL (JLL) Stock Price Extends Gains On Record Q3 Earnings
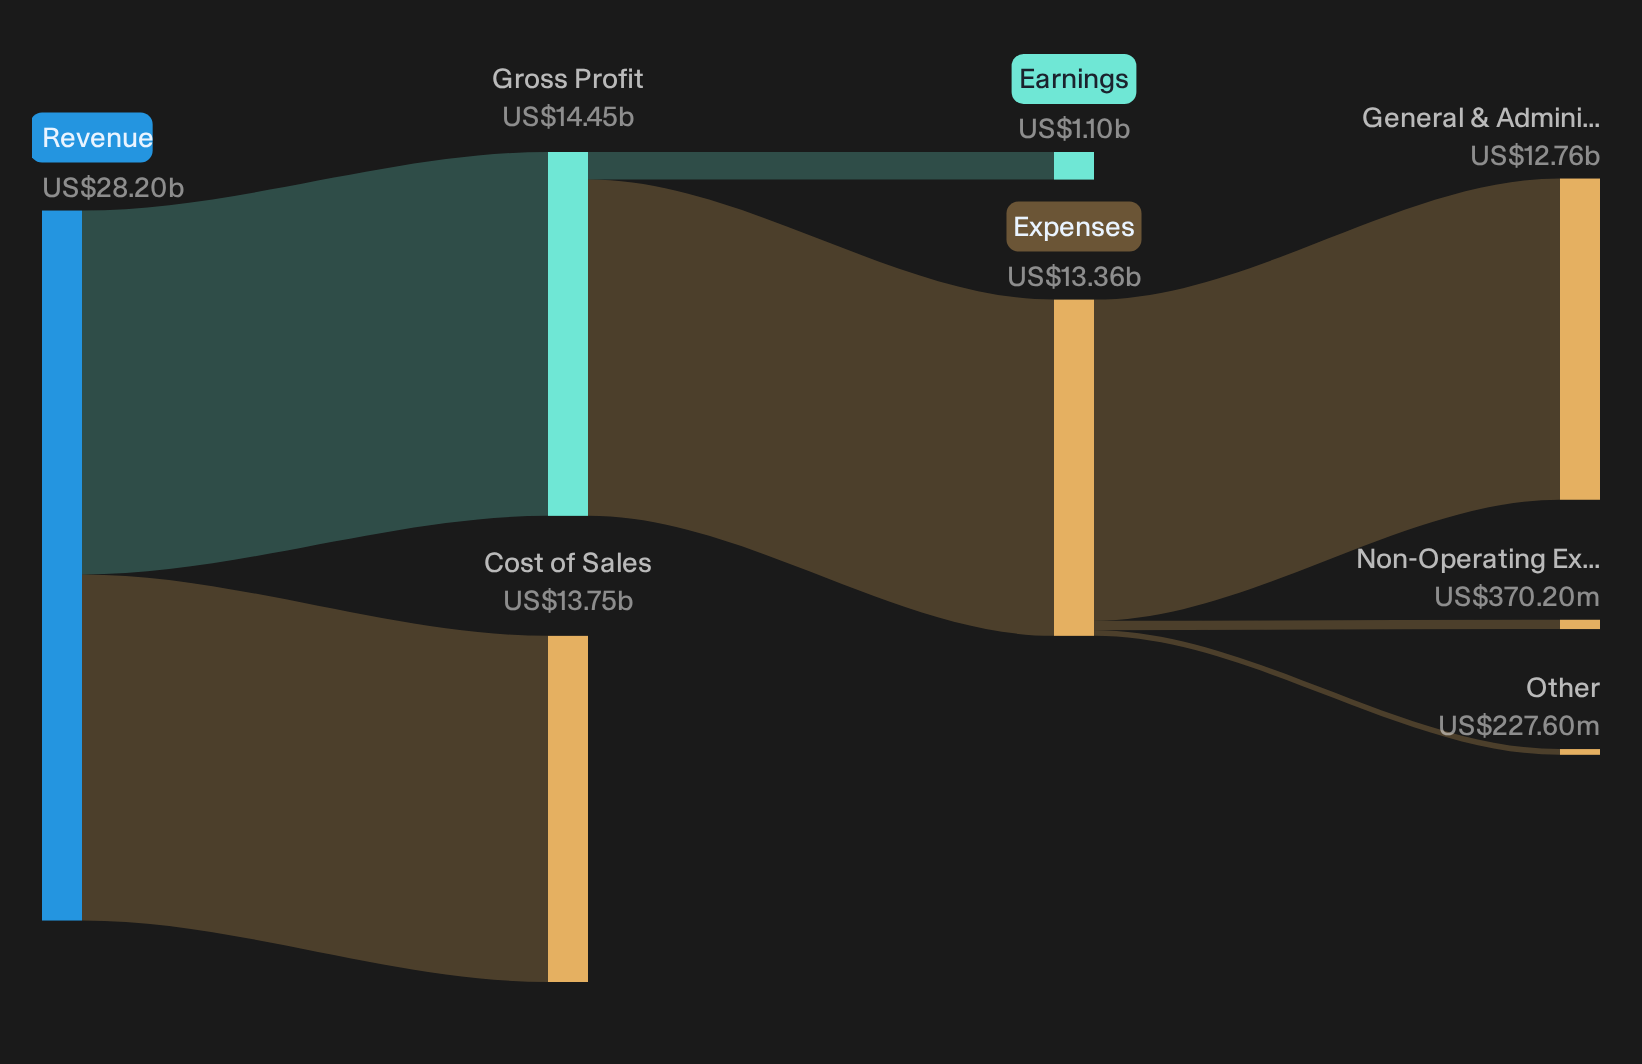
Jones Lang LaSalle just dropped its Q3 2026 scorecard and the trading screen lit up. The stock jumped 11.1% to US$333.34 by the close, a sharp move for a global property services heavyweight. That surge landed on the back of record quarterly revenue of US$7.28b and basic earnings per share of US$6.97. Together, these figures mark a notable profit swing in a sector where small margin shifts can matter more than headline sales.
For now, emotion is chasing the tape higher. The real question is whether this one-day repricing matches the profit story that unfolded underneath.
Impressed by Jones Lang LaSalle’s Q3 revenue and earnings punch but concerned that a single quarter jump can skew expectations? Compare this move with list of solid balance sheet and fundamentals stocks (24 results) for additional context.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$7,281.2m vs. US$6,510.4m (up 11.8%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$319.8m vs. US$222.8m (up 43.6%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$6.97 vs. US$4.71 (up 48.0%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 3.9% vs. 2.5% (higher margin on recent earnings)
Ask Charlie what JLL’s $500m buyback signals about management’s confidence.
JLL’s AI Ambitions Meet Early Margin Progress
The bullish story on Jones Lang LaSalle hinges on its tech platform changing how work gets done, not just adding more brokers and staff.
"The main factor that would need to go right is sustained execution on AI and data driven tools that keep revenue per producer and share gains in capital markets and leasing ahead of underlying transaction volumes, while preserving disciplined capital allocation."
Q3 shows parts of that thesis starting to show up in the numbers. Revenue rose faster than adjusted EBITDA, margins widened and management now pegs Accelerate 2030 platform work at roughly 20 bps of yearly margin help. Capital Markets and Leasing both posted double digit growth without any mention of heavy hiring, while a fresh US$500m accelerated buyback reinforces disciplined use of cash rather than large deals at any price.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
JLL Bears Question Whether AI Fees Can Hold
One key worry around Jones Lang LaSalle is not whether AI tools work, but who keeps the savings.
"While high daily adoption of internal AI tools and more than 100 AI agents in Real Estate Management Services workflows are already raising producer productivity, if AI driven efficiencies are increasingly shared back to clients through glide path savings and lower effective fees, the uplift to net margins and earnings could prove smaller than current expectations."
Q3 showed margin expansion and raised EPS guidance. This signals JLL is currently retaining a meaningful share of efficiency gains. Yet property management contract resets in APAC and glide path savings language suggest fee pressure is real, and the long run split of AI value with clients is still unresolved.
Hunt For Mispriced Earnings Power
Jones Lang LaSalle recently reported earnings that shifted sentiment as the quarter surprised the market. The real opportunity could sit in stocks where business momentum and market pricing have not yet aligned.
- Company 1 - 31% below our estimate - expands from classic deal advisory into capital markets and private capital mandates with richer fee potential.
- Company 2 - 27% below our estimate - supplies the AI superclusters a flagship model provider relies on to secure extra capacity beyond a primary cloud partner.
- Company 3 - 40% below our estimate - scales a new manufacturing build out that supports higher margin protective films and bundled installation services for repeat automotive programs.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com