
Renesas Stock In Focus After Ultra Low Power MCU Launch
- Renesas Electronics recently introduced the RL78/G21 microcontroller for smart appliances and expanded the RL78/G23 range with higher touch-channel counts, added security features, and tools for scalable human machine interfaces across household and industrial devices.
- The focus on ultra low power operation, integrated security and reduced bill of materials directly targets appliance makers seeking energy savings, lower system costs and simplified design migration.
- We will now look at how Renesas Electronics' ultra low power RL78/G21 launch may influence the existing investment narrative.
Scan beyond Renesas Electronics and see how other microcontroller and industrial computing players stack up on efficiency, security and balance sheet quality using our curated 22 resilient stocks with low risk scores today.
Renesas Electronics Investment Narrative Recap
To own Renesas Electronics, you need to believe that its push into higher value AI infrastructure, automotive and industrial chips can support steady earnings while heavy R&D and platform spend stays under control. The RL78/G21 and RL78/G23 launches mainly affect the industrial and appliance side, so they do not fundamentally shift the near term AI data center catalyst.
The bigger swing factor still sits with execution in AI power devices and digital power modules, plus the outcome of the GaN patent dispute, which could affect returns from that effort. Recent sector weakness on AI spending worries highlights how sensitive the stock remains to sentiment around those infrastructure ambitions.
The RL78/G21 ultra low power MCU announcement is the clearest tie to this week’s news. It broadens Renesas Electronics exposure to mainstream appliances, where energy efficiency, integrated security and lower bill of materials can be important selling points for OEM customers and may help support the Industrial/Infrastructure/IoT segment.
As a catalyst, this product launch is incremental rather than transformational. It reinforces the idea that Renesas Electronics is trying to balance AI and data center bets with more stable embedded MCU demand. Execution risk stays centered on maintaining margins while R&D, software and platform investments remain elevated relative to revenue.
Renesas Electronics' current analyst narrative points to revenues of ¥2,030.5b and earnings of ¥433.4b by 2029, built on assumed yearly top line expansion of 11.0% and an earnings increase of about ¥92.5b from ¥340.9b today.
Uncover why Renesas Electronics' fair value indicates a 63% potential upside to its current price, which could narrow quickly.
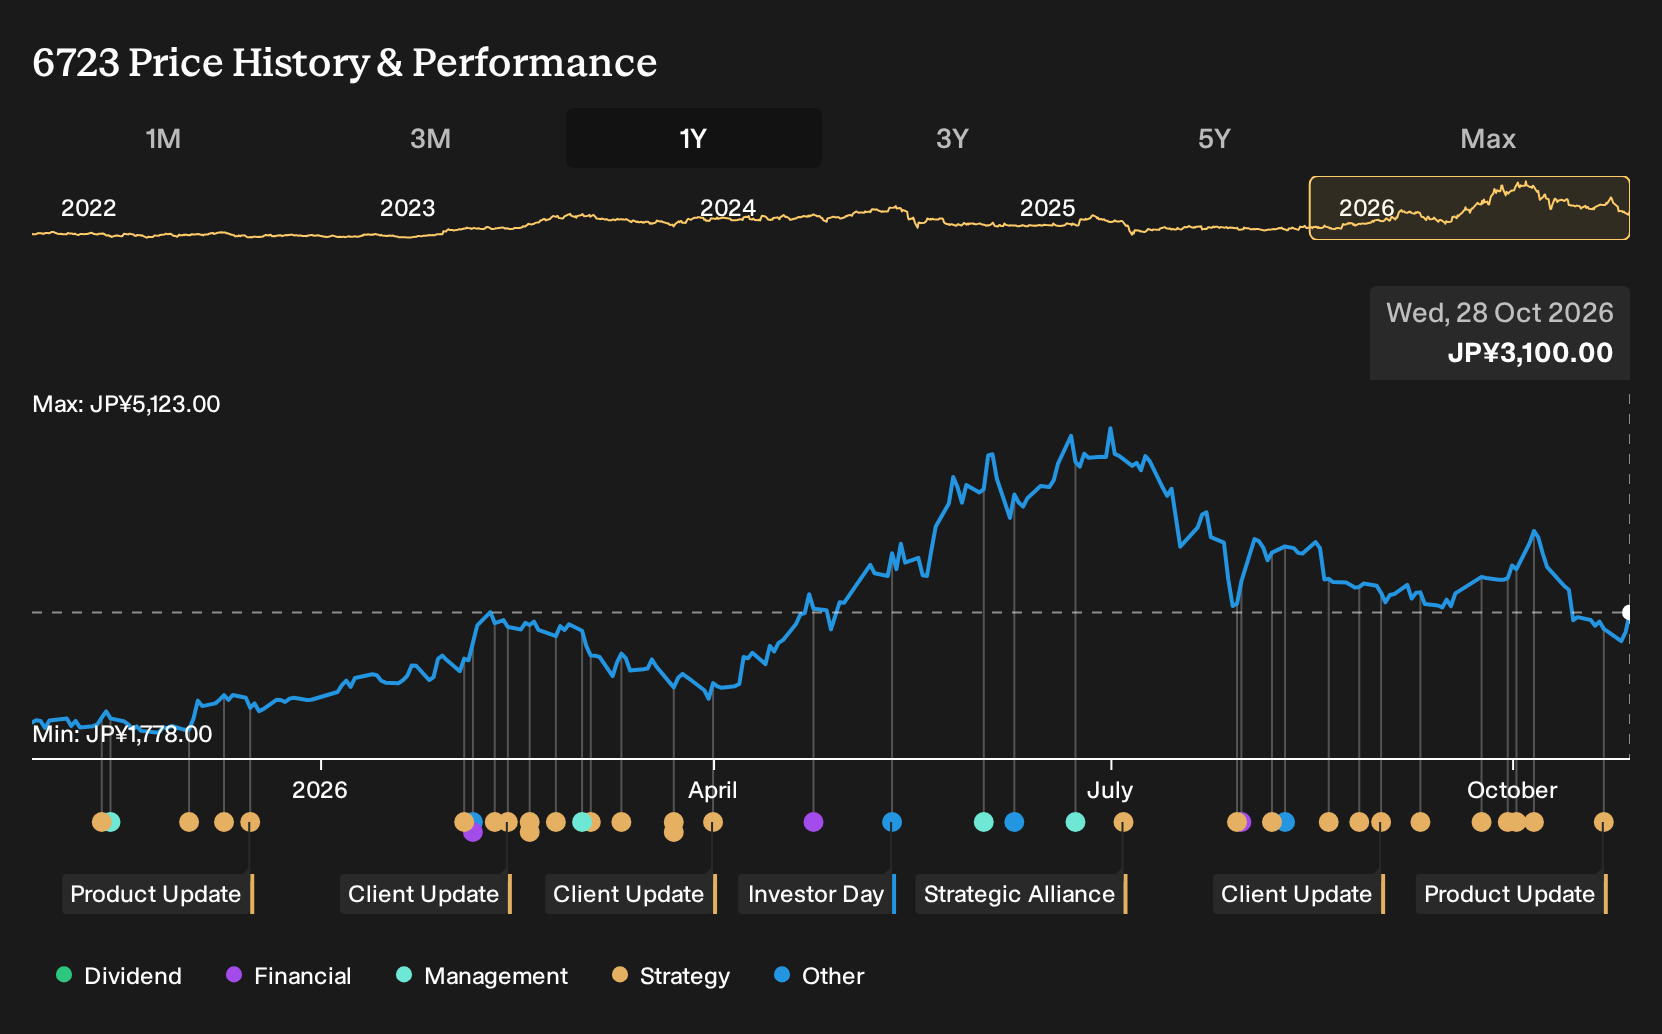
Exploring Other Perspectives
One alternate view on Renesas Electronics leans heavily on margin pressure risk. The lowest analysts were assuming revenue of ¥1,681.1b and earnings of ¥323.7b by 2029, meaning lower profitability than consensus. Those forecasts came before this RL78/G21 launch, so opinions may shift. Use them as a reference point, not a script.
Explore 2 other Renesas Electronics fair value estimates, including one that suggests as much as 14% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Renesas Electronics research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Renesas Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renesas Electronics' overall financial health at a glance.
Looking for more investment ideas beyond Renesas Electronics?
If you like the Renesas Electronics story but want a broader watchlist, the Simply Wall St Screener can help you quickly surface other stocks that match the type of risk and quality profile you prefer.
- For investors who care most about capital stability and robust financial footing, start with a list of solid balance sheet and fundamentals (23 results) that already clear strict balance sheet checks.
- If you want potential mispriced opportunities with strong business quality, scan through a curated set of 16 high quality undervalued stocks that combine fundamentals with more attractive pricing.
- For steadier income and cash returns, focus on companies in the 29 dividend fortresses that aim to pair higher yields with resilient operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com