
Why Geely Automobile Fell Even As Profit Rose
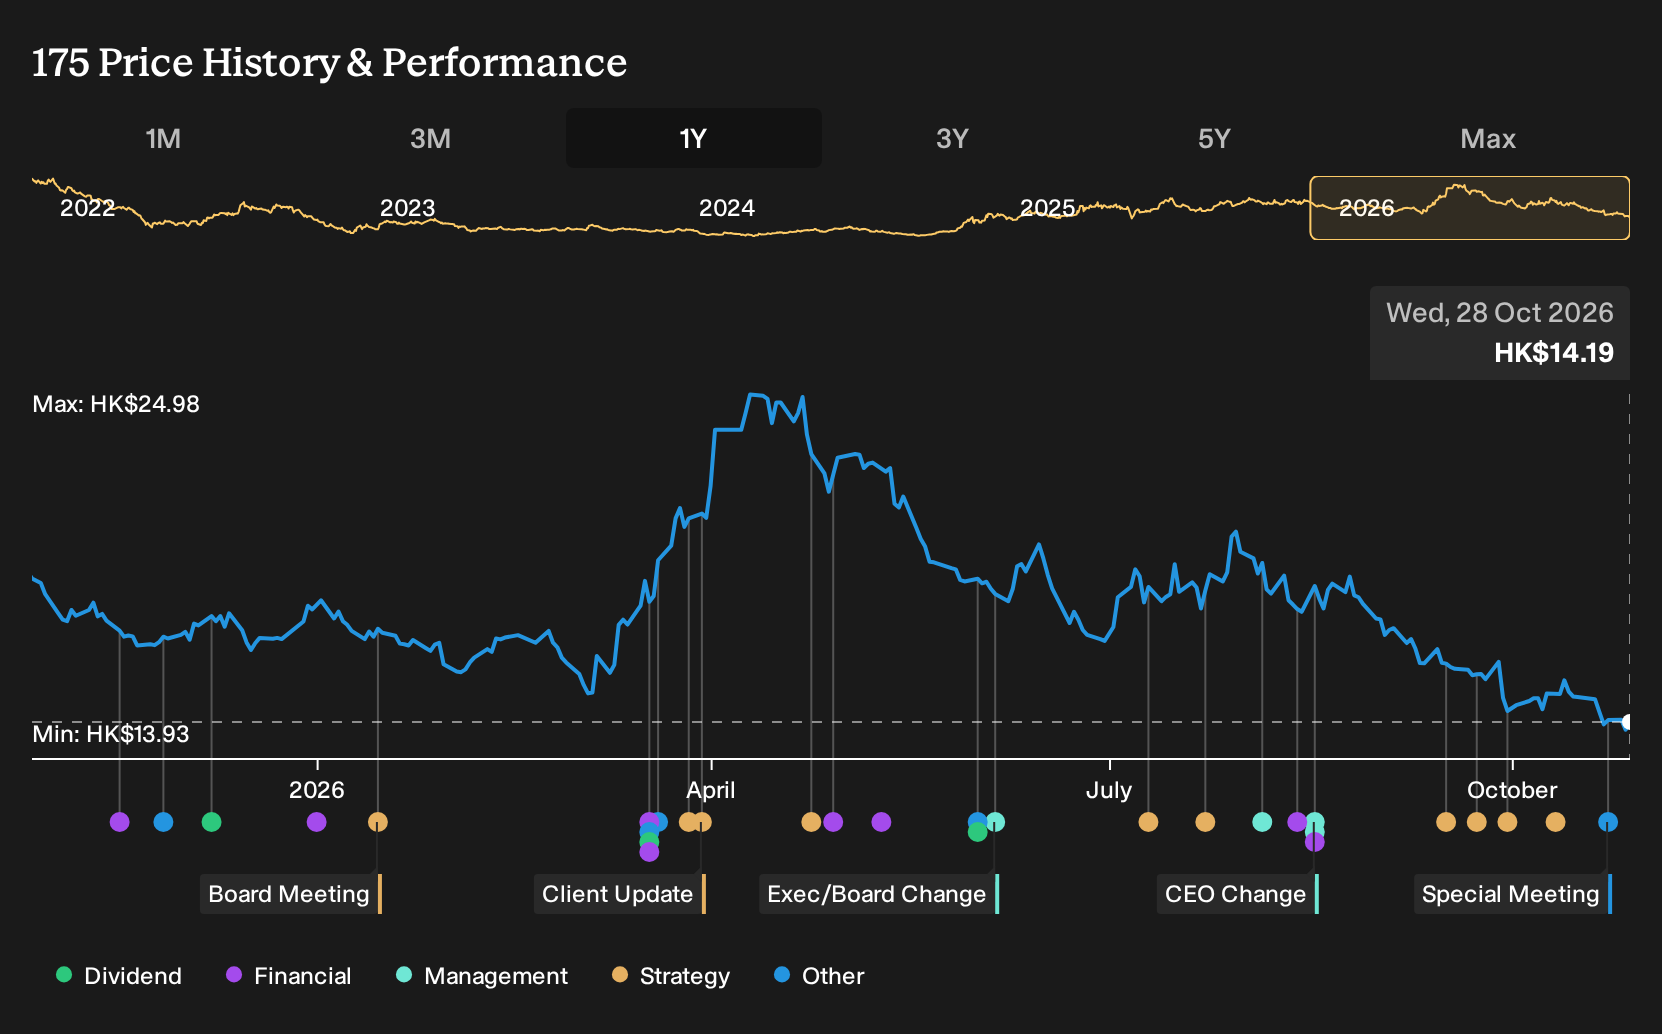
Geely Automobile has spent the past year juggling upbeat headlines about NEV launches, global expansion plans and new tech partnerships with some tough external hits to the wider auto sector. For Geely Automobile shareholders, the loss over the past year was 23.0%, including dividends. If you had bought on 28 October 2025, trusting forecasts for double digit revenue growth, margin compression and higher 2028 P/E multiples, what exactly did that original thesis fail to account for?
If the move has made Geely Automobile harder to judge, start where the gap is still open and scan 198 high quality undervalued stocks.
The Two Stories Geely Automobile Investors Had To Weigh
The shares cost HK$18.92 at the start of the period, and anyone looking at Geely Automobile then was really choosing between two very different stories that both sounded plausible.
The bullish view argued that launching 10 new NEV models in 2025 and pushing harder overseas could support higher sales, with a Fair Value of HK$25.1, the price implied if those assumptions played out. That case leaned on revenue growing 19.5% a year and a future 2028 P/E of 15.3x.
The bearish camp focused on rising tariffs and supply chain issues that could squeeze EV profitability, with a Fair Value of HK$17.03 built from more cautious inputs. In that version, revenue rose 14.2% a year but profit margins shrank from 8.1% to 4.2% by 2028.
What The Results Changed For The Geely Automobile Thesis
Geely Automobile reported Q2 2026 revenue of CNY 89,824.313m and net income of CNY 4,924.665m, with net margin at 5.5% versus 4.5% a year earlier. That shift in profitability supported the view that electrification and exports could help earnings. News on tariffs and US restrictions for Polestar and Volvo kept the cautious case alive, so the evidence cut both ways.
The key lesson is clear. When a thesis hinges on global expansion and EV mix, track export volumes, regional policy news and net margin together, rather than treating revenue growth alone as confirmation.
What You Would Be Paying For In Geely Automobile Today
Geely Automobile now trades at HK$14.19, with the selected Narrative arguing that its Fair Value sits above that level based on an earnings mix story rather than simple volume hopes.
The focus lands on export-heavy, capital light growth and hybrids. A buyer today would be assuming those higher margin overseas sales scale without eroding profitability.
"Export margins that the CFO describes as roughly 10 percentage points higher than domestic sales, combined with guidance that group gross margin in Q3 2026 should at least match the 18.4% level from Q2, are presented as creating room for Geely Automobile Holdings to shift the earnings mix toward higher margin overseas volumes and potentially change group net margins and earnings quality as exports scale."
The price and this Narrative do not agree. → Uncover what this Narrative says Geely Automobile is actually worth
Looking Beyond Geely Automobile
Geely Automobile highlights electrification, exports and new tech features in mainstream models.
Once that is on your radar, a different kind of bet appears nearby. Instead of chasing volume, this other business leans on software and digital capability inside its vehicles.
Its plan connects in house operating systems, driver assistance and cost discipline to how future returns might be earned.
The goal is to keep profitability intact even when tariffs, FX swings or weaker regions hurt margins.
If Geely is about where vehicles are sold, this peer asks how much of each car’s future value comes from software and efficiency gains.
That argument has a Narrative and a number behind it. → See the company one Narrative values 34% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com