
Photocure (OB:PHO) Q3 Results Put Cash Flow Ahead Of Earnings
Photocure came into the Q3 2026 print with the share price at NOK47.5 after a weak three months, down about 11%. The stock carries a premium P/E of 26.3x and a reputation as a high growth bladder cancer specialist, yet the fresh quarter shows a loss of NOK 26.2m on NOK 140.9m in revenue and adjusted EBITDA of roughly NOK 18.5m. Traders saw a familiar small cap biotech story. The gap here is that cash generation, not the earnings headline, now does the real talking.
Love Photocure’s specialist bladder cancer focus but concerned that earnings and cash generation are pulling in different directions? Benchmark it against a screener of stronger balance sheet plays using the list of solid balance sheet and fundamentals stocks (207 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): NOK 140.9m vs. NOK 135.0m (up about 4%)
- Net Loss (Q3 2026 vs. Q3 2025): NOK 26.2m loss vs. NOK 4.0m profit (shift from profit to loss)
- Basic EPS (Q3 2026 vs. Q3 2025): NOK 0.97 loss per share vs. NOK 0.15 earnings per share (moved from profit to loss)
- Adjusted EBITDA Margin (Q3 2026): NOK 18.5m on NOK 140.9m revenue, resulting in an adjusted EBITDA margin of around 13% for the quarter
Prefer clear charts over a wall of Photocure numbers and footnotes? See the full visual breakdown of the business, including how the balance sheet looks alongside key valuation and earnings metrics, in the company report for Photocure.
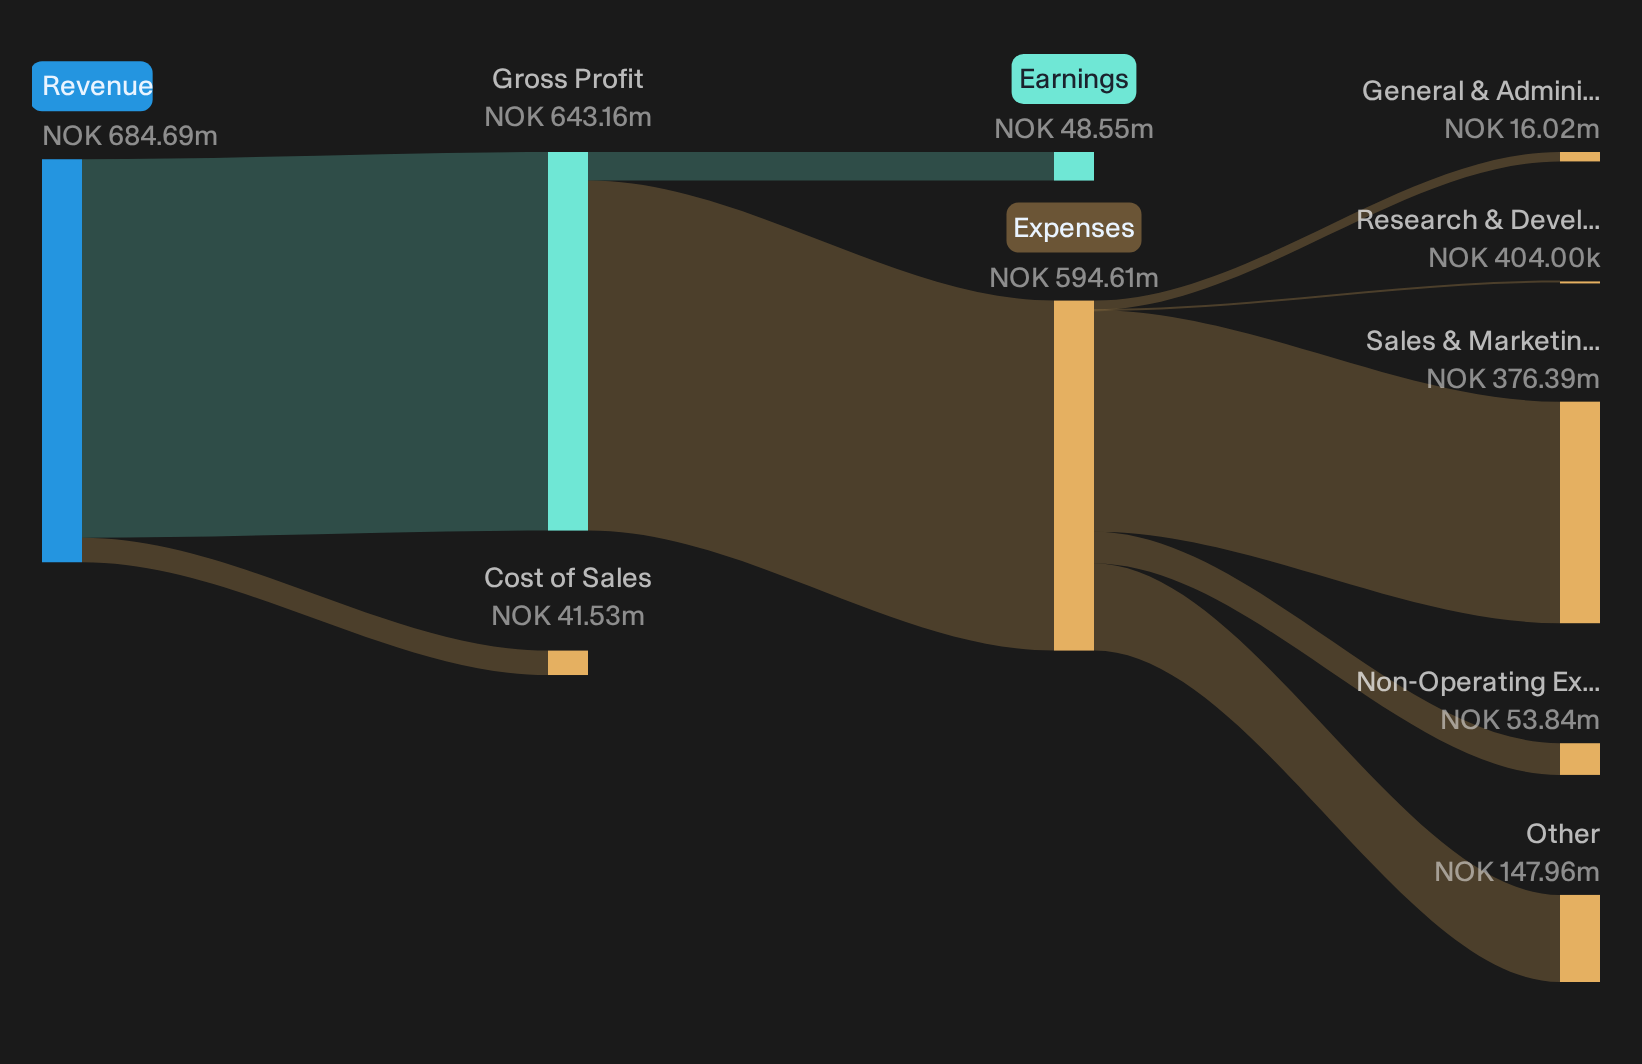
Photocure bull case: blue light engine under review
Supporters argue that expanding Photocure’s blue light ecosystem will steadily convert guideline support into higher recurring usage and profitability.
"The main requirement is execution on expanding clinical use and reimbursement so that Vesica’s AssureMDx and the wider BLC platform convert the identified procedure volumes and guideline support into sustained product revenue and EBITDA margin development."
Q3 shows some of that engine working. Hexvix/Cysview product sales reached NOK 134.2m, with North America and Europe both reporting volume gains and active accounts up about 20%. Adjusted EBITDA of about NOK 18.5m and raised 2026 growth guidance to a range of 10% to 12% point to early operating leverage, although net income moved to a loss.
Photocure bear case: execution and cash pressure tested
Critics focus on whether heavy spending around Vesica and AssureMDx will strain cash if earnings traction lags.
"Costly investments tied to the Vesica Health acquisition, the rollout of AssureMDx, and broader market access work already resulted in a total cash outflow of NOK 30.3 million in Q2 2026. If product revenue and adjusted EBITDA margins do not rise enough to offset these outlays, then Photocure’s net margins and cash position could come under pressure."
The latest quarter pushes back on the liquidity worry but not on profitability. Operations generated NOK 19.4m of cash, leaving NOK 162.4m on hand and no interest bearing debt. Yet the business still reported a NOK 26.2m loss and only modest adjusted EBITDA margin, so the earnings drag from investment remains unresolved.
The price and this Narrative do not agree. → Uncover what this Narrative says Photocure is actually worth.
Hunt For Mispriced Cash Engines
Photocure shows how earnings, cash flow and sentiment can diverge for long periods. The real opportunity could sit in stocks that appear undervalued before the market closes the gap.
- Company 1 - 29% below our estimate - use lower funding costs and tighter expenses to deepen secured mortgage and gold lending exposure without stretching credit risk.
- Company 2 - 16% below our estimate - expand healthcare managed services while folding in new platforms to push AI driven claims handling and revenue cycle work.
- Company 3 - 40% below our estimate - convert long term demand for underwater mapping and tracking into orders that pair sensing hardware with connected monitoring systems.
Those are three of them. See all 198 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com