
Banco Santander (BME:SAN) Stock Price Defies Strong Q3 Earnings Report
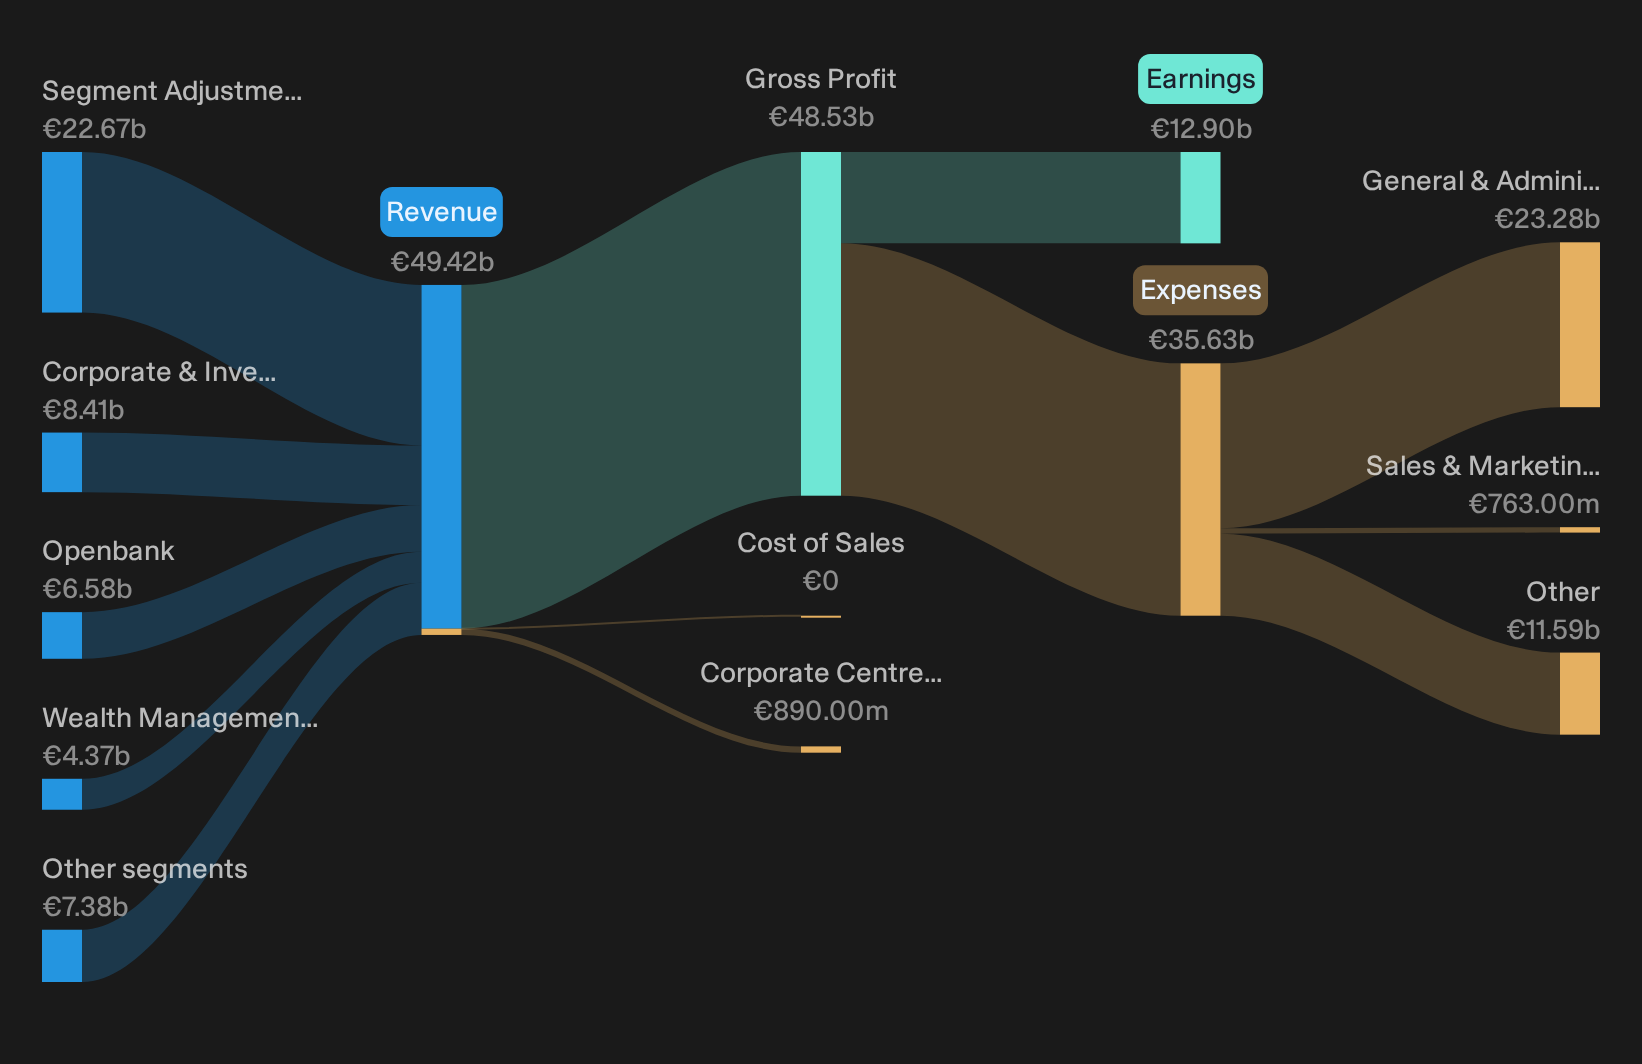
Banco Santander walked into its Q3 2026 report with a bruised share price, down over 14% across the past month and roughly 13% over three months. The reputation is a high return, globally diversified lender. The fresh quarterly print shows a different picture. Basic earnings per share landed at €0.41 and net income from ongoing operations reached €3,750m, helped by record nine month underlying profit flagged on the call. The stock treated that as background noise. The immediate question for investors is why the recent slide jars so sharply with those profit headlines.
Love Banco Santander’s global profit engine but uneasy about a share price that keeps sliding despite those €3,750m earnings headlines? Check out the list of solid balance sheet and fundamentals stocks (207 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): €12,072m vs. €11,183m (up about 8%)
- Net Income from Ongoing Operations (Q3 2026 vs. Q3 2025): €3,750m vs. €2,931m (up about 28%)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.413 vs. €0.187 (up about 121%)
- Non Performing Loans, NPL ratio indicator (Q3 2026 vs. Q3 2025): €36,057m vs. €31,644m (up about 14%)
Earnings tell part of Banco Santander's story, but investors who care about what they are really paying for usually focus on the cash coming in and out of the business. On Banco Santander's cash flows alone, the stock could be a hefty 44% undervalued.
Santander’s Efficiency Story Meets Hard Cost Data
Bullish analysts frame Banco Santander as an efficiency compounding machine powered by tech and scale. The clearest ambition is written into its own transformation targets.
"Bullish analysts expect Banco Santander to use its global platform, AI programs and capital light businesses to compound profit while keeping its cost base under tight control through 2028."
Q3 gives that claim some solid milestones. The efficiency ratio at 42.6% marks the best level in 17 years. Cost per active customer in Retail & Openbank fell 5%. Payments units show similar discipline, with Getnet cutting cost per payment by 39%. Those concrete savings support an efficiency led bull story more than sentiment does.
One Narrative disagrees with today's price. → See where this Narrative says Banco Santander should trade.
Bear Credit Fears Meet Mixed Q3 Signals
Bears argue Banco Santander is leaning too hard into unsecured and cyclical lending just as conditions could turn.
"Growing exposure to unsecured and cyclical activities such as U.S. auto, consumer finance and Latin American corporates in a still volatile macro backdrop heightens the risk that currently benign credit trends reverse, forcing higher loan loss provisions and reducing net income."
Q3 credit quality does not break, yet there are stress points. The non performing loan stock reached €36,057m, up 14% year on year, even as net income from ongoing operations rose to €3,750m. Earnings still look healthy, although the higher NPL base shows that credit risk is edging in the direction bears worry about.
Hunt For Mispriced Profit Engines
Banco Santander shows how a strong earnings story can sit beside a sliding share price. The real opportunity could sit in stocks that look mispriced before the crowd catches up.
- Company 1 - 42% below our estimate - expands composite structures and aftermarket services as air travel demand reshapes aircraft build rates and new mobility programs.
- Company 2 - 31% below our estimate - tightens margins through operational programs while integrating valves acquisition into higher value aftermarket and nuclear heavy projects.
- Company 3 - 26% below our estimate - sells grid diagnostics and test systems as electrification and digital monitoring change how utilities specify critical equipment.
That is three of the list. See all 198 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com