
SiteOne Landscape Supply (SITE) Q3 Results Show Margin Gains Outrunning Flat Demand
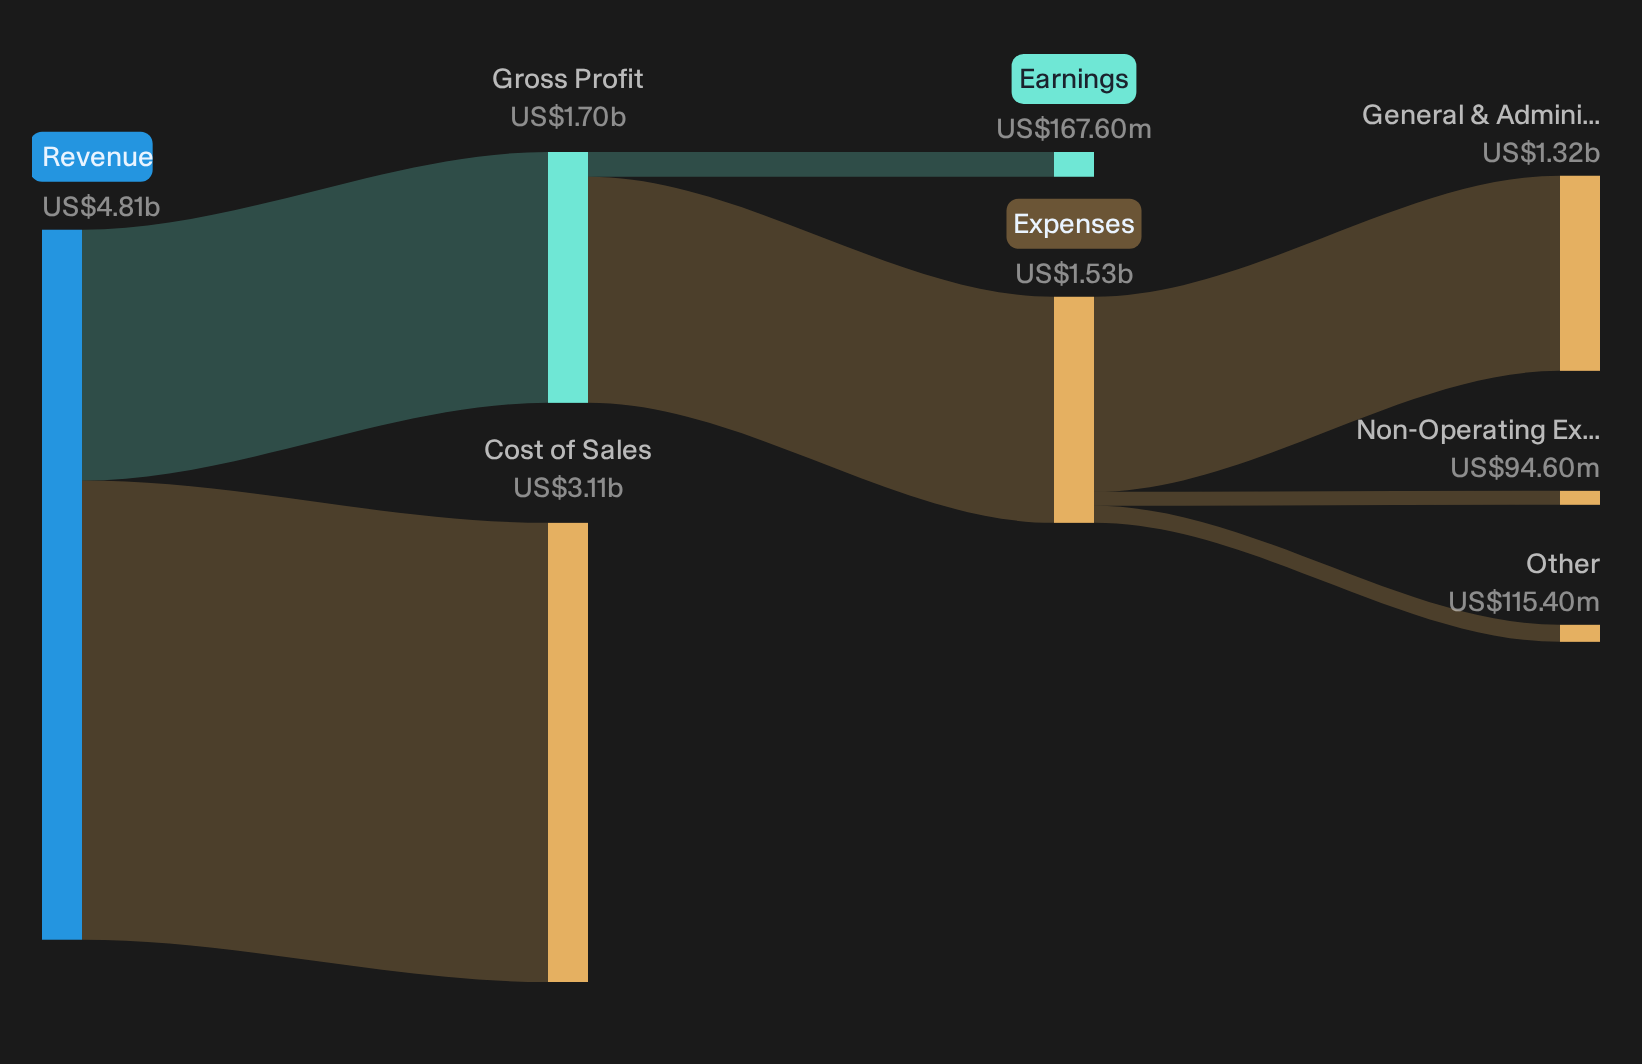
SiteOne Landscape Supply arrived at its Q3 2026 report with the stock already grinding higher over the past month, then added another 0.9% to close at US$104 after the release. That small move understates what actually hit the tape. Net sales reached US$1.29b and adjusted earnings before interest, tax, depreciation and amortisation climbed to US$138.3m, with adjusted EBITDA margin widening to 10.7%. For a distributor often viewed as a low-margin volume story, this quarter was about pricing power and cost work quietly stretching profitability while the share price reaction stayed muted.
Like the way SiteOne Landscape Supply is squeezing more profit out of each dollar of sales but want a broader set of distributors and industrials with healthy margins and sturdy finances? Check out the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,291.1m vs. US$1,258.2m (up 2.6%)
- Net Income (Q3 2026 vs. Q3 2025): US$63.9m vs. US$59.1m (up 8.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.46 vs. US$1.32 (up 11.0%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 10.7% vs. 10.1% (expanded 60 bps)
SiteOne boosted buybacks even as organic demand stayed flat. Ask Charlie what SiteOne’s bigger buyback says about management’s conviction.
SiteOne’s Self Help Story Meets Hard Numbers
The bullish pitch around SiteOne Landscape Supply hinges on internal fixes doing the heavy lifting for margins and earnings rather than relying primarily on additional deals.
"The main thing that has to go right is continued execution on self help levers such as private label expansion, branch turnarounds, delivery and procurement efficiency, and digital adoption so that EBITDA margins move toward management’s multi year targets."
Q3 provides a concrete checkpoint. Adjusted EBITDA margin widened to 10.7% as gross margin improved 80 bps and delivery expense fell more than 35 bps. Private brands grew 23% in the quarter and digital sales climbed more than 45% year to date, with organic daily sales roughly flat.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Bear Case on SiteOne Meets Mixed Evidence
Bearish views focus on SiteOne Landscape Supply’s ability to fix underperforming locations while costs stay stubborn.
"Although SiteOne is leaning on focused branch turnarounds, private label expansion and digital tools to help move EBITDA margin toward a 13% target, the company is still working through more than 100 underperforming branches and a large Pioneer turnaround."
Q3 shows the margin tools working, with gross margin up 80 bps and adjusted EBITDA margin at 10.7%. Even so, Organic Daily Sales were slightly negative and SG&A as a percentage of sales ticked higher, and management is taking restructuring charges in Q4. The turnaround is progressing, but the drag from weaker volumes and cost pressure has not fully cleared.
Hunt Quiet Disconnects In Plain Sight
SiteOne Landscape Supply just showed how margin work can matter more than headline sales for a quarter. The real opportunity sits in finding stocks that fundamental analysis suggests may not fully reflect their business drivers.
- Company 1 - 23% below our estimate - uses surgical robotics and higher acuity procedures to shift complex operations onto a recurring hardware and services platform.
- Company 2 - 32% below our estimate - sells GPU infrastructure and integrated software that data centres adopt when scaling intensive AI workloads beyond early pilots.
- Company 3 - 25% below our estimate - turns demand for advanced cardiometabolic and obesity treatments into extended volume agreements supported by expanded manufacturing facilities.
Those are three of them. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com