
Shikoku Kasei Holdings (TSE:4099) Looks Pricey Following Board Change Review
Shikoku Kasei Holdings (TSE:4099) has called a board meeting for 27 October 2026 to review potential changes to its representative directors and officers, a governance move that can reshape how the business is steered.
For investors watching the tape, Shikoku Kasei Holdings has paired this governance announcement with strong momentum. The year-to-date share price return is 74.69% and the 1-year total shareholder return is 74.30%, supported by a 3-year total shareholder return of 192.17% and a 5-year total shareholder return of 267.83%.
Scan how Shikoku Kasei Holdings fits into the wider momentum story by comparing it against a hand-picked 72 high quality undiscovered gems.
Bulls see Shikoku Kasei Holdings as a governance-backed momentum story, while bears see a hot stock priced for perfection. Which case do the current valuation markers lean toward as this board meeting approaches?
Price-to-Earnings of 18.1x: Is it justified?
On current figures, Shikoku Kasei Holdings trades on a P/E of 18.1x, which lines up with a share price of ¥2,381. The market is treating this as a premium to peers and to its own earnings profile.
The P/E ratio compares the stock price with earnings per share and gives a shorthand view of how much investors are willing to pay for each unit of profit. For a chemicals group like Shikoku Kasei Holdings, this is often a go-to yardstick because earnings tend to track the cycle and investors often anchor expectations to profit power rather than sales alone.
Here, the market is placing a higher price tag on those earnings. The P/E of 18.1x is above the JP Chemicals sector average of 12.5x, above the peer average of 14.1x, and above an estimated fair P/E of 14.5x that the market could move toward if sentiment cools.
Explore the SWS fair ratio for Shikoku Kasei Holdings.
Result: Price-to-Earnings of 18.1x (OVERVALUED)
Still, the Shikoku Kasei Holdings story can change quickly if the board reshuffle unsettles leadership direction or if earnings momentum fades relative to that premium P/E.
Find out about the key risks to this Shikoku Kasei Holdings narrative.
Another View: What The SWS DCF Model Says
That rich P/E story meets a cooler read from the SWS DCF model. On this approach, Shikoku Kasei Holdings at ¥2,381 sits above an estimated future cash flow value of ¥2,284.34, so the shares screen as overvalued. Which signal do you trust more, earnings multiple or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
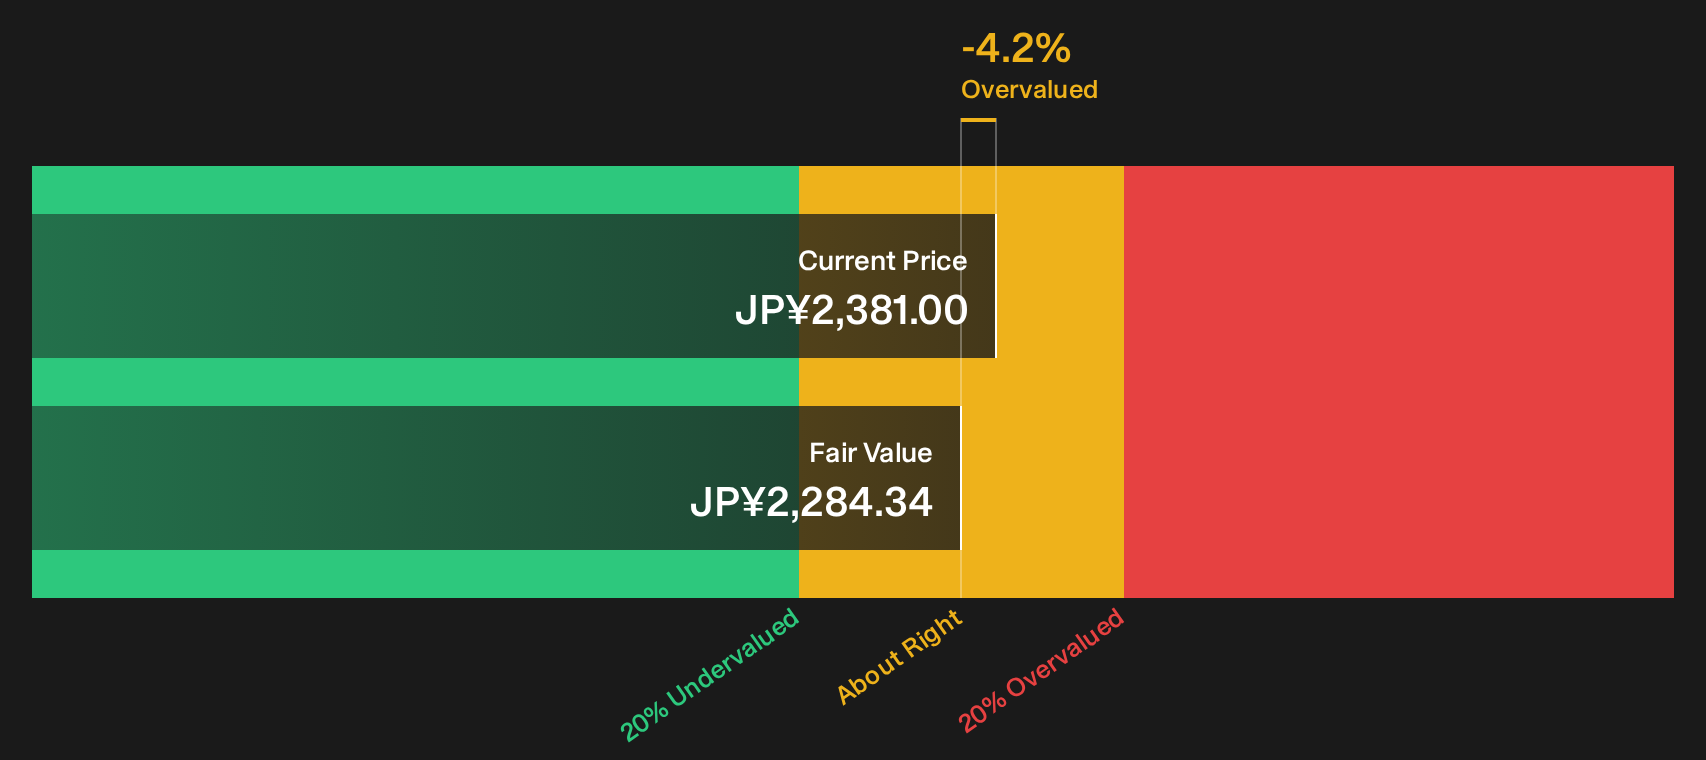
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shikoku Kasei Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So is Shikoku Kasei Holdings priced for perfection, or just reflecting justified enthusiasm around governance and cash flow expectations as the board meeting nears? Act while sentiment is still forming by reviewing the key issues for yourself and weighing both sides of the story through 2 key rewards and 1 important warning sign
Looking for more Shikoku Kasei Holdings style ideas?
If you rate what is happening around Shikoku Kasei Holdings, do not stop here. Fresh opportunities often show up first in objective screeners.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that filters for financial strength before excitement.
- Zero in on value by reviewing a 15 high quality undervalued stocks that blends quality fundamentals with pricing that still looks reasonable.
- Stack potential returns with stability by checking a 29 dividend fortresses that focuses on companies offering higher income profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com