
BASF (XTRA:BAS) Q3 Earnings Leave Cash Flow Questions Unanswered
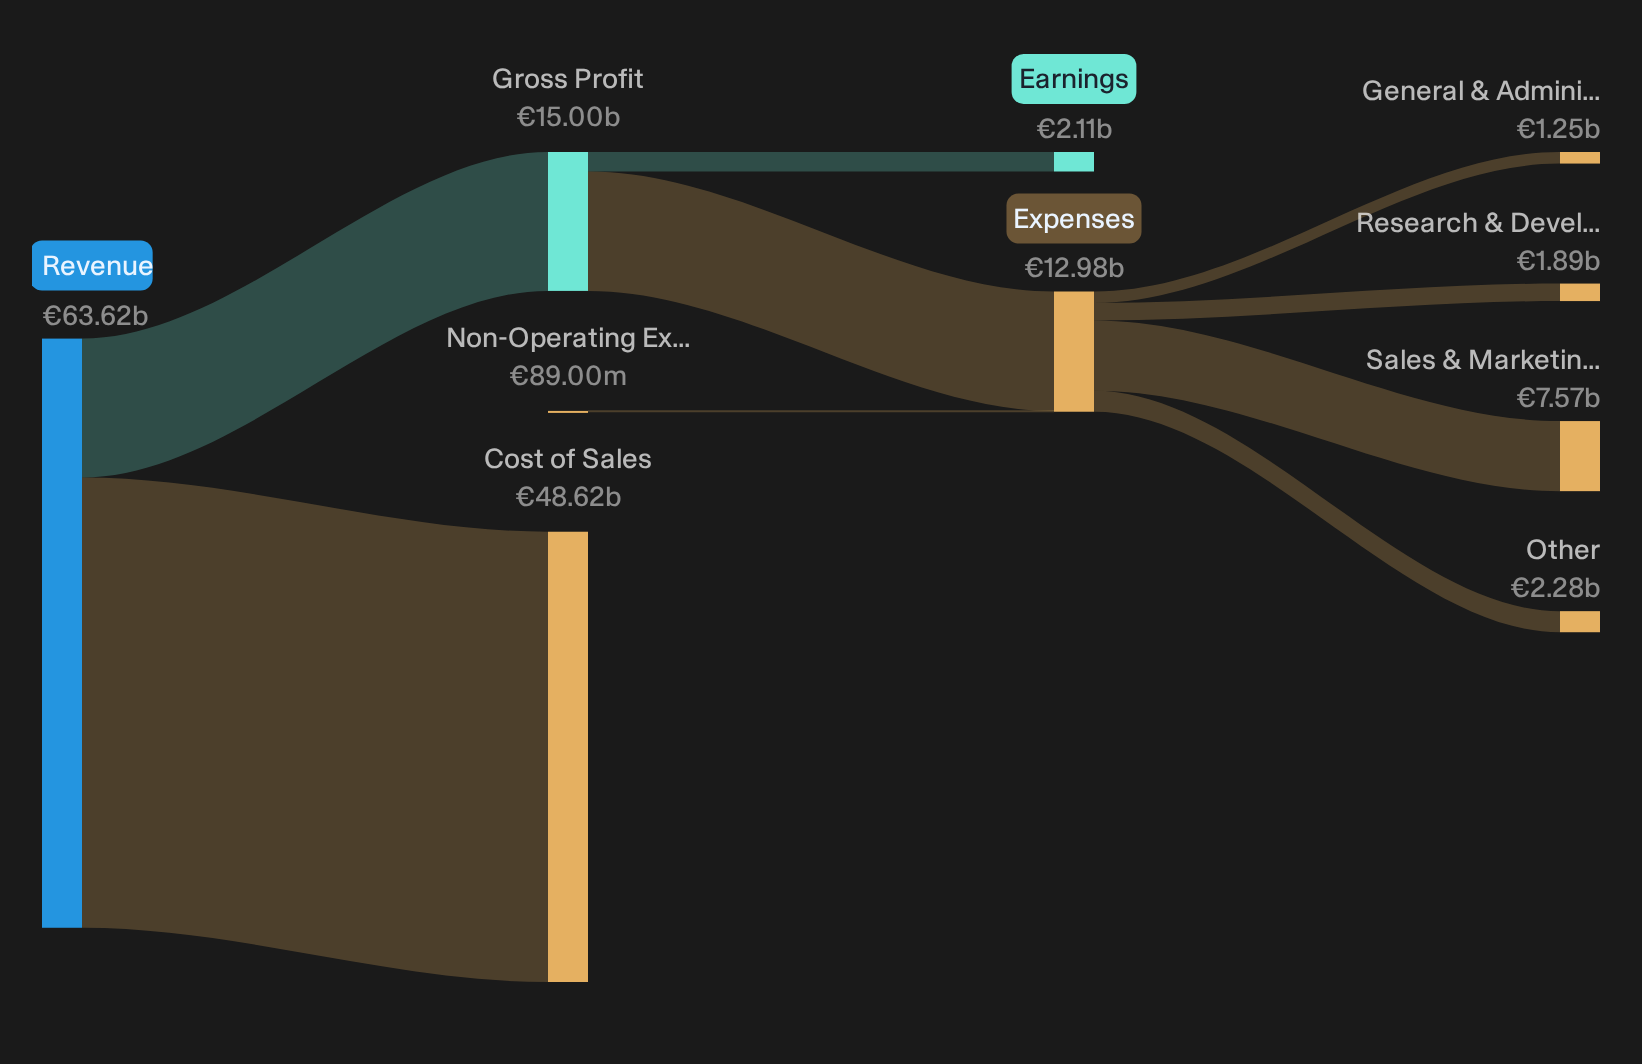
BASF entered its Q3 2026 earnings with the stock at €52.84, roughly flat over the past week and modestly higher over the past month. On the surface, a basic earnings per share figure of €0.18 and net income of €155m look underwhelming for a global chemicals heavyweight.
The market is reacting to a single quarter. Longer term investors are staring at a different tension. Trailing earnings are up sharply over the past year and the current P/E multiple sits above the broader European chemicals sector, while the shares trade far below a discounted cash flow estimate of €113.36.
Like the idea of BASF trading well below a DCF estimate but uneasy about paying a richer P/E for muted quarterly earnings power? Compare it with other potential deep value opportunities in our 196 high quality undervalued stocks
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €16,360m vs. €14,328m (up about 14%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): €155m vs. €140m (up about 11%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.18 vs. €0.16 (up about 15%)
- EBITDA before special items (Q3 2026 vs Q3 2025): €1.6b compared with the prior-year period (up 15%)
Management called a BASF–Evonik tie-up logical but strictly optional. Ask Charlie what BASF isn’t saying about an Evonik deal.
BASF Bull Case Leans On Cost Wins And China Ramp
The bullish story hangs on execution, especially in China and on fixed cost cuts.
"The main thing that has to go right is continued execution on the China Verbund expansion and the CoreShift cost program, including delivering the targeted fixed cost reductions and high utilization at Zhanjiang."
BASF is hitting clear milestones on this script. Cash fixed costs are down about 3% year on year and EBITDA before special items is running ahead of last year, which points to early progress on the cost reset. Zhanjiang is operating at high utilization and helping Greater China volumes and pricing, even though the site still reports slightly loss making EBITDA as start up costs weigh on the P&L.
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there.
BASF Bear Case: Earnings Up, Cash Story Still Soft
The key worry is that rising EBITDA does not fix the balance sheet story.
"The main thing that has to go right is that BASF converts its ongoing cost savings, portfolio reshaping and China focused Zhanjiang ramp up into sustainable free cash flow after current negative quarters that include working capital build and transformation cash outflows."
Q3 shows that concern is not resolved. EBITDA before special items is €6.4b year to date and guidance is tighter at €7.4 to €7.8b, yet free cash flow is still a €1.0b outflow. Working capital absorbed €1.5b and restructuring cash costs stay heavy into 2027. Net debt is guided to about €15b, so the stronger profit guidance has not yet translated into clear balance sheet improvement.
Hunt For Mispriced Cash Generators
BASF shows how earnings, cash flow and valuation can present different signals in one stock. The real opportunity is finding companies that may be undervalued before the market narrows that gap.
- Company 1 - 29% below our estimate - turn a record equipment and service backlog into higher margin projects as offshore operations become a contributor.
- Company 2 - 31% below our estimate - shift capacity toward higher margin composite and clean energy products while automation and tighter capital use support cash generation.
- Company 3 - 35% below our estimate - convert long dated defense, electrification and industrial contracts into steady electronics production as new facilities and acquisitions expand capacity.
That is three of the list. See every one of the 196 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com