
UBS Group (SWX:UBSG) Could Be 14% Undervalued After Q3 Earnings
UBS Group (SWX:UBSG) is back in focus after its Q3 2026 earnings call on 28 October, alongside fresh numbers on net income and recently completed share repurchase activity.
Recent trading tells a mixed story. UBS Group shares are at CHF38.60, with the 1 month share price return down 4.7% and the 3 month share price return down 9.4%. However, the 1 year total shareholder return of 29.4% and 5 year total shareholder return of 161.9% point to momentum that has built over time, as buybacks and consistent net income figures shape how investors weigh upside potential against banking sector risk.
Scan how UBS Group stacks up against other global financial players using a curated list of list of solid balance sheet and fundamentals (204 results) to see where capital is quietly regrouping after recent earnings and buyback news.
UBS Group has given shareholders a sharp run over the past year, while the last quarter has cooled the mood. Has most of the upside already played out or do the current numbers still leave meaningful room on valuation?
Most Popular Narrative: 14% Undervalued
On the most followed view, UBS Group is worth CHF44.87 per share, which sits above the latest CHF38.60 close and frames the recent pullback as a discount rather than a ceiling.
The ongoing integration of Credit Suisse is now delivering most of the targeted cost synergies and Non-core & Legacy balance sheet reduction, and the plan to complete the integration program by the end of 2026 leaves further scope for UBS Group to convert remaining cost saves and lower NCL operating expenses into higher net margins and earnings power.
See why 63 investors see UBS Group as 14% undervalued.
Result: Fair Value of CHF44.87 (UNDERVALUED)
Still, the bullish UBS Group story can crack if tighter Swiss capital rules absorb more than US$22b of CET1, or if fresh regulatory cases push legal and compliance costs higher.
Find out about the key risks to this UBS Group narrative.
Another View: UBS Group Through The P/E Lens
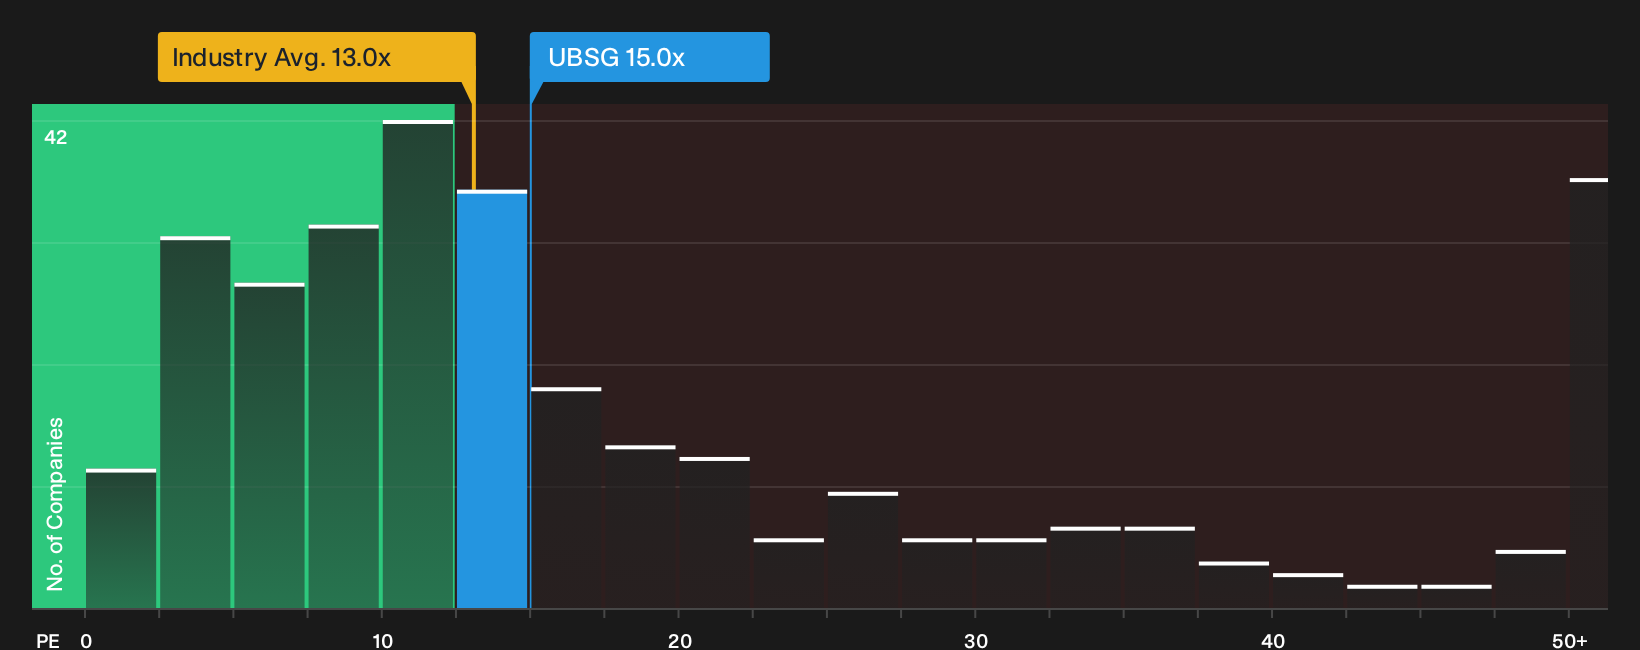
That 14% undervaluation story leans on a fair value of CHF44.87, yet the P/E picture is less straightforward. UBS Group trades on 14.7x earnings, above the European Capital Markets average of 13x but below a peer average of 16.8x and a fair ratio of 21.7x. Is this a cushion or a value trap in the making?
For a closer look at how that earnings multiple could shift over time, and what a move toward the fair ratio might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment this split around UBS Group, treat the latest results as your starting point rather than the final word, and weigh both sides of the story. Review the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond UBS Group?
If UBS Group has sharpened your thinking, do not stop here. Broader context from other quality businesses can reset what you consider a reasonable risk and potential reward.
- Stack potential upside against quality by scanning a focused group of 195 high quality undervalued stocks that combine pricing pressure with underlying business strength.
- Strengthen your income stream by reviewing 224 dividend fortresses that pair higher yields with balance sheets built to handle rough patches.
- Reduce stress on your portfolio by filtering for 224 resilient stocks with low risk scores that score well on resilience instead of forcing returns through volatility alone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com