
ENCE (BME:ENC) Stock Price Lags Its Q3 Earnings Turnaround
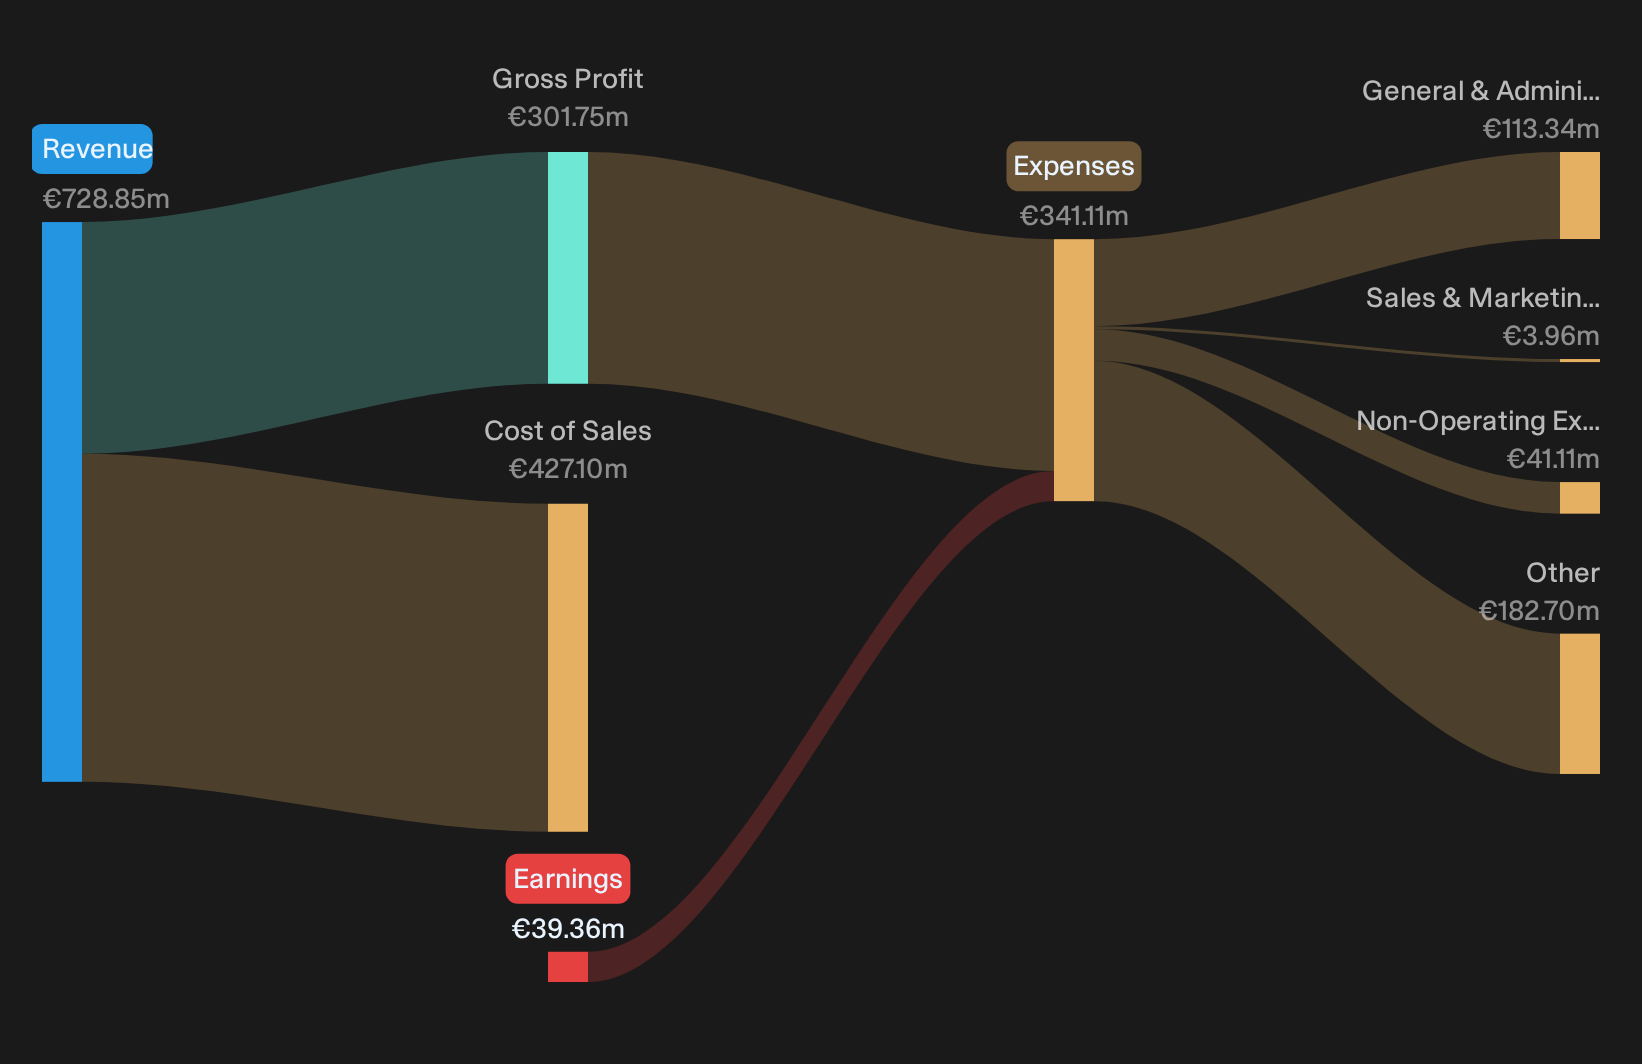
ENCE Energía y Celulosa just posted its Q3 2026 scorecard and the headline is simple. The pulp and renewables group swung to a €10.2m profit on €215.9m in revenue after a run of losses. The share price, at €2.23 after a 7 day slide and a double digit drop over three months, still trades as if investors do not fully trust the recovery story.
The strongest positive trend is the earnings rebound. Market mood remains cautious while the income statement finally shows clear improvement. That gap between emotion and hard numbers is where the real story sits today.
Love ENCE Energía y Celulosa’s return to profit but concerned the market still prices it like a fragile turnaround? Check our screener of stocks that pair recovery stories with stronger balance sheets and cash generation in the list of solid balance sheet and fundamentals stocks (204 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €215.9m vs. €181.3m (up about 19%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): profit of €10.2m vs. loss of €15.1m (returned to the black)
- Basic EPS (Q3 2026 vs Q3 2025): €0.04 per share vs. loss of €0.06 per share (swung back to positive earnings per share)
- EBITDA (Earnings Before Interest, Tax, Depreciation and Amortization, Q3 2026 vs Q3 2025): €46m vs. €13m (more than tripled)
ENCE’s biomethane pipeline is already 4x its 2030 target. Ask Charlie what ENCE’s biomethane pipeline means for future earnings.
ENCE bull case: mix shift and cost plan on trial
The optimistic view on ENCE Energía y Celulosa hangs on a cleaner pulp mix and lower unit costs feeding through to steadier cash. That is the ambition.
"ENCE Energía y Celulosa is pushing ahead with a shift toward higher margin special pulp grades, with these products already at 34% of volumes and targeted above 62% by 2028, and an estimated incremental EBITDA margin of about €36 per tonne over standard pulp that can support higher net margins if volumes ramp as planned."
Special grades now account for 32% of sales year to date, only a small step from 29% in 9M 2025, so the mix shift is real but gradual. The Efficiency and Competitiveness Plan is largely on track, with €14.7m of annualised savings against a €15m objective, yet cash cost guidance has risen to €475 per tonne as new regulatory and inflation pressures offset some of that work.
ENCE bear case: capex strain and renewables fragility tested
On the cautious side, investors worry that heavy spending and fragile green energy operations could choke the ENCE Energía y Celulosa investment story.
"High and front loaded CapEx, combined with net debt of €493 million and working capital outflows, could strain ENCE Energía y Celulosa's balance sheet if cash generation is weaker than expected. This may restrict investment in special pulp, renewable industrial heating and biomethane projects and weigh on future revenue and earnings."
Q3 data partly challenges that concern. Net debt has fallen to €467m and free cash flow was positive at about €10m, helped by a €16m working capital release. Liquidity looks solid with €196m of cash and an undrawn €130m revolver, while renewables EBITDA reached €13m with biomass production recovering, indicating prior disruptions did not carry into this quarter.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt Disconnected Earnings Stories
ENCE Energía y Celulosa shows earnings moving in one direction while sentiment diverges. The real opportunity is finding stocks that may be undervalued before the market fully recognizes them.
- Company 1 - 48% below our estimate - build a multi asset investment platform as customers shift savings into digitally held equities and ETFs.
- Company 2 - 25% below our estimate - expand copper projects as tighter concentrate markets and new polymetallic output reshape production mix.
- Company 3 - 30% below our estimate - shift revenue toward higher margin specialty chemicals as new nutrition and defense capacity comes online.
That is three of the list. See every one of the 192 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com