
Be Sure To Check Out Pitti Engineering Limited (NSE:PITTIENG) Before It Goes Ex-Dividend
Some investors rely on dividends for growing their wealth, and if you're one of those dividend sleuths, you might be intrigued to know that Pitti Engineering Limited (NSE:PITTIENG) is about to go ex-dividend in just 3 days. The ex-dividend date generally occurs two days before the record date, which is the day on which shareholders need to be on the company's books in order to receive a dividend. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Accordingly, Pitti Engineering investors that purchase the stock on or after the 2nd of November will not receive the dividend, which will be paid on the 21st of November.
The company's upcoming dividend is ₹2.00 a share, following on from the last 12 months, when the company distributed a total of ₹2.50 per share to shareholders. Looking at the last 12 months of distributions, Pitti Engineering has a trailing yield of approximately 0.3% on its current stock price of ₹871.60. If you buy this business for its dividend, you should have an idea of whether Pitti Engineering's dividend is reliable and sustainable. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. Pitti Engineering has a low and conservative payout ratio of just 8.0% of its income after tax. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. It paid out 11% of its free cash flow as dividends last year, which is conservatively low.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Pitti Engineering
Click here to see how much of its profit Pitti Engineering paid out over the last 12 months.
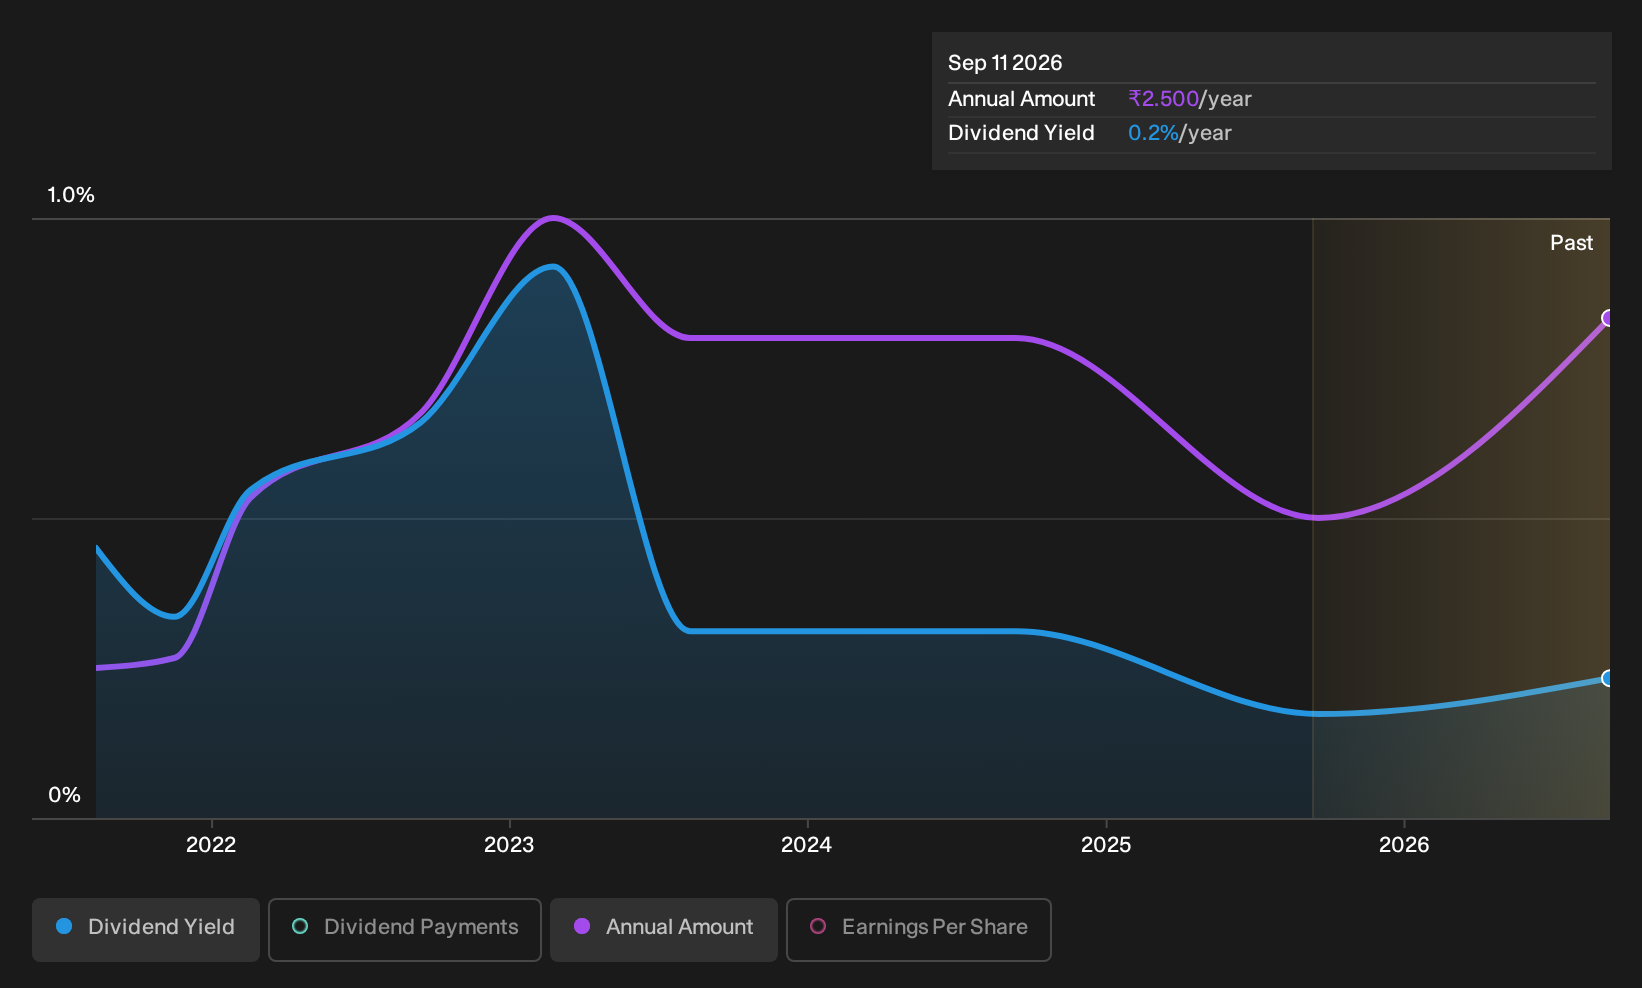
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. Investors love dividends, so if earnings fall and the dividend is reduced, expect a stock to be sold off heavily at the same time. That's why it's comforting to see Pitti Engineering's earnings have been skyrocketing, up 29% per annum for the past five years. Pitti Engineering looks like a real growth company, with earnings per share growing at a cracking pace and the company reinvesting most of its profits in the business.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. Pitti Engineering has delivered an average of 27% per year annual increase in its dividend, based on the past five years of dividend payments. It's exciting to see that both earnings and dividends per share have grown rapidly over the past few years.
The Bottom Line
Should investors buy Pitti Engineering for the upcoming dividend? It's great that Pitti Engineering is growing earnings per share while simultaneously paying out a low percentage of both its earnings and cash flow. It's disappointing to see the dividend has been cut at least once in the past, but as things stand now, the low payout ratio suggests a conservative approach to dividends, which we like. Pitti Engineering looks solid on this analysis overall, and we'd definitely consider investigating it more closely.
So while Pitti Engineering looks good from a dividend perspective, it's always worthwhile being up to date with the risks involved in this stock. For example, we've found 1 warning sign for Pitti Engineering that we recommend you consider before investing in the business.
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.