
What Amazon Earnings Preview Means For Shareholders
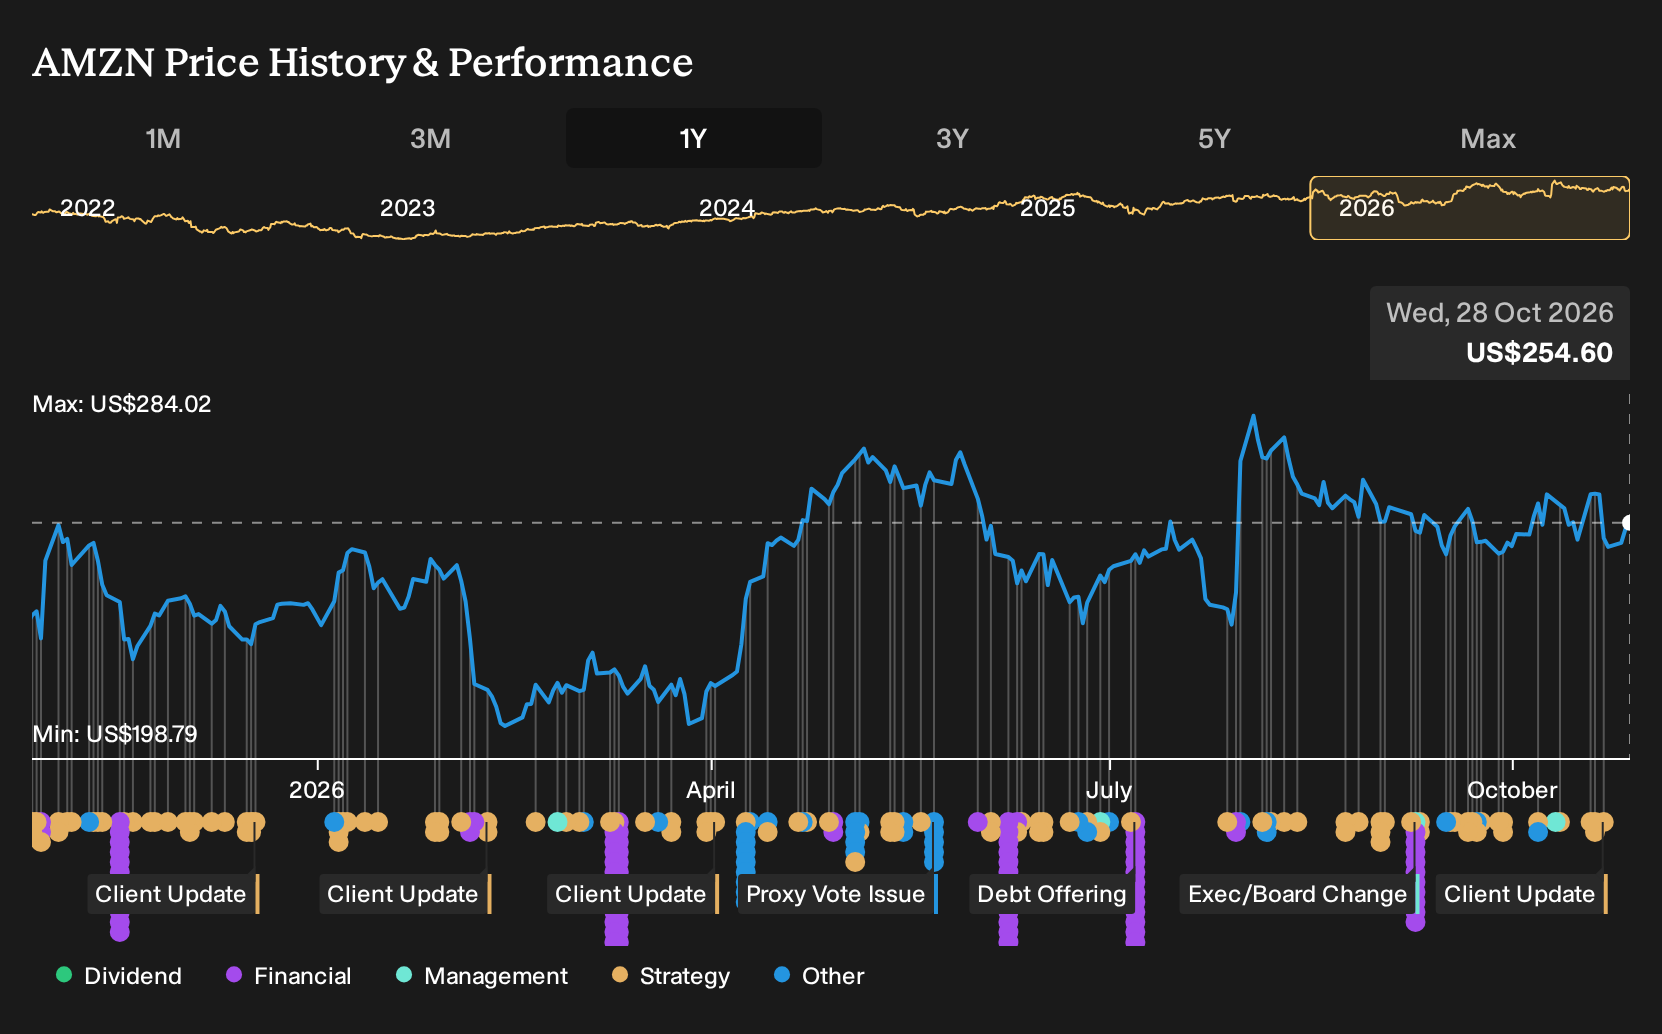
- In the past week, attention on Amazon.com has intensified as the company heads into its Q3 2026 earnings release, with investors tracking how heavy AI and cloud infrastructure spending is influencing AWS performance, operating income and cash needs.
- The focus on AI related capital expenditure, including data centers, custom chips and satellite projects, highlights how dependent Amazon.com’s long term cash generation may be on converting that buildout into durable cloud and AI contracts.
- This raises questions about how Amazon.com’s investment narrative aligns with heavy AI focused CapEx as Q3 earnings scrutiny builds around AWS.
Scan how Amazon.com’s AI heavy spending story compares with other potential beneficiaries of the same trend by running through our hand picked 54 AI infrastructure stocks.
Amazon.com Investment Narrative Recap
To back Amazon.com as a shareholder, you need to believe its heavy AI, AWS and logistics investments convert into long term, high margin service revenue, while retail and devices keep feeding traffic and data. The key short term catalyst is whether Q3 2026 results show AWS and AI contracts scaling fast enough to justify roughly US$220b of 2026 CapEx.
The biggest near term risk sits in that same spending, plus energy and regulatory costs tied to data centers and satellites. Recent launches in devices, ads and consumer partnerships mainly reinforce existing demand channels rather than materially changing the earnings setup heading into this week’s report.
Among recent updates, ModelOp’s launch of Center 3.5 looks most relevant for Amazon.com right now. The software hooks into Amazon Bedrock AgentCore, Amazon Quick and frontier models on Bedrock, and then centralizes governance for enterprises that run AI across multiple providers. That speaks directly to how corporate clients might standardize large AI footprints that include AWS.
For investors, this matters less as a revenue event today and more as a proof point that third party tools are wiring Amazon’s AI stack into broader enterprise workflows. Stronger ecosystem pull can support AWS backlog and AI related usage, while execution risk still lies in turning those integrations into long term, contracted spend that covers elevated capital outlays.
Analyst Scenarios Behind Amazon.com's AI Spending
Forecasts tied to Amazon.com try to put hard numbers around what all this AI heavy CapEx might need to deliver. Analysts are working with a picture where top line revenue is assumed to grow by 14.4% each year over the next three years, while profit margins step down from 17.4% today to 14.0% by around 2029 as the business leans into infrastructure buildout.
On earnings, the consensus view points to current profit of about US$135.3b moving to US$163.0b by 2029. That implies an increase of roughly US$27.7b in annual earnings, even as margin assumptions ease. This highlights how much faith is being placed in volume growth from AWS, AI services and newer infrastructure platforms to carry the weight of present spending.
Those profit expectations sit alongside projected earnings per share of US$14.88 by 2029 and an assumed 0.9% yearly increase in the share count over the next three years. To make the analyst price targets work, investors would effectively be underwriting a move from a 20.1x P/E today to about 29.2x on those 2029 earnings, a richer multiple than the current 20.1x P/E ascribed to the wider US multiline retail group.
Pulling the revenue and earnings paths together, the consensus framework has Amazon.com generating about US$1,161.3b of revenue and US$163.0b of earnings in 2029. That setup relies on around 14.4% yearly revenue growth and an earnings increase of roughly US$27.7b from US$135.3b today, with the gap between current and forecast profit effectively acting as the hurdle for today’s AI and cloud investment story.
Uncover why Amazon.com's fair value indicates a 30% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You have 34 fair value opinions from the Simply Wall St Community, with estimates ranging from US$269.78 to US$475.09 for Amazon.com. That spread reflects sharply different views on how AI CapEx, AWS backlog and new projects like Amazon Leo may offset risks from heavy quarterly spending and possible changes in tax treatment. Use it as a prompt to compare multiple viewpoints before deciding how Amazon.com fits your own expectations.
Explore 33 other Amazon.com fair value estimates, including one that suggests it could be worth just $269.78.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amazon.com research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amazon.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amazon.com's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amazon.com?
If the Amazon.com story has sharpened your view on AI and long term cash generation, you can use that same lens to compare other businesses that fit different risk and income profiles through the Simply Wall St Screener.
- For investors who want potential mispricing plus quality, scan a curated pool of companies that combine healthy fundamentals with attractive valuations through the 26 high quality undervalued stocks.
- If capital protection and balance sheet strength matter most to you, filter for businesses with resilient finances and sound fundamentals using the list of solid balance sheet and fundamentals (24 results).
- When you are hunting for ideas that the market may not be paying full attention to yet, cast a wider net across lesser known opportunities via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com