
Is PROG Holdings (PRG) A Bargain As Lower Earnings Guidance Resets Valuation?
PROG Holdings (PRG) reset expectations on 28 October 2026, trimming full year earnings guidance while issuing fresh quarterly targets that give investors a narrower view of near term revenue and profit potential.
That guidance reset landed after a choppy stretch for PROG Holdings, where the share price return over the past 90 days fell 28.12%, even though the year-to-date share price return remains positive at 5.14% and the three-year total shareholder return is 16.44%. This points to longer-term holders seeing a very different experience compared with recent short-term momentum.
Stress test your reaction to PROG Holdings' guidance reset by comparing it with a hand-picked 32 resilient stocks with low risk scores that have held steadier through recent swings.
PROG Holdings still runs a sizeable lease to own and BNPL operation with over US$2.6b in annual revenue, yet the share price just reset hard. Is that business now mispriced, or is it fairly tagged for its risks?
Most Popular Narrative: 42% Undervalued
On the most followed view, PROG Holdings screens as undervalued with a fair value of $53.43 against a last close of $30.88. This puts the recent guidance reset against a valuation gap that the narrative ties to how its ecosystem could compound earnings over time.
Ongoing traction in diversifying revenue through additional platforms in the ecosystem, including Purchasing Power’s rising GMV and expanding adjusted EBITDA contribution and MoneyApp within the broader suite, supports a larger consolidated profit base that is not solely tied to Progressive Leasing earnings.
See why 5 investors see PROG Holdings as 42% undervalued.
Result: Fair Value of $53.43 (UNDERVALUED)
Still, PROG Holdings faces a clear catch. Any renewed pressure on credit performance or a stall in Four Technologies and Purchasing Power could quickly weaken this narrative.
Find out about the key risks to this PROG Holdings narrative.
Another View: What PROG Holdings’ P/E Is Really Saying
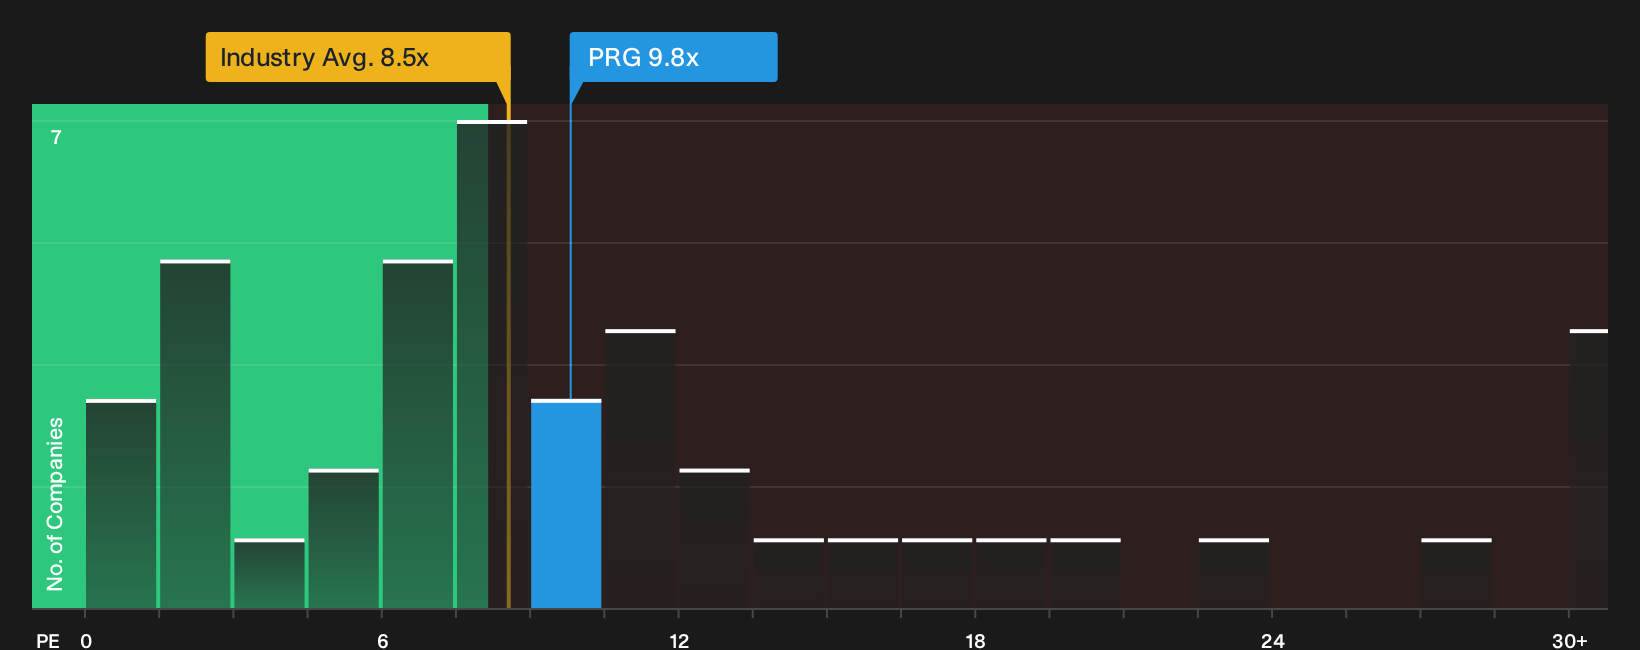
There is a catch to the 42% undervalued story. On simple P/E, PROG Holdings trades at 9.8x earnings, which is richer than both the US Consumer Finance sector at 8.5x and its peer set at 8.9x, while still below a fair ratio of 12.4x that the model suggests the market could move toward. That mix of discount to fair ratio and premium to peers leaves you weighing whether this is mispricing or just extra valuation risk tied to its business model.
To stress test that P/E view against the underlying earnings assumptions, it helps to see what the detailed valuation work says, including how cash flows and multiples line up in one place: See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the PROG Holdings story can either cloud judgment or sharpen it, depending on how you use the information in front of you. Move quickly to review both sides of the ledger by weighing the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond PROG Holdings?
Round out your view on PROG Holdings by comparing it with other opportunities that share some of the qualities you care about most.
- Target resilient opportunities by scanning a 32 resilient stocks with low risk scores that has tended to hold up better when sentiment turns choppy.
- Hunt for value by running through a 19 high quality undiscovered gems that pairs solid fundamentals with relatively low market attention.
- Build a sturdier core by reviewing a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio through different market conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com