
Simpson Manufacturing (SSD) Could Be 13% Undervalued As Results Beat And Buyback Lands
Why Simpson Manufacturing's fresh guidance and buyback matter now
Simpson Manufacturing (SSD) just paired third quarter 2026 results that modestly exceeded expectations with updated margin guidance and a new US$1.0b share repurchase authorization, drawing fresh attention from investors.
Recent trading reflects that news flow. Simpson Manufacturing’s share price has climbed 9.13% over the past month and 15.80% year to date, while the 5-year total shareholder return of 73.35% points to a solid longer term payoff profile.
Scan how Simpson Manufacturing compares with peer construction plays by reviewing a curated set of list of solid balance sheet and fundamentals (24 results) that have recently attracted renewed interest from investors.
The recent jump in Simpson Manufacturing now sits between two stories: steadier margins and a larger buyback on one side, and a sentiment reset on the other. How far does the current share price already reflect both?
Most Popular Narrative: 13% Undervalued
Simpson Manufacturing’s most followed valuation storyline pegs fair value at $219 per share, above the recent $190.74 close. This puts the latest guidance, cash returns and share move in sharper context.
The accelerating adoption of off-site, modular and mass timber construction solutions continues to support high performance engineered fasteners and connectors. Recent high single-digit to double-digit OEM volume growth suggests further potential contribution to Simpson Manufacturing revenue and earnings.
Heightened building code requirements and the priority on resilient, sustainable structures are still increasing demand for advanced connectors, adhesives and seismic reinforcement solutions. This keeps Simpson Manufacturing well placed to win higher value project work that can support net margins and earnings.
See why 5 investors see Simpson Manufacturing as 13% undervalued.
Result: Fair Value of $219 (UNDERVALUED)
Still, muted 2.7% annual revenue growth and earnings per share contraction, alongside tougher price-based competition in fasteners, could quickly challenge this Simpson Manufacturing upside story.
Find out about the key risks to this Simpson Manufacturing narrative.
Another View: Simpson Manufacturing Through A DCF Lens
The popular Simpson Manufacturing story leans on a fair value of $219, yet the Simply Wall St DCF model points to a future cash flow value of $187.21 versus the current $190.74 price, which implies the shares screen slightly overvalued on this yardstick. Which yardstick do you trust more for your own process?
For readers who want to see how that cash flow based estimate is built line by line, Look into how the SWS DCF model arrives at its fair value.
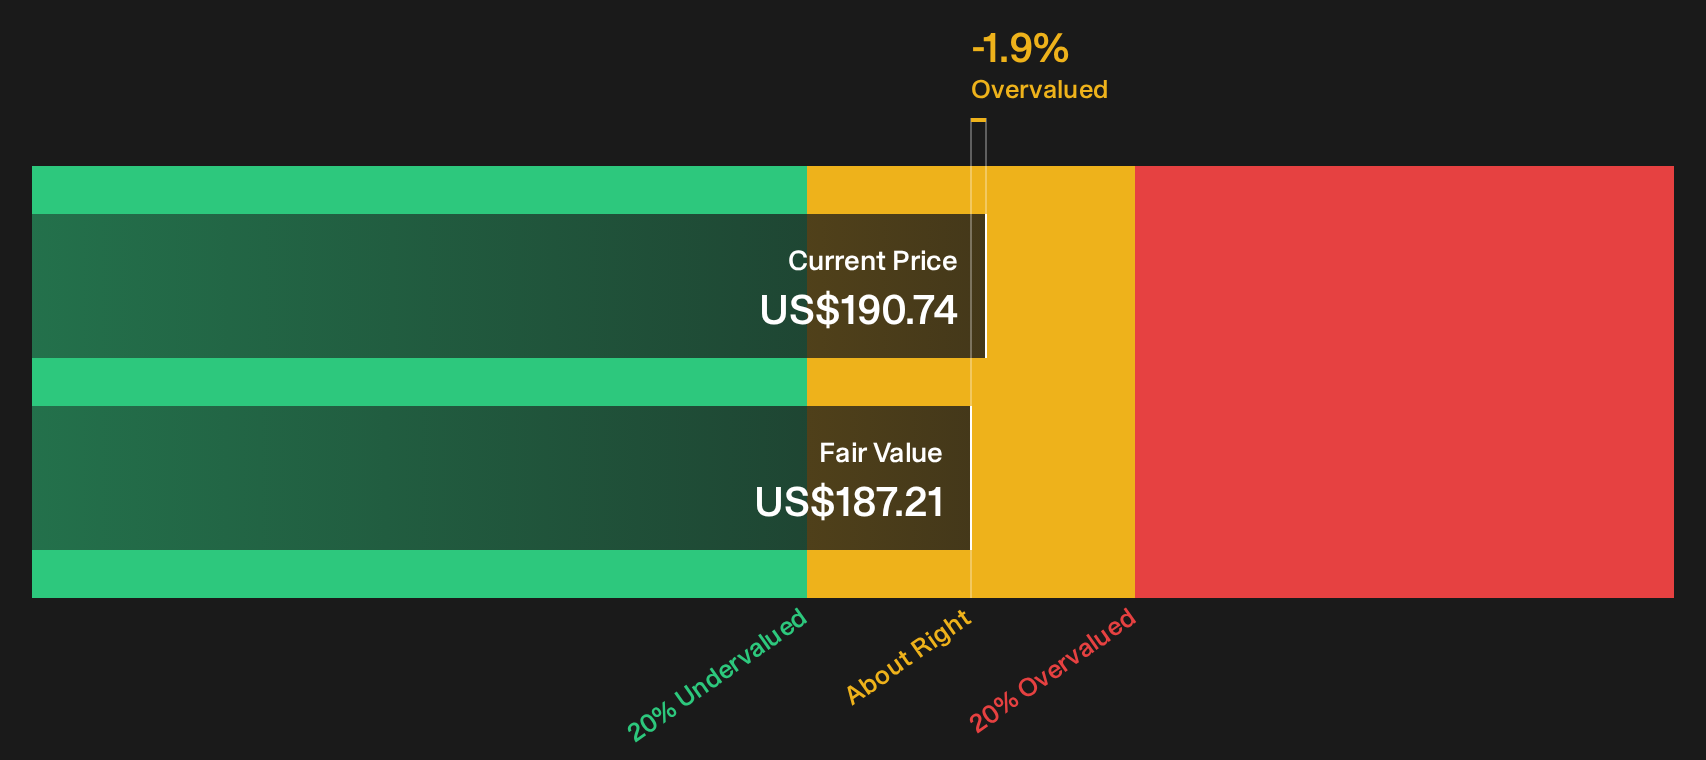
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Simpson Manufacturing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on Simpson Manufacturing leave you unsure, that is the point. Move quickly, review the numbers yourself carefully, and weigh both sides of the story with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Simpson Manufacturing?
Simpson Manufacturing might already be on your radar, but widening your watchlist with a few targeted themes can sharpen your next move.
Use the Simply Wall St screener to uncover fresh opportunities that match your risk appetite, income goals, and quality preferences before others get there first.
- Target quality at a discount by scanning a curated pool of 26 high quality undervalued stocks that combine stronger fundamentals with appealing pricing.
- Lock in potential income streams by focusing on 6 dividend fortresses that aim to pair higher yields with more resilient payouts.
- Prioritise capital protection by reviewing 32 resilient stocks with low risk scores that show sturdier balance sheets and more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com