
Advantest (TSE:6857) Raises Guidance On AI Demand, Is The Upside Already Priced In?
Advantest (TSE:6857) has drawn fresh attention after management raised full year earnings guidance, increased the dividend, introduced a new share repurchase plan, and linked the outlook to demand from artificial intelligence driven chip testing.
The recent guidance upgrade, dividend lift and share repurchase plan come on top of a strong run in Advantest’s shares, with a 90 day share price return of 25.04% and a year to date gain of 64.96%, while the 5 year total shareholder return above 10x indicates that investors have been steadily reassessing both growth potential and risk around AI linked semiconductor testing.
See how other AI focused chip testers and enablers are reacting to this surge in demand with the curated 54 AI infrastructure stocks.
After this kind of run, either Advantest has already pulled most of its future return into the present or today’s price still leaves meaningful upside. The current valuation is where that tension shows up most clearly.
Most Popular Narrative: 18% Undervalued
Advantest last closed at ¥34,930, while the most followed narrative anchors fair value at ¥42,685. This gap frames the whole AI tester debate around how much of the future is already in the price.
Expansion of software and ecosystem offerings such as SmarTest 8, the SiConic environment including the new DFT Engineering workflow, and AI enabled data infrastructure for the V93000, alongside partnerships such as the OpenLight silicon photonics collaboration, can increase Advantest’s test content per device and mix of higher margin solutions, supporting revenue and net margin over time.
See why 17 investors see Advantest as 18% undervalued.
Result: Fair Value of ¥42,685 (UNDERVALUED)
Still, the Advantest story can change quickly if AI driven tester demand softens or if new memory platforms trigger a sharper reset in margins and utilisation.
Find out about the key risks to this Advantest narrative.
Another View: Advantest Through The P/E Lens
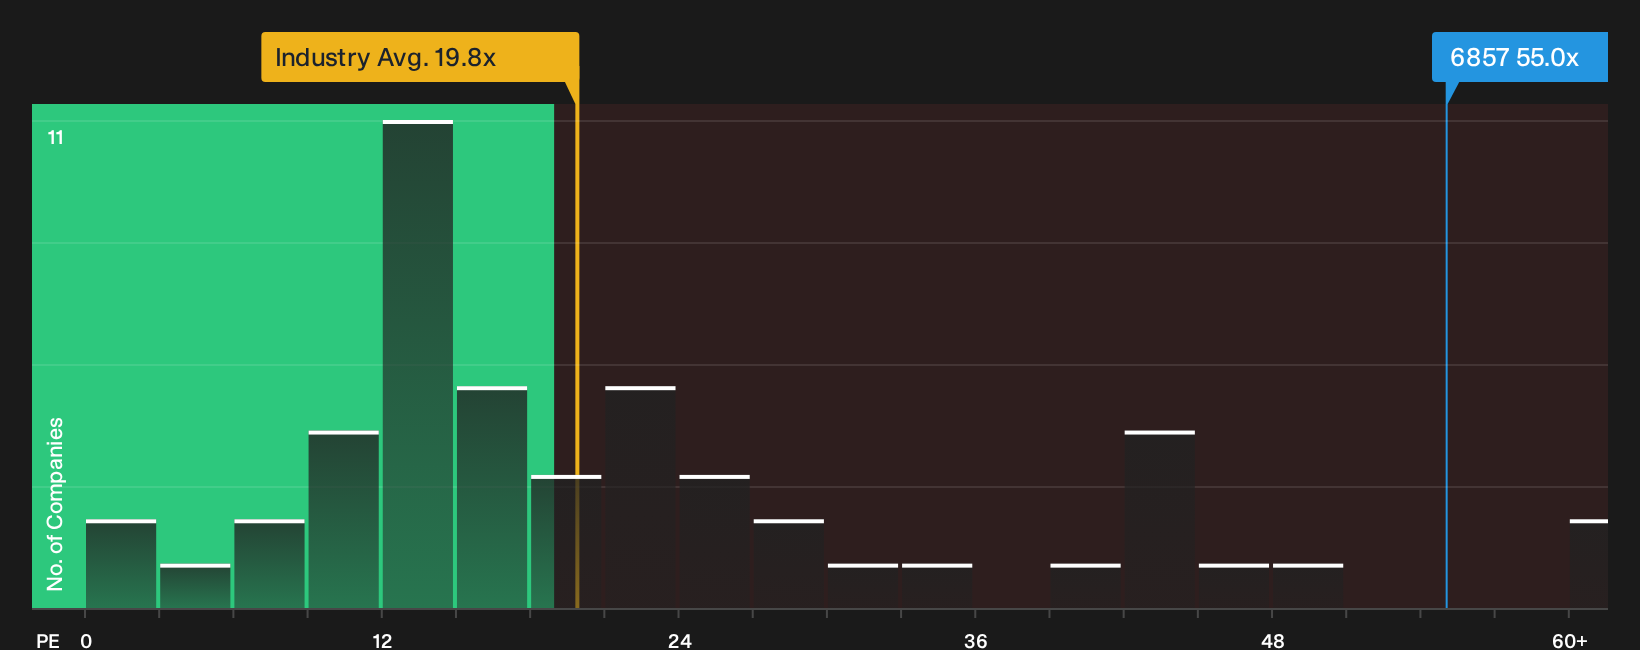
On the narrative fair value, Advantest screens 18.2% undervalued at ¥42,685. Yet the P/E picture pushes back. The shares trade on 55x earnings, compared with a 36.5x peer average, a 19.8x sector level, and a fair ratio of 38.6x that the market could move toward.
This richer multiple raises a practical question for investors. Is the higher price simply paying up for quality and AI exposure, or is it narrowing the room for error if growth or margins fall short, even slightly, of current expectations?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Advantest’s valuation can create plenty of noise. Move quickly, review the full data for yourself, and weigh both the upside potential and the risk signals across the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Advantest?
If Advantest has sharpened your focus on where capital can work harder, do not stop here. Fresh opportunities often sit just one screener away.
- Target reliable compounders by reviewing companies on the 14 high quality undervalued stocks that pair appealing prices with solid underlying fundamentals.
- Strengthen your defence by scanning the 24 resilient stocks with low risk scores that highlights businesses with more resilient risk profiles.
- Spot tomorrow’s quiet winners early by checking the 72 high quality undiscovered gems before they move onto everyone else’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com