
Custom Truck One Source (CTOS) Updates Guidance As Fair Value Stays In Focus
Custom Truck One Source (CTOS) just put fresh numbers on the table, with third quarter 2026 results and new full year guidance giving investors an updated read on sales, earnings and future revenue expectations.
The recent update appears to have caught investors’ attention, with Custom Truck One Source’s 7 day share price return of 15.19% and year to date share price return of 85.69% indicating strong positive momentum, supported by a 1 year total shareholder return of 78.31%.
Scan beyond Custom Truck One Source and line up other infrastructure linked equipment players showing strong price and earnings momentum with our hand picked 44 power grid technology and infrastructure stocks
Custom Truck One Source is clearly winning more business and turning prior losses into profit, yet the share price has already run hard. Is the current valuation still giving you enough compensation for the risk?
Most Popular Narrative: 19% Undervalued
Analysts following Custom Truck One Source put fair value around $13.33, compared with the recent $10.77 close. The narrative therefore leans toward a discount that still needs testing against the underlying assumptions.
Sustained and growing demand from electricity grid modernization and maintenance, fueled by increasing electricity usage and multi-year utility infrastructure upgrades, is driving recurring rental revenue and supporting long-term top-line growth. Legislative tailwinds, such as the federal bonus depreciation provision, are incentivizing capital spending by smaller and mid-sized customers. This should accelerate equipment purchases and bolster TES segment revenues and margins.
See why 4 investors see Custom Truck One Source as 19% undervalued.
Result: Fair Value of $13.33 (UNDERVALUED)
Still, high net leverage around 4.66x and pressure on TES and ERS gross margins could quickly challenge the Custom Truck One Source undervaluation story.
Find out about the key risks to this Custom Truck One Source narrative.
Another View: Custom Truck One Source Through Earnings Ratios
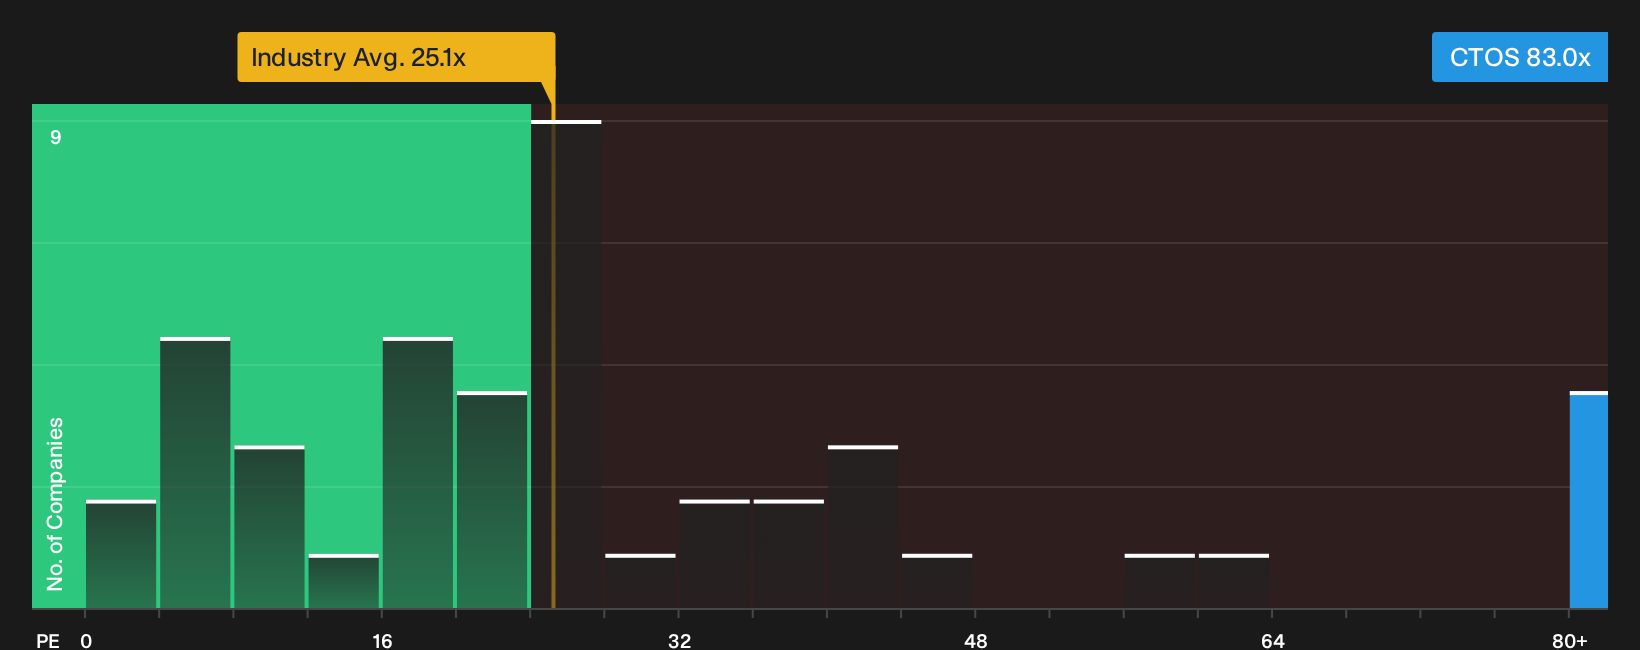
The discounted cash flow work points to Custom Truck One Source trading below an estimated fair value, yet the earnings multiples tell a tighter story. The current P/E of 83x looks steep next to the US Trade Distributors sector on 25.1x and a fair ratio of 39.2x. That gap suggests investors are paying a rich price for each dollar of profit, so how comfortable are you with that premium if sentiment cools?
To see how those earnings-based ratios stack up and where the fair ratio might pull pricing over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this are exactly when you want to get hands on with the numbers and pressure test Custom Truck One Source for yourself. If you want a concise view of both the upside and the concerns before making a call, start with the 4 key rewards and 2 important warning signs
Looking for more ideas beyond Custom Truck One Source?
If Custom Truck One Source sharpened your focus today, do not stop there. Broader opportunity often sits just a few targeted filters away on the Simply Wall St Screener.
- Target potential upside across quality businesses trading below their estimated worth by scanning a curated 26 high quality undervalued stocks.
- Lock in income ideas that aim for durability and yield by zeroing in on a hand picked 6 dividend fortresses.
- Prioritise resilience by filtering for companies with strong finances using our focused list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com