
XPO (XPO) Could Be 19% Undervalued Following Its Q3 Earnings Setup
XPO (XPO) heads into its Q3 earnings report tomorrow, with investor attention centered on expected 12.8% year on year revenue growth and largely steady forecasts that frame sentiment around the freight carrier.
The share price has eased in the days leading into the announcement, with a 1-day share price return of 3.32% down and a 7-day share price return of 3.59% down. However, XPO still carries a year-to-date share price return of 30.91% and a 1-year total shareholder return of 45.64%, indicating that longer term momentum has so far outweighed the recent pullback.
Scan how XPO compares with other freight and logistics plays by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
XPO has built a sizable freight operation across North America and Europe, and the share price run over the past year reflects that story. After the recent pullback, the key issue is whether that story still lines up with the current valuation.
Most Popular Narrative: 19% Undervalued
Against XPO's last close of $181.69, the most followed narrative pegs fair value near $225. This frames the stock as trading below that estimate while earnings forecasts and cash flow expectations remain central to the story.
The main factor that has to go right is that XPO continues to convert higher productivity, tighter LTL capacity, and a richer mix of local and premium shipments into sustained free cash flow generation and balance sheet strength.
The current valuation suggests that the market has not fully priced in the view that XPO is undervalued relative to its record profitability, rising free cash flow, and improving leverage profile.
See why 12 investors see XPO as 19% undervalued.
Result: Fair Value of $225.04 (UNDERVALUED)
Still, the narrative around XPO could be tested if freight volumes soften, or if rising labor and operating costs outpace the productivity gains analysts are counting on.
Find out about the key risks to this XPO narrative.
Another Look At XPO Using Market Multiples
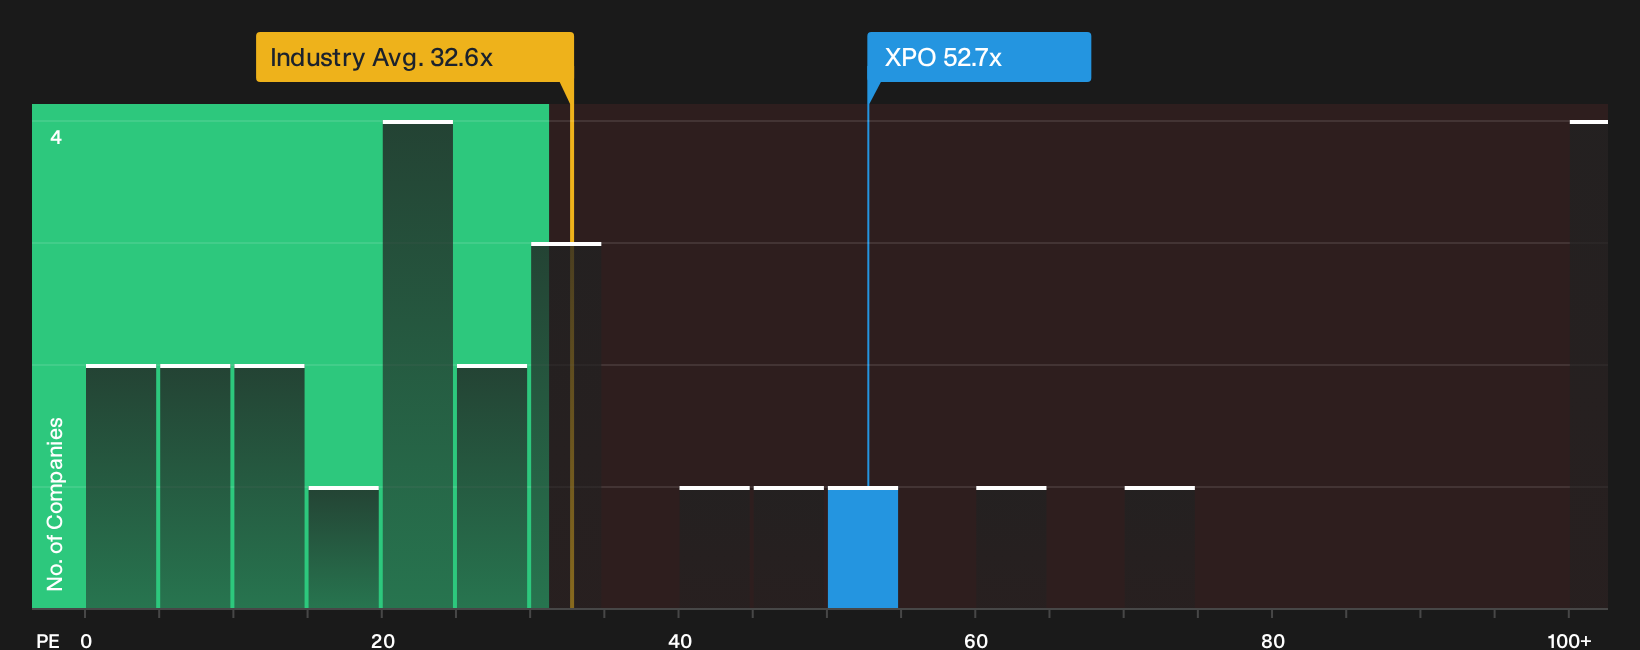
The story so far casts XPO as undervalued against fair value estimates and analyst targets. Market pricing tells a tougher story. The stock trades on a P/E of 52.7x, while the US Transportation industry sits at 32.6x and peers average 26.7x. Against a fair ratio of 21.9x, that gap points to meaningful valuation risk if sentiment cools.
For a closer read on what the numbers imply for this kind of pricing, and how much conviction you want to place on XPO sustaining a premium, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around XPO feels familiar, treat it as a prompt to review the underlying data and decide where you stand. Then weigh both sides of the story by checking 3 key rewards and 2 important warning signs.
Looking for more XPO-sized investment ideas?
If the XPO story has you thinking more carefully about price, quality, and risk, broaden your watchlist with a few focused sets of opportunities investors often overlook.
- Target resilience first and hunt for 32 resilient stocks with low risk scores that keep risk scores contained while still leaving room for upside when conditions change.
- Zero in on value and review 26 high quality undervalued stocks where quality fundamentals and pricing occasionally fall out of sync.
- Get ahead of the crowd and scan 19 high quality undiscovered gems before attention and liquidity start to catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com