
Free Cash Flow Outlook Has Anritsu Stock Looking Undervalued
- Anritsu has recently been reassessed by the market after analysis of its projected future free cash flow, which has drawn attention to a potential disconnect between the current share price and the value implied by its expected cash generation.
- The fresh focus on Anritsu’s underlying cash flow outlook reflects how investors are considering the company’s long range business performance more heavily than short term trading movements.
- This article examines how Anritsu’s investment narrative is being reshaped by renewed attention to future free cash flow and potential undervaluation.
Scan beyond Anritsu and compare its free cash flow story with a curated set of quality opportunities in our 14 high quality undervalued stocks.
What Is Anritsu's Investment Narrative?
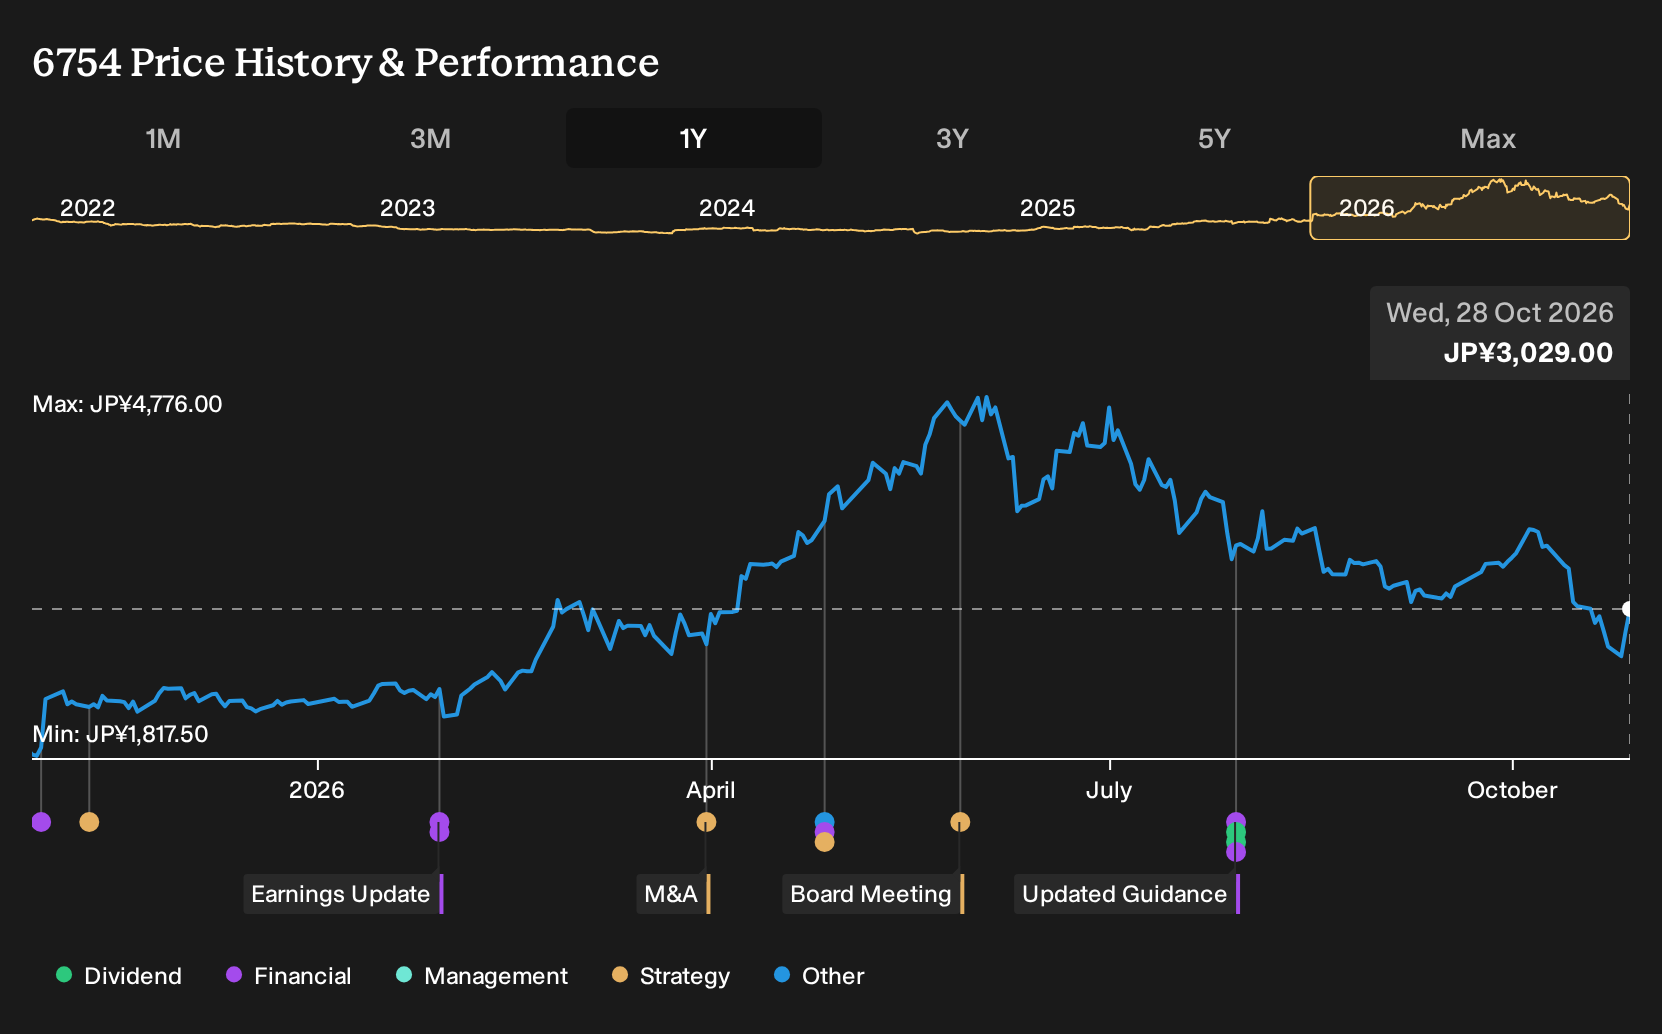
To own Anritsu, you need to believe its measurement gear, from 5G and wireless testers to optical instruments and product quality systems, can keep generating solid free cash flow across communications and electronics cycles. The recent focus on discounted cash flow value simply shines a light on that operational question. Recent moves in the share price, including a 14.7% decline over 90 days, do not change the practical work in front of management, which is converting a broad global footprint and ¥126,426 revenue base into consistent cash.
In the short term, the big swing factor is execution in higher margin test and measurement, where pricing power and order timing can make earnings lumpy. Earnings growth of 57.6% over the past year and an 11.4% net margin, up from 8.2%, suggest recent delivery has been strong. At the same time, investors need to weigh a 27x P/E, forecast earnings growth of 16.21% a year, capital needs in areas like 5G and 6G solutions, and a share price that has been more volatile than the broader JP market. The new free cash flow debate fits into all of this as a check on whether that mix of growth, volatility, and capital intensity still lines up with the current valuation.
That said, the one issue that could really upset the free cash flow story is ...
There's only one way to know the right time to buy, sell or hold Anritsu. Head to Simply Wall St's company report for the latest analysis of Anritsu's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Anritsu research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Anritsu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Anritsu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Anritsu?
If you want to stress test your view on Anritsu, compare it with other stocks that score well on fundamentals and risk using the Simply Wall St Screener. You can filter by quality, balance sheet strength, dividend profile, and more to build a watchlist that fits your own approach.
- For investors who want potential mispricings on their radar, start with a focused set of companies that screen as attractively priced using the 14 high quality undervalued stocks.
- If capital preservation and resilience matter most to you, narrow the field to businesses that pass strict financial health checks with our list of solid balance sheet and fundamentals (23 results).
- To uncover opportunities that may not be widely followed yet, scan a curated group of lesser known but fundamentally strong stocks through the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com