
How High CO2 Waste Incineration Will Impact Kanadevia Stock Investors
- Kanadevia Corporation announced that it will start what it describes as the world's first high CO2 concentration waste incineration demonstration in the Waste to Energy sector at Tokyo's Shinagawa Incineration Plant in November 2026, using a pilot facility that processes 2 tons of waste per day and targets CO2 recovery rates above 90%.
- The project aims to raise flue gas CO2 concentration to about 30% to 60% and reduce the flue gas volume sent to capture equipment to a fraction of conventional systems, which could influence how future Waste to Energy plants are designed for carbon circularity, capital allocation and site footprint.
- We will now look at how Kanadevia's investment narrative could be affected by its high concentration CO2 capture trial in Tokyo.
Scan beyond Kanadevia and this Tokyo trial by lining up other potential carbon and infrastructure beneficiaries using the hand picked 44 power grid technology and infrastructure stocks that could benefit as grids adapt to higher electrification and Waste to Energy demand.
Kanadevia Investment Narrative Recap
To own Kanadevia, you need to buy into a fairly specific story. The business is trying to turn engineering depth in waste, machinery and decarbonization into steadier earnings, while dealing with thin net margins of 2.2% and profit pressure from past one off items and project issues. The Tokyo CO2 trial fits that effort, but it does not remove those near term execution questions.
Right now, the key short term swing factor is whether project work, including low carbon contracts, converts into clean, on budget revenue that supports the forecast earnings recovery. The biggest live risk is still further charges or cancellations on complex infrastructure jobs, which would keep returns and free cash flow tight and leave the dividend uncovered.
The high CO2 concentration Waste to Energy demonstration in Shinagawa is the announcement that most directly matters here. It sits inside Kanadevia’s Environment and Decarbonization activities, where the group is trying to build a pipeline that is less exposed to straightforward construction risk and more anchored in proprietary systems tied to carbon capture and circularity.
Set against the Oman green hydrogen collaboration, the Tokyo pilot gives you two different but related catalysts to watch. One is technology acceptance in Waste to Energy, including whether CO2 capture rates near 90% can be sustained at pilot scale. The other is whether this engineering track record helps Kanadevia win more decarbonization projects without repeating past cost overruns or compliance setbacks.
What The Consensus Kanadevia Numbers Assume
Kanadevia's narrative projects revenues of ¥752.2b and earnings of ¥29.5b by 2029. That profile lines up with analyst assumptions of 4.4% yearly revenue growth and an earnings increase of about ¥14.6b from earnings today of ¥14.9b.
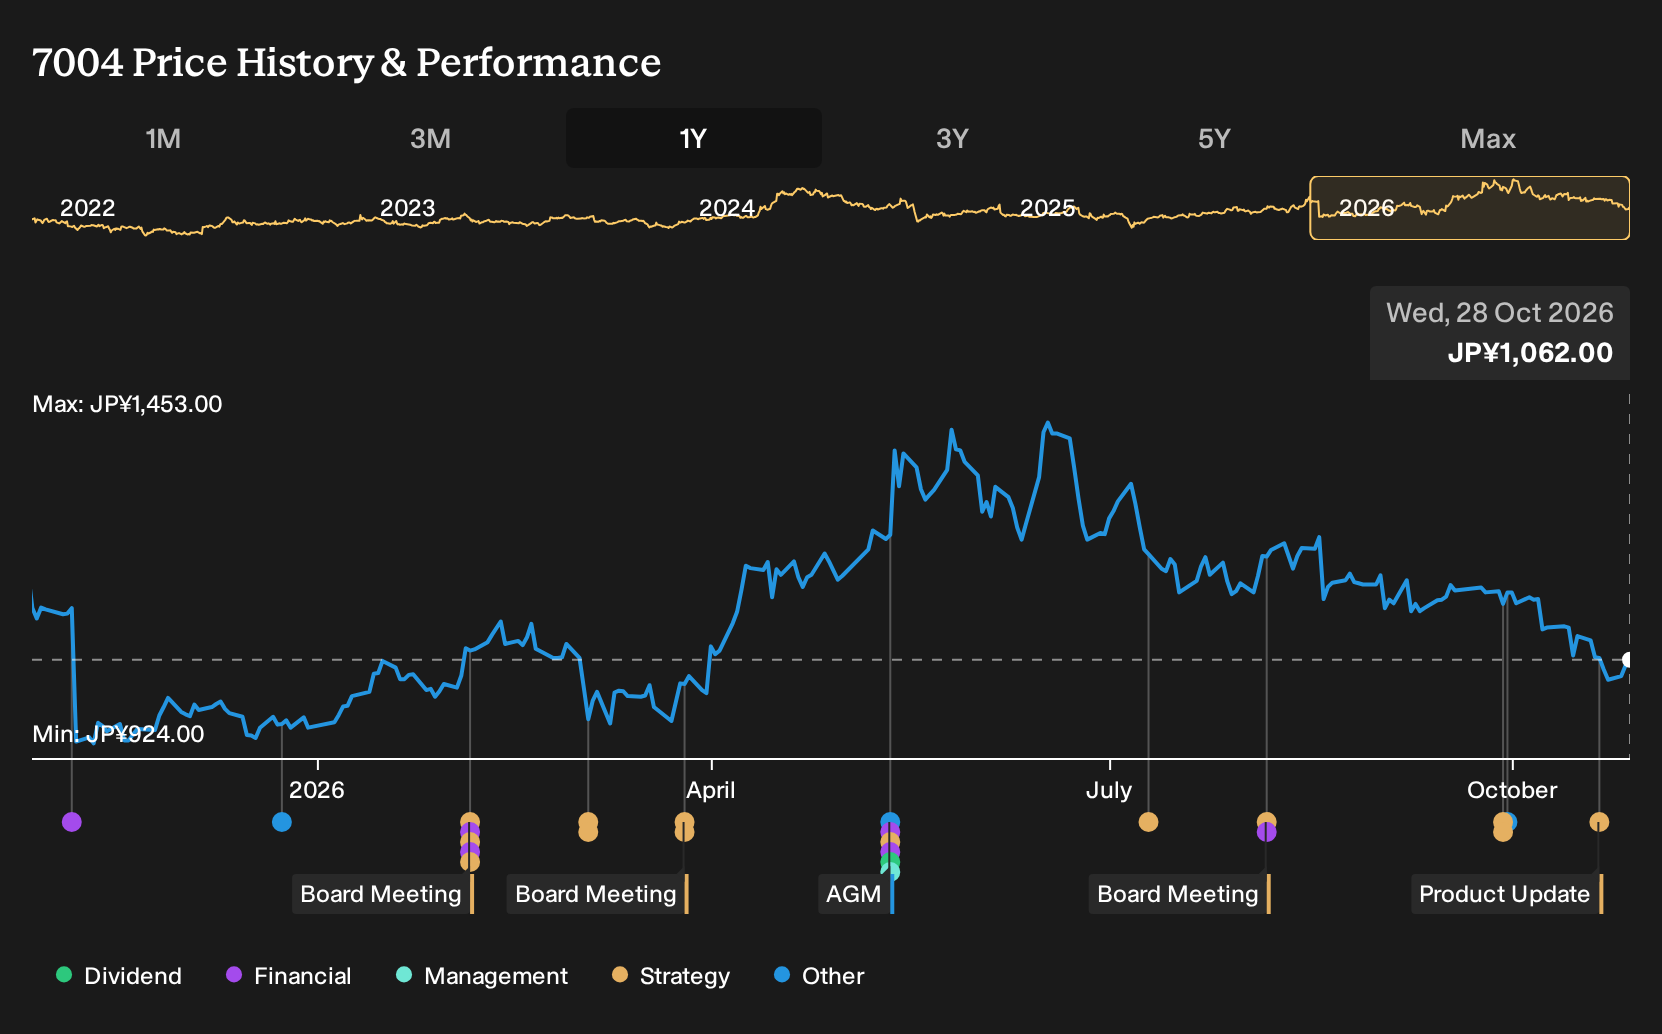
Uncover why Kanadevia's fair value indicates a 22% potential upside to its current price, which could narrow quickly if Kanadevia's Tokyo trial reshapes sentiment.
Exploring Other Perspectives
Fair value estimates on Kanadevia from the Simply Wall St Community span roughly ¥1,300 to about ¥1,824, based on only 2 individual models, so opinions already stretch quite wide. When you also consider the Oman low carbon projects and the Tokyo CO2 trial, it becomes clear why future contract outcomes could push these views even further apart. Readers should treat this as a prompt to explore several alternative viewpoints rather than anchor on any single number.
Explore another Kanadevia fair value estimate, including one that suggests it could be worth just ¥1300!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis and research.
- A great starting point for your Kanadevia research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Kanadevia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it straightforward to review Kanadevia's overall financial position at a glance.
Looking for more investment ideas beyond Kanadevia?
Once you have a view on Kanadevia, it can help to line it up against other potential opportunities using the Simply Wall St Screener. That way you see where this stock fits alongside different return profiles, balance sheet quality levels and income characteristics.
- For investors who want potential mispricing combined with quality fundamentals, compare Kanadevia against a curated set of 14 high quality undervalued stocks that already pass strict balance sheet and cash flow checks.
- If capital preservation is high on your list, contrast its risk profile with a group of 24 resilient stocks with low risk scores that screen well on volatility, leverage and earnings stability.
- When you prefer sturdier financial foundations, weigh Kanadevia next to a list of solid balance sheet and fundamentals (23 results) to see how its debt, liquidity and asset base stack up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com