
Oil Discovery Could Be A Game Changer For BW Energy Stock (OB:BWE)
- BW Energy reported that the 10P1 and 10P2 appraisal wells in the Dussafu field in Gabon found commercial oil volumes, with combined recoverable resources estimated at 8 to 9 million barrels gross. The company plans to develop two additional production wells as part of the MaBoMo Phase 2 campaign.
- These Dussafu results give BW Energy a clearer queue of future projects. These range from new MaBoMo production wells to planned Bourdon and Tortue drilling, which could reshape how investors think about the long term production mix and project timing.
- The focus is now on how BW Energy's investment narrative evolves as new Dussafu appraisal success feeds into longer term production planning.
What Is BW Energy's Investment Narrative?
To own BW Energy, you need to believe the company can turn a growing project pipeline into reliable production while managing heavy capital needs and a geared balance sheet. The Dussafu appraisal success and the Kavango West 1X drilling restart both feed that story. They expand the set of potential producing assets, but also keep investment intensity high at a time when profit margins have compressed to 12.2% from 23.6% and returns on equity remain relatively low at 8.7%.
In the near term, the key swing factors are execution on MaBoMo Phase 2, timing and performance of future Dussafu and Bourdon wells, and what the Kavango flow tests actually show once results are released. Management is guiding to about 23 kbopd for 2026 after some wells were shut in, so operational uptime and cost control matter as much as growth projects. Forecasts point to fast revenue and earnings expansion, yet that only helps shareholders if BW Energy can fund this build out while handling its high level of debt and reliance on higher risk borrowing.
That said, the picture looks less straightforward once you factor in ...
There's only one way to know the right time to buy, sell or hold BW Energy. Head to Simply Wall St's company report for the latest analysis of BW Energy's Fair Value.
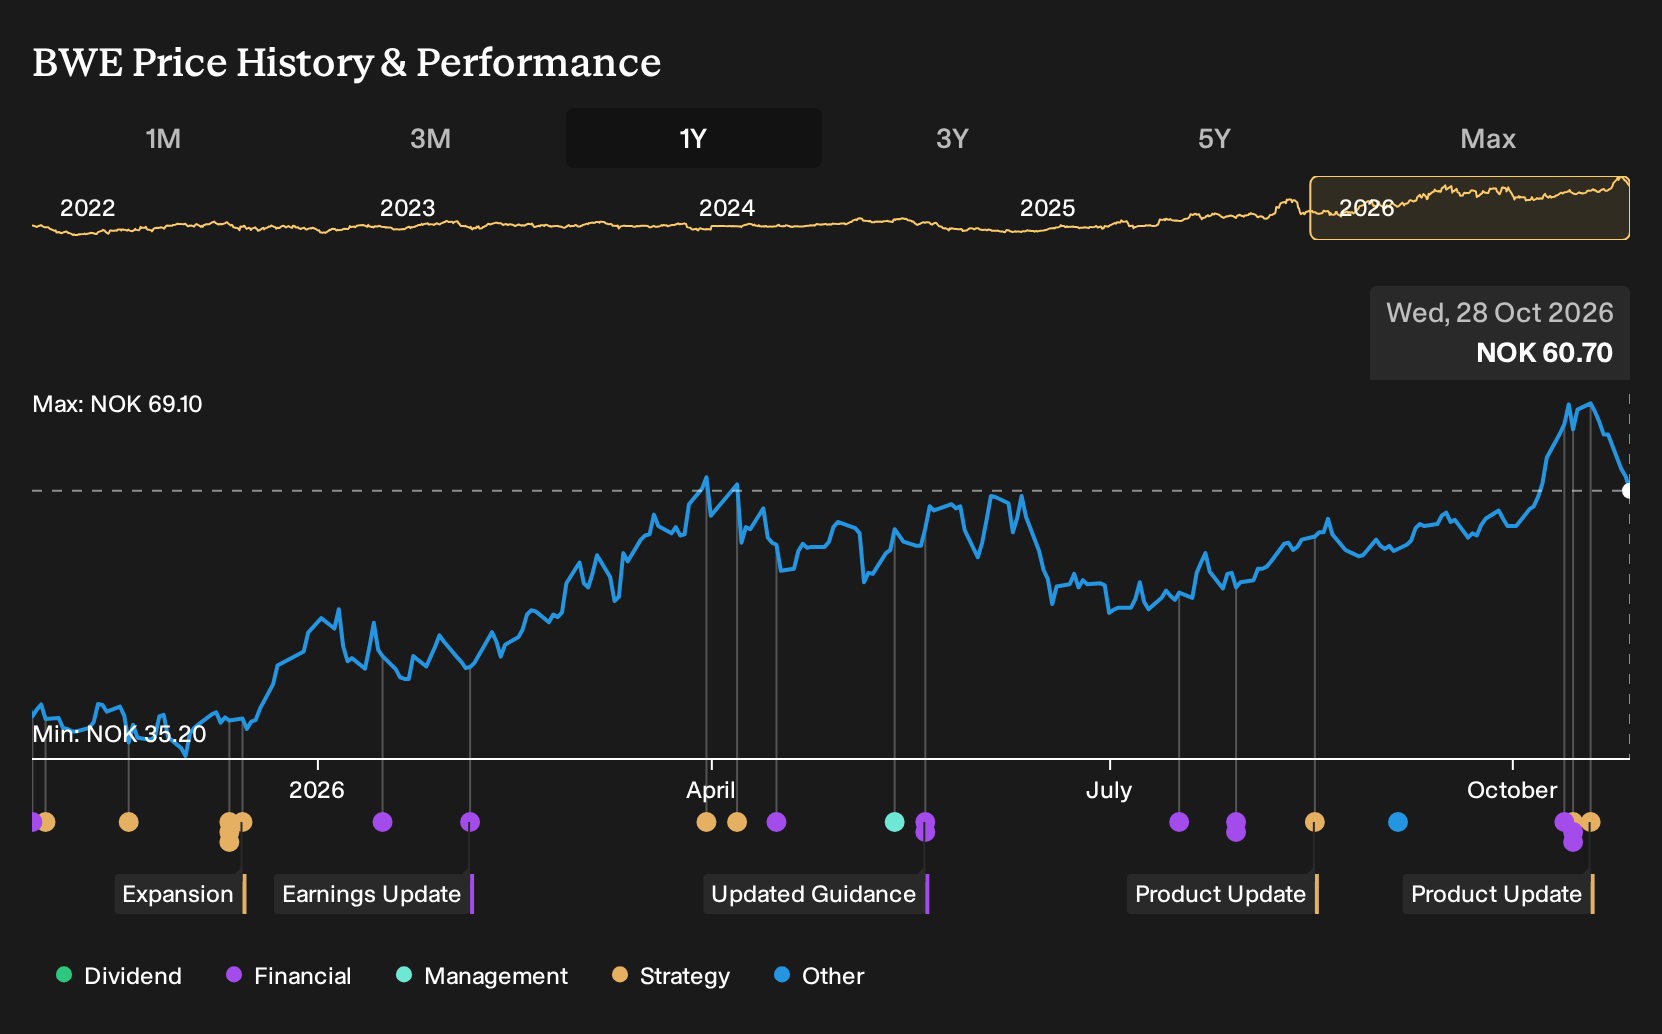
Exploring Other Perspectives
One area where the most optimistic analysts really diverge from the baseline is earnings potential. They were pencilling in revenue of about US$3.3b and earnings of US$1.3b by 2029 for BW Energy, compared with today’s US$99.9m. You should consider whether the recent Dussafu and Kavango drilling news shifts your own expectations closer to, or further from, that optimistic path.
Explore 3 other BW Energy fair value estimates, including one that suggests as much as 1166% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BW Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BW Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BW Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond BW Energy?
Once you have a view on BW Energy, it can help to compare it with companies that fit different risk, quality, and income profiles using the Simply Wall St Screener.
- For investors hunting for stability and strong finances, start with a list of solid balance sheet and fundamentals (203 results) that can handle pressure without relying on fragile funding.
- If you care most about resilience and controlled downside, consider a 228 resilient stocks with low risk scores that scores well on volatility and fundamental risk checks.
- Those looking for quality that is not yet widely followed can review a 609 high quality undiscovered gems that combines solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com