
Is Retail Leadership Change Altering The Investment Case For Marzetti (MZTI)?
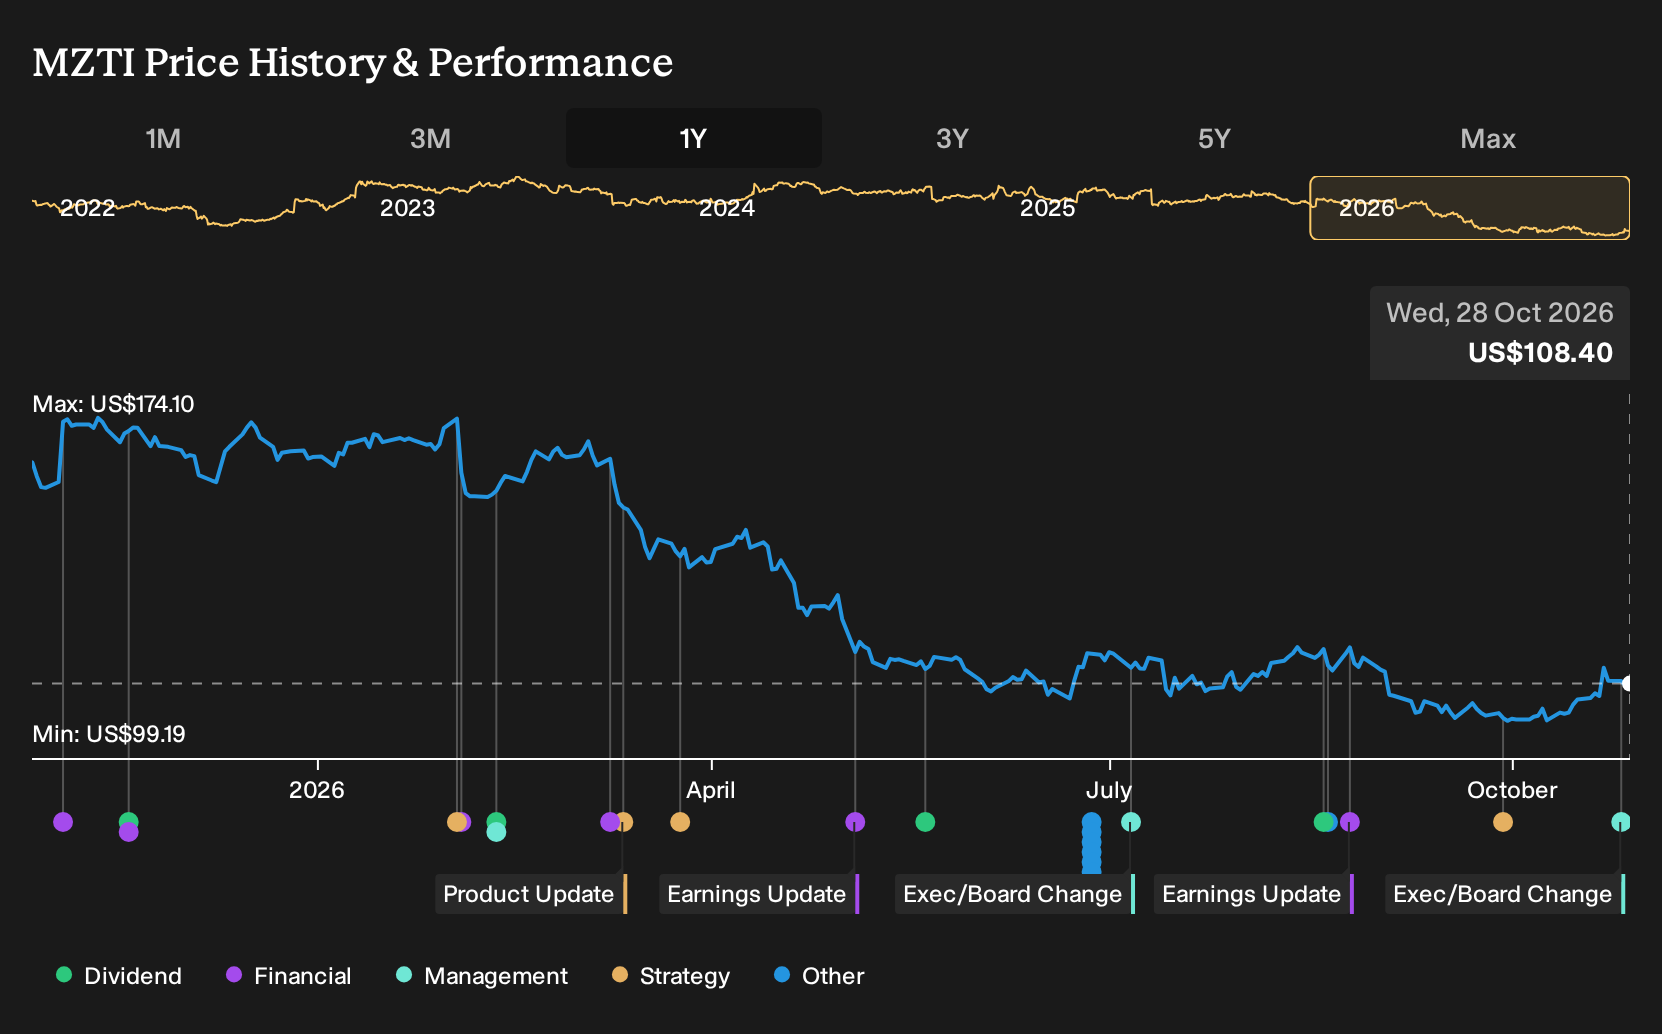
- Marzetti recently named former Wingstop executive Mark Christenson as President of its Retail business and promoted Rene Luichinger to Chief Customer Officer, placing both in charge of retail brand, growth planning and customer strategy.
- The appointments concentrate long consumer packaged goods and retail sales experience at the top of Marzetti’s retail unit, which could reshape how the business manages product mix, promotions and retailer relationships.
- We will now examine how Marzetti’s investment narrative could be influenced by Christenson’s appointment to lead its retail portfolio.
Marzetti Investment Narrative Recap
To own Marzetti you need to be comfortable with a steady, branded food producer that leans on licensed products, retail dressings and frozen bakery for volume. The near term story still hinges on whether retail demand for these products can offset consumer shifts toward fresher, clean label options and rising pressure from private label competitors.
The key short term swing factor is execution on product mix and promotions in the Retail segment, which Christenson now oversees. The biggest risk remains margin pressure from input cost volatility and retailer consolidation. This leadership change looks operationally relevant, but not a single, stand alone catalyst by itself.
The most relevant recent development is Marzetti’s push on newly licensed and branded items such as the Texas Roadhouse dinner rolls rollout. That initiative directly meets the brief Christenson has been given, since it sits at the intersection of brand building, premium price points and volume in the grocery aisle.
If that type of licensed product can sustain household penetration and repeat purchase, it supports analysts’ expectations for modest revenue growth and stable earnings. If it stalls, the firm leans harder on cost savings and supply chain efficiency to protect margins, which increases the importance of disciplined execution from the refreshed retail leadership team.
Marzetti's current analyst script points to US$2.1b in revenue and US$197.3m in earnings by 2029, based on assumed yearly top line growth of 2.1% and an earnings increase of about US$5.7m from US$191.6m today.
Uncover why Marzetti's fair value indicates a 35% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternate view on Marzetti fixates on licensing risk rather than consumer trends. The most cautious analysts worry that heavy reliance on partners like Texas Roadhouse could make earnings more fragile. Before this leadership news, they were penciling in revenue of about US$2.1b and earnings of roughly US$192.4m by 2029. That is a more muted script than the consensus. It could shift again as investors reassess these forecasts in light of the new retail leadership team.
Explore 2 other Marzetti fair value estimates, including one that suggests it could be worth just $138.54!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marzetti research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Marzetti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marzetti's overall financial health at a glance.
Looking for more Marzetti-sized investment ideas?
If you want to stress test your thinking beyond Marzetti, use the Simply Wall St Screener to line up other companies that fit the kind of quality, income, or resilience profile you want in your portfolio.
- For investors who like mispriced quality, scan a curated set of potential value ideas through 26 high quality undervalued stocks.
- If balance sheet strength is non negotiable for you, focus your shortlist using a list of solid balance sheet and fundamentals (24 results).
- For those who care about consistency more than excitement, filter for steadier profiles with a 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com