
3 British Dividend Stocks With Yield Over 3%
Soaring energy prices in the UK are squeezing household budgets and lifting inflation forecasts, which makes reliable cash payouts from British dividend stocks feel more valuable. Regular income can help soften higher bills and unpredictable interest rate moves. This article looks at three high-yield UK companies that currently pay more than 3%, with dividends that this screen flags as covered, growing and relatively steady.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher-yielding dividend payers with covered, growing, and steady payouts. However, if you want the standouts, these 4 dividend aristocrats stocks are the most outstanding.
Man Group (LSE:EMG)
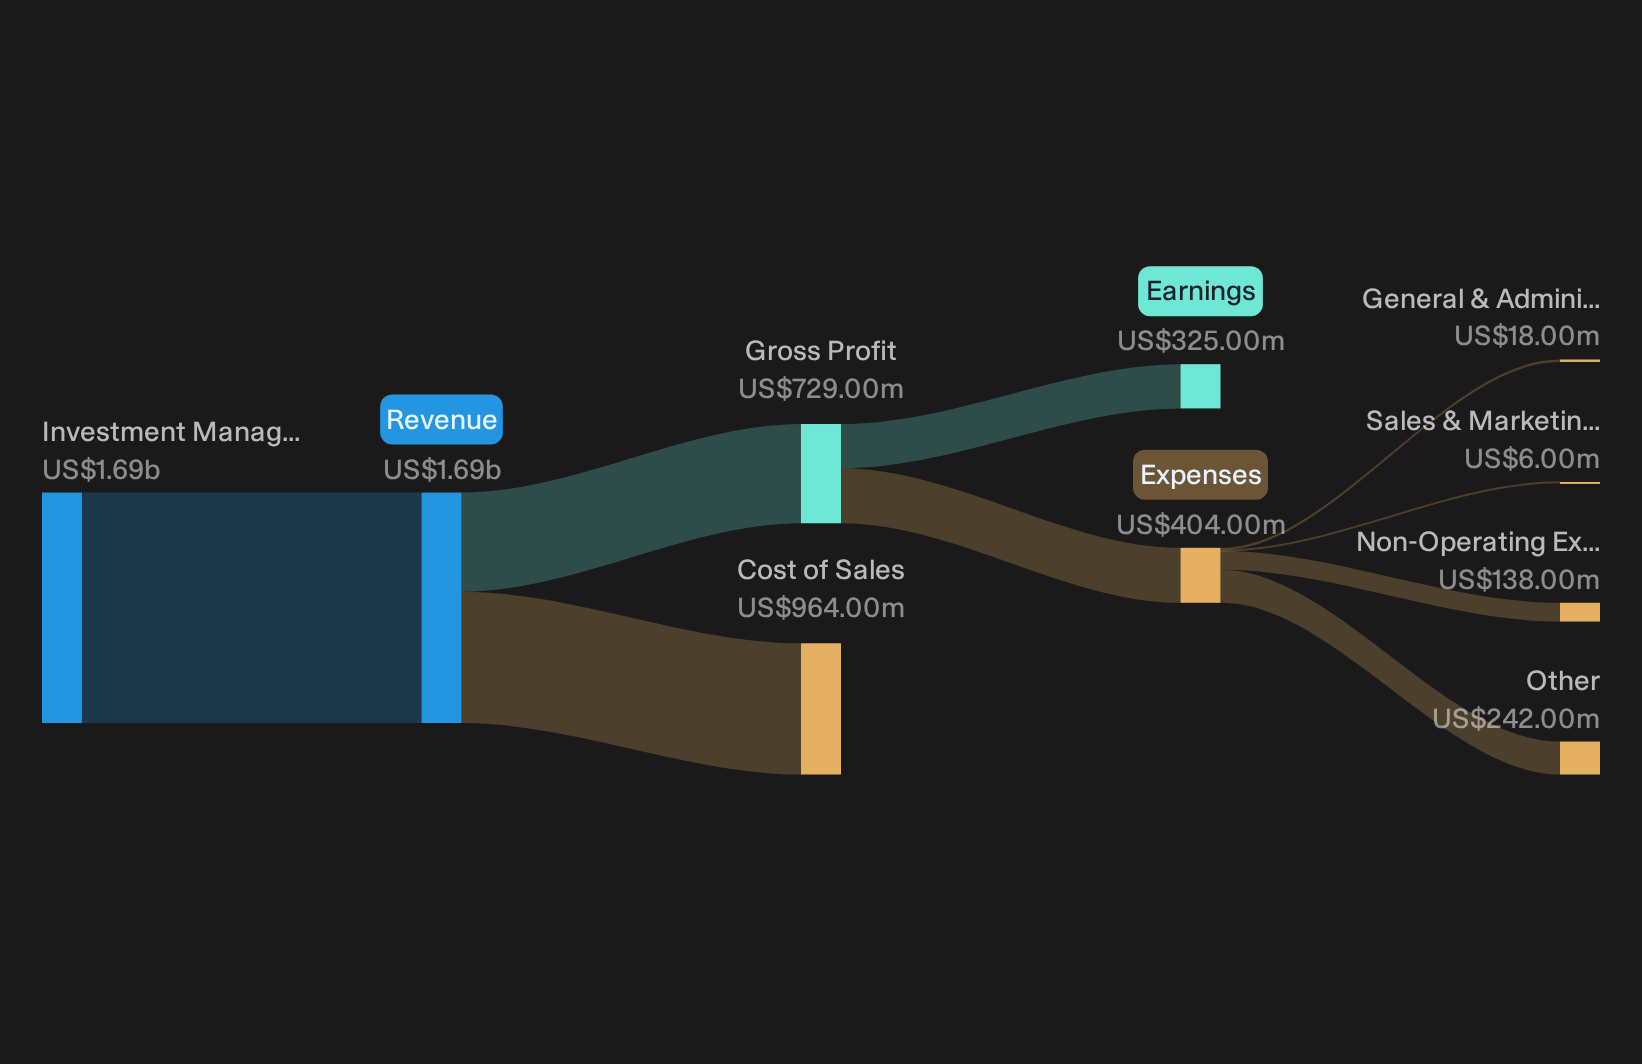
Man Group is an investment manager that runs quantitative, multi manager and discretionary funds across several asset classes. It earns $1.69b from its Investment Management Business, and with a market value of about £3.69b it converts these fee streams into regular dividends.
For income focused investors, Man Group offers something powerful. The business earns recurring fees from a broad set of investment strategies, which provides a relatively steady cash pool that can support a covered dividend and room for growth when conditions cooperate.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026 plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
The real test for that income story could come from how one unresolved pressure influences future fee margins and overall earnings quality.
That unresolved pressure sits at the heart of the full narrative for Man Group, where the full story weighs fee resilience against the risk of margins stalling or quietly accelerating.
Grafton Group (LSE:GFTU)
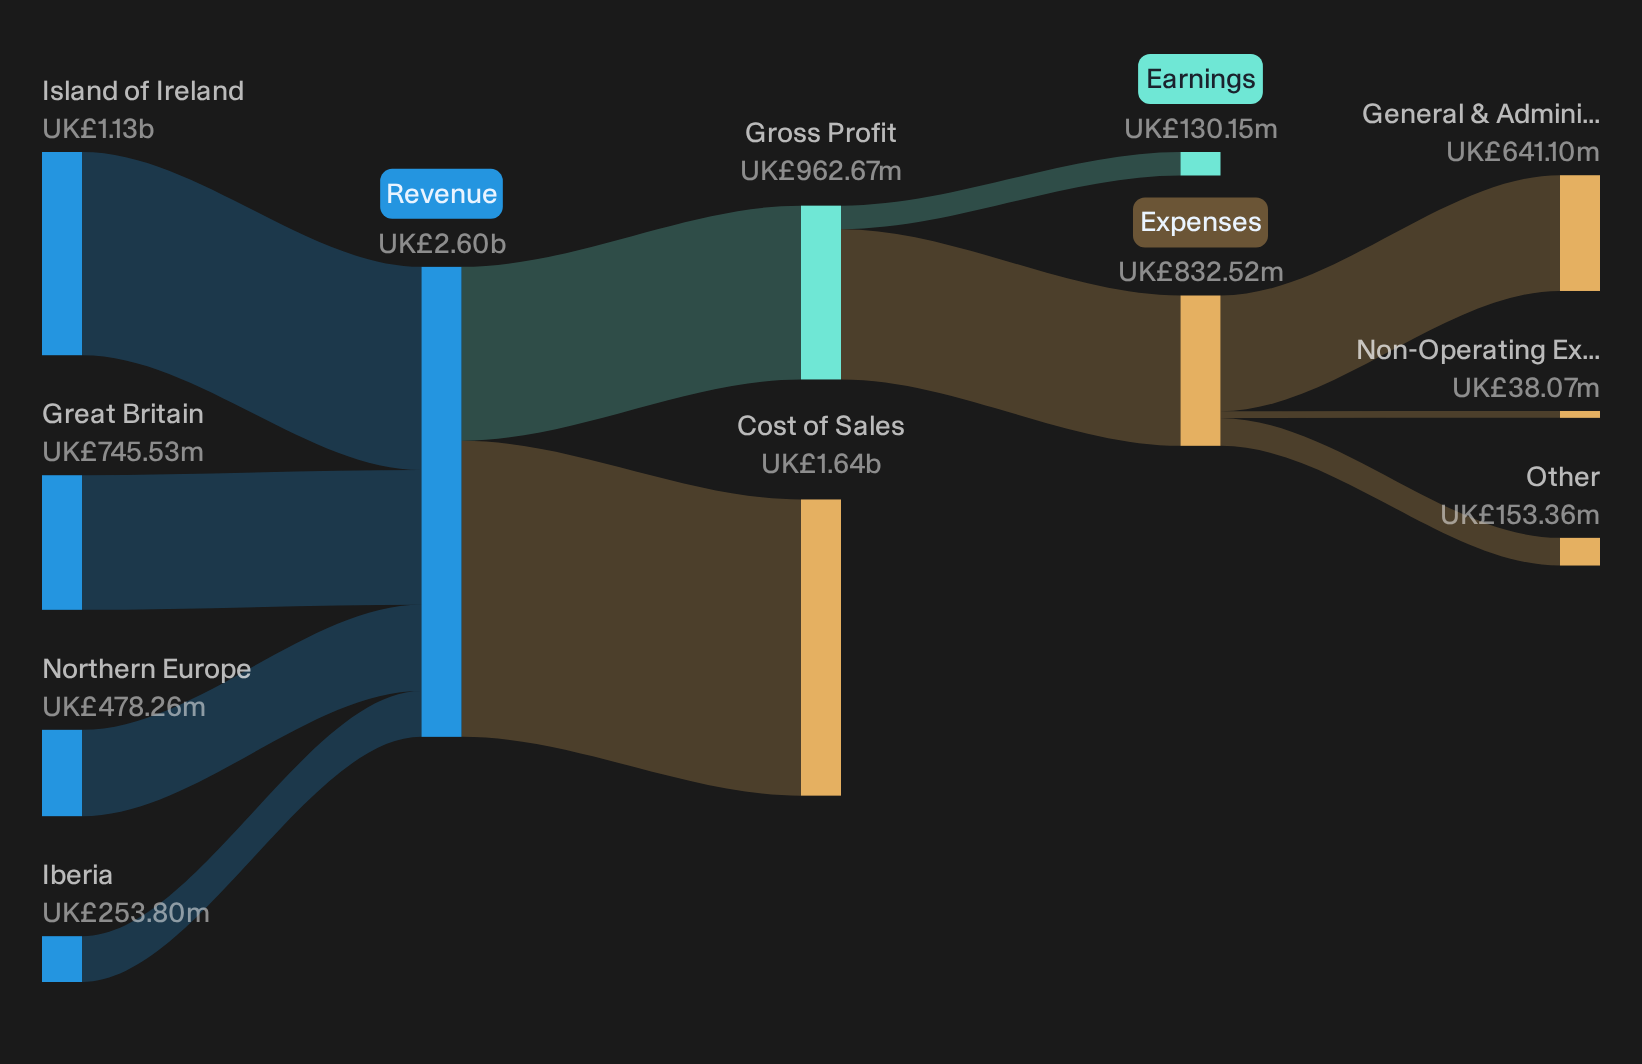
Grafton Group is a Dublin headquartered building materials distributor and DIY retailer. Cash generative outlets like Selco, Leyland SDM and Woodie’s underpin the 3%+ yield, while Iberia, Great Britain, Northern Europe and Ireland contribute about £254 million, £746 million, £478 million and £1.1 billion of revenue respectively on a group worth roughly £1.8 billion.
Grafton Group offers a different angle on dependable dividends. Its contractor focused merchant branches and DIY outlets generate cash that helps fund a covered 3%+ yield and gives the Iberian expansion real weight in that income story.
"Grafton Group's continued build out of its Iberian HVAC platform, now including both Salvador Escoda and Mercaluz with around 120 branches and a shared focus on own brand products, allows further branch openings, new customer channels and exports to support higher revenue and EBITA margins in the region."
What matters next for that payout is how one less visible pressure shapes the balance between rising Iberian earnings and softer profitability in Great Britain.
That tug of war is exactly what the full narrative for Grafton Group unpacks, showing where Iberian momentum could be masking stalled trends or setting up an overlooked earnings reset.
HSBC Holdings (LSE:HSBA)
HSBC Holdings is a global banking group with deep retail and wealth operations in Hong Kong and the UK, where steady deposit, mortgage and fee income help support its role in this 3%+ dividend powerhouse screen. The group is large, with a market value of about £221.9b.
HSBC Holdings leans on those retail deposits and wealth franchises, especially in Asia, to produce recurring earnings that can underpin a covered dividend profile investors can plan around.
"Intensifying investment in Asian wealth management and private banking remains central, with over 1 trillion US dollars of Asian wealth balances and strong net new money in Hong Kong and India."
What really matters now is how one less visible pressure shapes the balance between that wealth driven income engine and future payout headroom.
That payout headroom question is exactly what the full narrative for HSBC Holdings tackles, highlighting where HSBC Holdings’ wealth engine could be quietly accelerating income or masking emerging pressure.

Seeking Fresh Alternatives Beyond Dividends
Fresh ideas move first. Once a theme gains momentum, entry points can start flying away while attention chases performance. Scan these under the radar lists before the crowd and act now.
- Spot resilient payers that keep portfolios steadier when markets swing and track a curated 4 dividend fortresses list before yields get crowded by late money.
- Target growth stories tied to real-world infrastructure shifts and review a focused group of 44 power grid technology and infrastructure stocks positioned around grid upgrades and electrification while prices still look reasonable.
- Back structural demand for critical materials and assess a condensed basket of 16 top copper producer stocks aligned with long term electrification trends before valuations reflect full optimism.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com