
Soitec (ENXTPA:SOI) Could Be 57% Below Fair Value Following AI Spending Questions
Recent commentary around Soitec (ENXTPA:SOI) is zeroing in on one issue. Investors are questioning how sustainable AI infrastructure spending really is, and whether that supports the company’s current premium price-to-sales valuation.
Over the past year, Soitec’s share price has surged, with a year-to-date share price return of about 395% and a 1-year total shareholder return of 197%, even though the 30-day share price return is down 13.64% and longer term 3 and 5-year total shareholder returns remain negative. Recent weakness over the past month sits alongside a 17.86% 90-day share price gain, which suggests momentum has cooled in the short term as investors reassess how much premium they want to pay for AI exposed revenue while the stock trades around €123.10.
Compare Soitec’s premium AI story with other chip suppliers by scanning hand-picked 54 AI infrastructure stocks that are also tied to data centers and network buildouts.
After a move this steep, either Soitec’s rally has already banked most of the AI enthusiasm, or investors are still underestimating what they are paying for each euro of sales.
Most Popular Narrative: 57% Undervalued
Against Soitec’s last close of €123.10, the most followed narrative anchors on a fair value of €284.86, which frames today’s price as heavily discounted once optimistic AI and photonics assumptions are incorporated using an 11.68% discount rate.
Acceleration in Soitec's Photonics-SOI activity, with revenue already above $100m, growth above 30% in the most recent full year and an expectation for FY27 revenue to more than double again, points to a larger AI data center optical interconnect business than most models currently assume. This could add meaningful upside to revenue and operating leverage if multi year customer commitments continue to ramp.
See why 6 investors see Soitec as 57% undervalued.
Result: Fair Value of €284.86 (UNDERVALUED)
Still, the bullish Soitec narrative hinges on mobile and automotive demand stabilising, and on new platforms avoiding further impairments after the SmartSiC reset.
Find out about the key risks to this Soitec narrative.
Another View: Soitec Looks Expensive On Sales
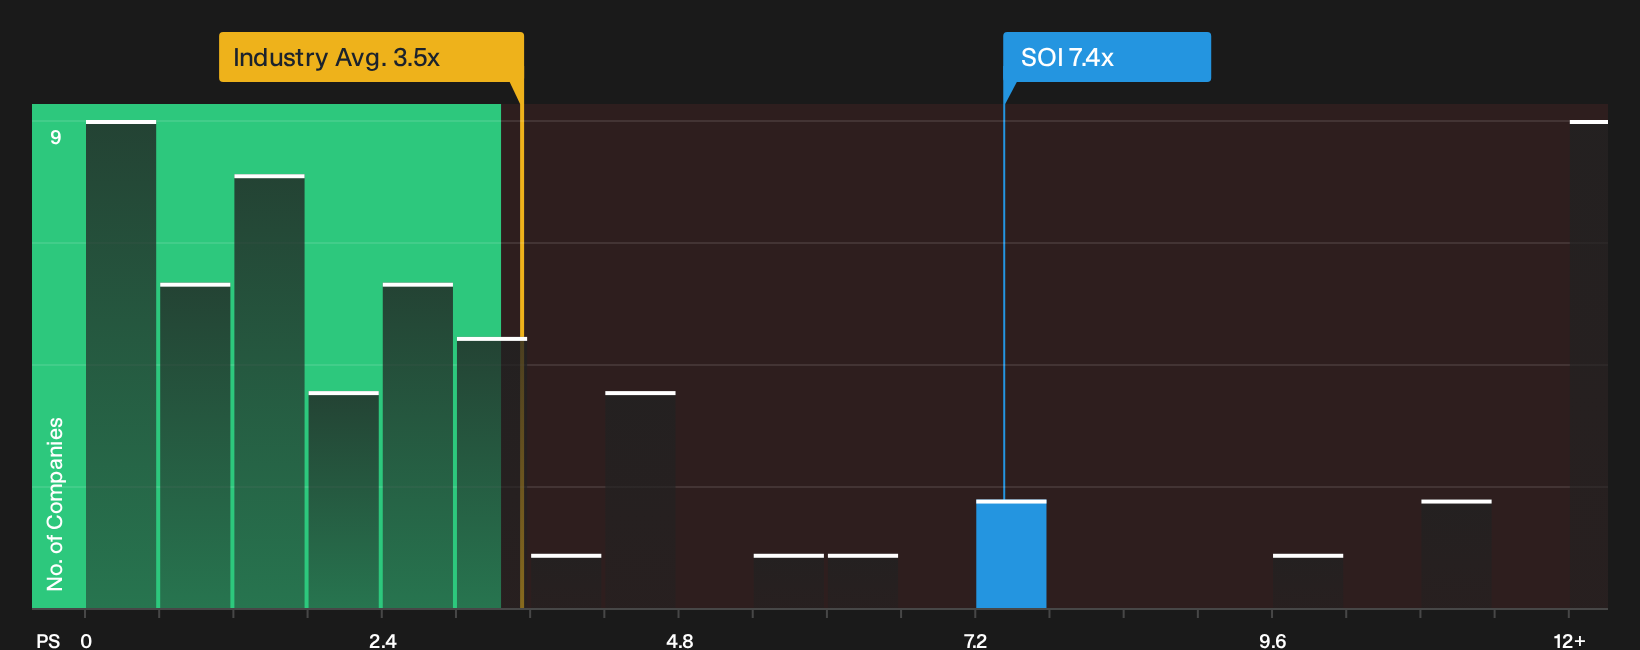
On the bullish narrative, Soitec screens as heavily undervalued at a fair value of €284.86. Yet the P/S ratio tells a different story. At 7.4x sales, the stock trades well above the European semiconductor group on 3.5x and peers on 4.3x, and also above a 5.4x fair ratio that the market could eventually lean toward. If sentiment cools, how comfortable are you paying such a premium for every euro of revenue?
To test how much that premium leaves on the table, or how much it could compress, it is worth checking what the numbers say in a more granular valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual sense of how Soitec stacks up against the wider sector on this metric, see the latest relative chart.
Next Steps
Sentiment around Soitec is split, which is exactly when fresh eyes matter most. Review the figures, weigh both sides and then check the 1 key reward and 1 important warning sign.
Looking for more Soitec sized opportunities?
If you stop at Soitec, you risk missing other ideas that fit your style. Let the Simply Wall Street Screener surface fresh candidates for your watchlist.
- Hunt for quality at a discount by reviewing 191 high quality undervalued stocks that pair solid fundamentals with more modest price tags.
- Prioritise resilience by scanning 228 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Spot future leaders early by checking 609 high quality undiscovered gems before wider attention catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com