
Is Power Corporation Of Canada (TSX:POW) Fully Valued Following Its Wealthsimple Investment?
Power Corporation of Canada (TSX:POW) is committing fresh capital to Wealthsimple, participating in a $425 million equity round that values the fintech at $13.8 billion and supports its product and technology expansion.
Recent trading has been strong for Power Corporation of Canada, with a 1-month share price return of 3.58% and a year to date share price gain of 34.58% taking the stock to CA$96.8. That move sits on top of a 1-year total shareholder return of 55.47% and a 3-year total shareholder return of about 23x, which signals that investors have been rewarding the group’s mix of traditional financial operations and higher growth fintech exposure such as Wealthsimple.
Spot similar wealth and fintech plays with strong momentum by scanning our hand picked 8 high quality undiscovered gems that share traits with Power Corporation of Canada's approach to backing Wealthsimple.After a near vertical run and a fresh Wealthsimple cheque, Power Corporation of Canada now trades only about 5% below the average analyst target while sitting at a small premium to one intrinsic value estimate. Is that caution or mispricing?
Price-to-Earnings of 23.1x: Is it justified?
Power Corporation of Canada is being valued at a P/E of 23.1x, which puts the current CA$96.8 share price on a richer footing than many insurance peers and suggests investors are paying a premium for each dollar of earnings.
The P/E ratio compares what the market is willing to pay per share to the business's earnings per share. For a diversified financial group like Power Corporation of Canada, which blends traditional insurance, asset management and fintech investments, this measure often reflects how much faith investors place in the durability and growth of those profits.
Here, the current P/E of 23.1x is well above the estimated fair P/E of 15.1x. This implies the market is pricing in a stronger earnings profile than that fair ratio benchmark suggests. The same 23.1x level is also higher than the peer average of 18.1x and sits far above the broader North American insurance industry average of 11.4x. This indicates investors are assigning a much higher valuation than both immediate peers and the wider sector and that the fair ratio gives a lower level the valuation could move toward over time.
Explore the SWS fair ratio for Power Corporation of Canada.
Result: Price-to-Earnings of 23.1x (OVERVALUED)
Still, the current premium P/E leaves Power Corporation of Canada exposed if investor enthusiasm for fintech cools or if analyst targets are revised lower.
Find out about the key risks to this Power Corporation of Canada narrative.
Another View: DCF Says Slightly Overvalued
The rich P/E story for Power Corporation of Canada meets a cooler message from the SWS DCF model. On future cash flows, the CA$96.8 share price sits above an estimated value of CA$91.8. That tilt toward overvaluation raises a simple question. Is the crowd paying up for momentum or overpaying for growth that may not materialise?
Look into how the SWS DCF model arrives at its fair value.
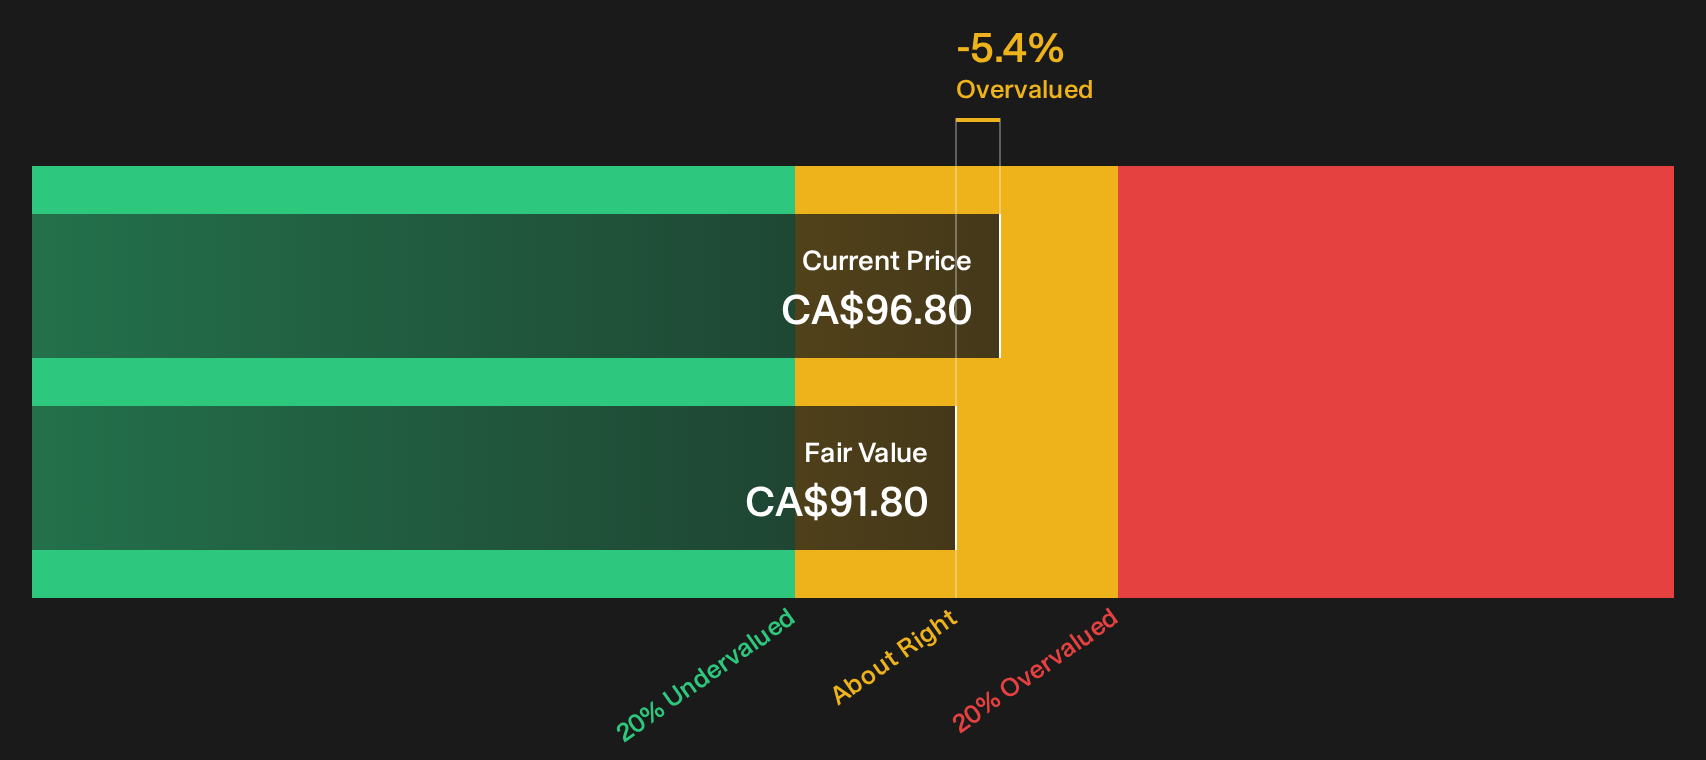
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Power Corporation of Canada for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big premium and punchy returns can feel persuasive, yet the picture is never one sided. Act while the data is fresh and weigh both sides of Power Corporation of Canada for yourself with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Power Corporation of Canada?
Do not stop with one opportunity. The best portfolios come from comparing multiple strong candidates side by side and acting when the odds line up in your favour.
- Target resilient balance sheets and sturdy fundamentals by scanning a curated list of solid balance sheet and fundamentals (6 results) that can help you stress test your next idea.
- Hunt for pricing gaps where quality meets value by using the focused 4 high quality undervalued stocks instead of settling for whatever is already popular.
- Lock in potential cash flow streams by reviewing a hand picked 3 dividend fortresses before the market closes the yield window.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com