
InnoCare Pharma (SEHK:9969) Climbed, What Is Driving Attention Today?
InnoCare Pharma (SEHK:9969) drew fresh attention after presenting new orelabrutinib data at the ESMO 2026 Congress, highlighting high response rates, durable outcomes and manageable safety across several lymphoma and leukemia settings.
For investors watching the tape, InnoCare Pharma’s 1-day share price return of 2.01% sits alongside a 30-day share price decline of 17.38% and a year-to-date share price fall of 6.80%. The 3-year total shareholder return of 84.92% contrasts with a 1-year total shareholder return drop of 15.58%, highlighting long-term gains but fading momentum in the short run as the market weighs fresh orelabrutinib data and the recent swing to earnings per share of CN¥0.39 over the first nine months of 2026.
Scan a curated pool of biopharma players already turning clinical progress into earnings with the 609 high quality undiscovered gems that share some of InnoCare Pharma's mix of late-stage assets and profitability.
Bulls point to orelabrutinib data and fresh profitability, while bears focus on the recent 30 day slide and mixed return history. Which side does the current valuation of InnoCare Pharma appear to support?
Most Popular Narrative: 41% Undervalued
InnoCare Pharma last closed at HK$11.65, while the most followed narrative sets fair value at HK$19.62 using a 7.25% discount rate. That gap frames a story where the share price trails the assumptions baked into analysts’ long range cash flow and earnings models.
The company has a strong pipeline with numerous drugs in late-stage development, including tafasitamab, zurletrectinib, and others, expecting approvals and launches in the next few years, which could significantly bolster future revenues.
The introduction of InnoCare's ADC platform aims to tap into new therapeutic areas with highly differentiated products, potentially opening new revenue streams and improving net margins through therapies with a better safety profile.
See why 1 investors see InnoCare Pharma as 41% undervalued.
Result: Fair Value of HK$19.62 (UNDERVALUED)
Still, the reliance on orelabrutinib and heavy R&D spending could hurt the InnoCare Pharma story if key trials disappoint or competitors gain ground faster than expected.
Find out about the key risks to this InnoCare Pharma narrative.
Another View: InnoCare Pharma On Earnings Multiples
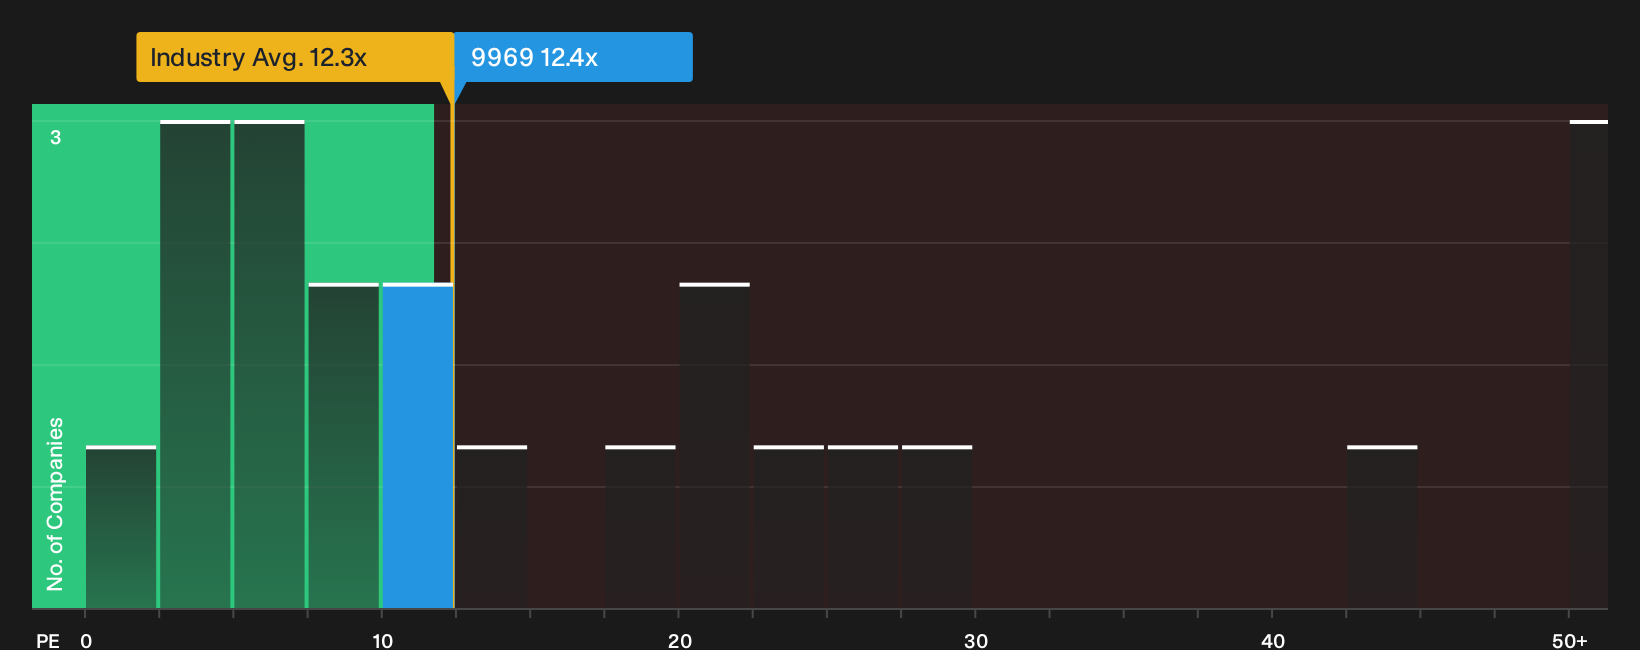
The earlier narrative leans on discounted cash flows and a fair value of HK$19.62. On simple earnings metrics, InnoCare Pharma looks less clear cut. The P/E sits at 12.4x, only a touch higher than the Hong Kong Biotechs industry on 12.3x, yet above a fair ratio of 6.6x that our model suggests the market could move toward. That mix points to room for upside if optimism about the pipeline holds, but also real downside risk if sentiment shifts back toward that lower fair ratio. Which story do you lean toward?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between enthusiasm and caution around InnoCare Pharma feels sharp, treat that as your signal to check the numbers yourself, weigh the clinical story against the balance of risks and upsides, and ground your own stance in the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond InnoCare Pharma?
Do not stop at InnoCare Pharma. Broaden your watchlist with focused stock ideas that balance opportunity and risk using clear, data driven filters.
- Zero in on strong fundamentals and potential mispricing by scanning a curated pool of 191 high quality undervalued stocks that may suit a value focused watchlist.
- Protect your downside first by reviewing 228 resilient stocks with low risk scores that pair steadier risk profiles with solid underlying financials.
- Spot earlier stage prospects with room to grow by combing through a 131 elite penny stocks with strong financials that filters for stronger balance sheets and earnings quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com