
Voltas Fell While Profit Rose
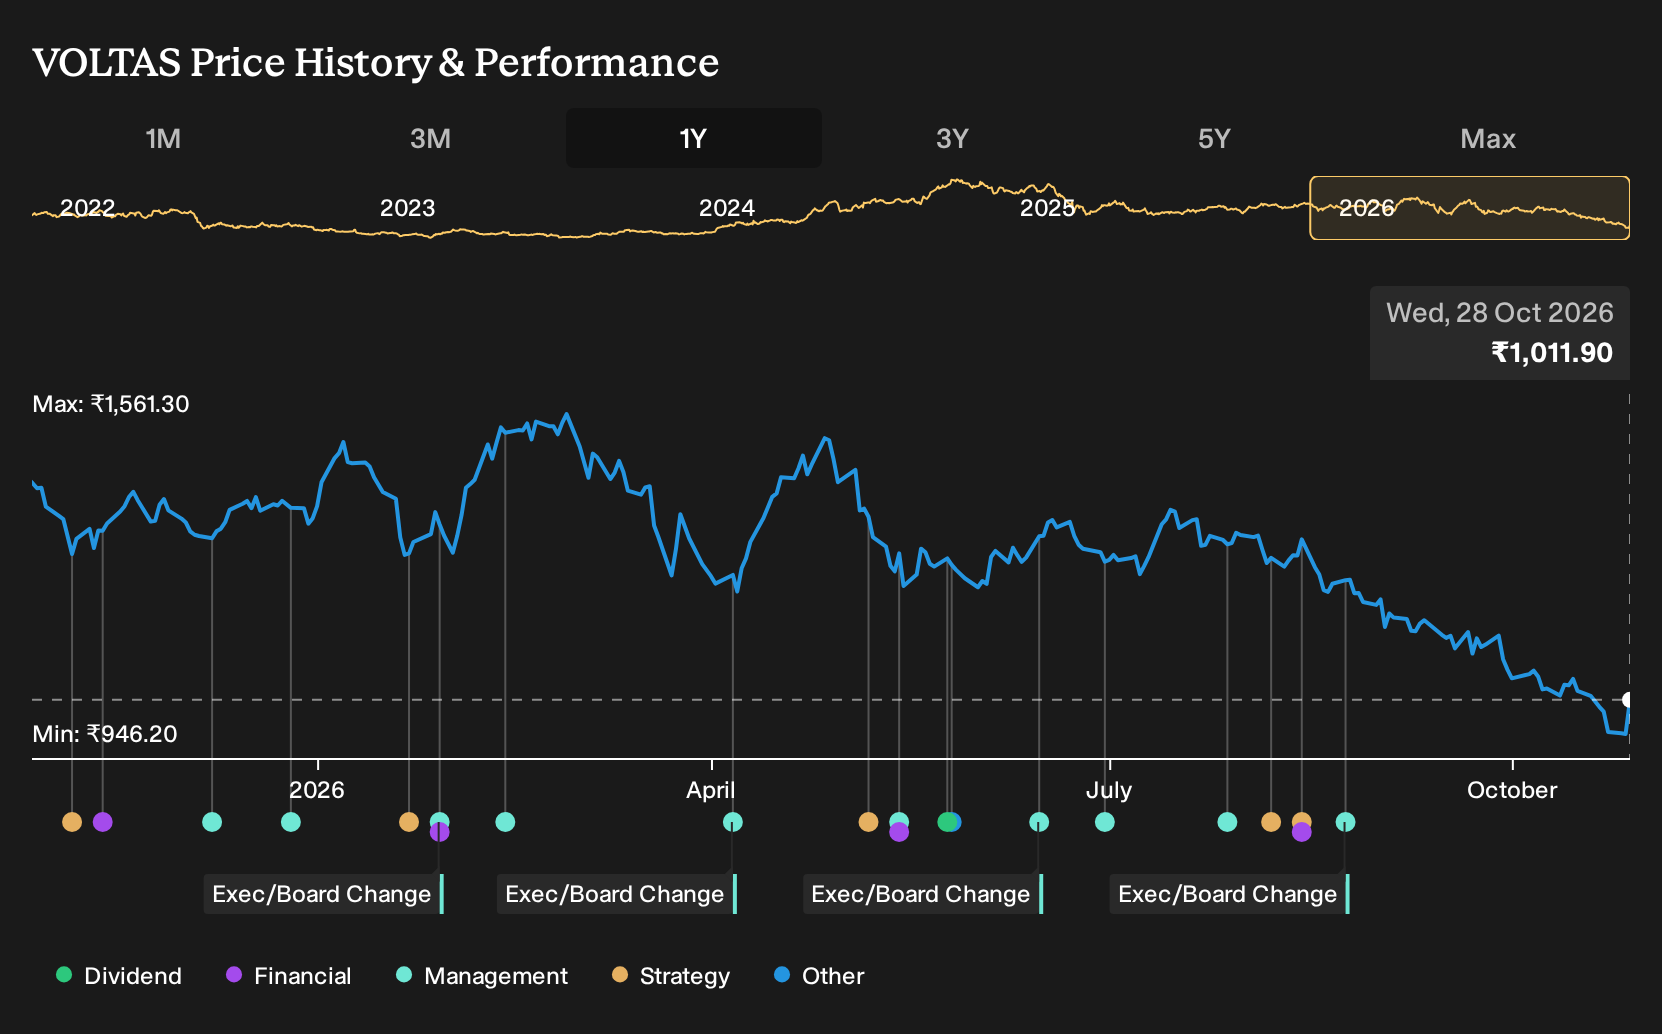
Voltas just served up a cleaner quarter, with higher revenue, stronger net income and a fatter margin, yet long term holders still saw red. For Voltas shareholders, the loss over the past year was 28.5%, including dividends. If you had bought on 28 October 2025, seeing bulls talk about premium cooling and bears warn about rising compliance costs, which signals would have looked most convincing before that drop showed up on your statement?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Voltas has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Two Voltas Narratives Investors Had To Weigh
The shares cost ₹1,428 at the start of the period, and anyone looking at Voltas then had to choose between two very different stories.
The bullish narrative put Fair Value at ₹1,850. It leaned on rapid urbanization, rising demand for cooling, and the idea that connected, AI and IoT-enabled appliances would support a richer product mix and stronger margins.
The bearish view set Fair Value at ₹1,032. It focused on rising compliance costs from tighter energy standards and the risk that lagging technology and heavy seasonality in room air conditioners would weaken market share and future revenue.
What The Voltas Results Actually Tested
The clearest new fact was the Q1 2027 earnings print. Voltas reported revenue of ₹46,735m and net income of ₹2,137.6m, with net margin at 4.6% versus 3.6% a year earlier. That margin shift leaned toward the bullish story that talked up richer product mix and better profitability, although one quarter still left the overall debate unsettled.
The key lesson sits in that margin line. When a thesis hinges on pricing power or compliance costs, track net margin and not just revenue or profit. Then judge whether the change in that single ratio really matches the promises that were made in each narrative before you commit fresh capital to any company.
What Voltas Buyers Are Being Asked To Believe Now
Voltas now trades at ₹1,012, with this Narrative’s Fair Value sitting above that level based on its own assessment rather than a proven fact.
The current Narrative leans on room air conditioner share gains, capacity ramp up and cost work. A buyer today would be assuming that margin recovery across key segments actually materializes and holds.
"The main thing that has to go right is that Voltas turns its cost programs, backward integration, new compressor capacity and Voltbek scale into a sustained recovery in segment margins, while losses in newer categories narrow."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Voltas
Voltas sells comfort. Your air stays cool, your room more liveable.
There is a similar promise in a very different aisle.
Sportswear buyers also want reliable performance at prices that still feel reachable.
One large athletic brand uses massive scale to push costs down, keeping footwear and clothing within range for budget-conscious shoppers.
When budgets tighten, that focus on affordability and direct sales can matter, hinting at how consumer staples and comfort might quietly rhyme.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 16% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com