
How Revenue Growth And Buybacks Will Impact WisdomTree Stock (WT)
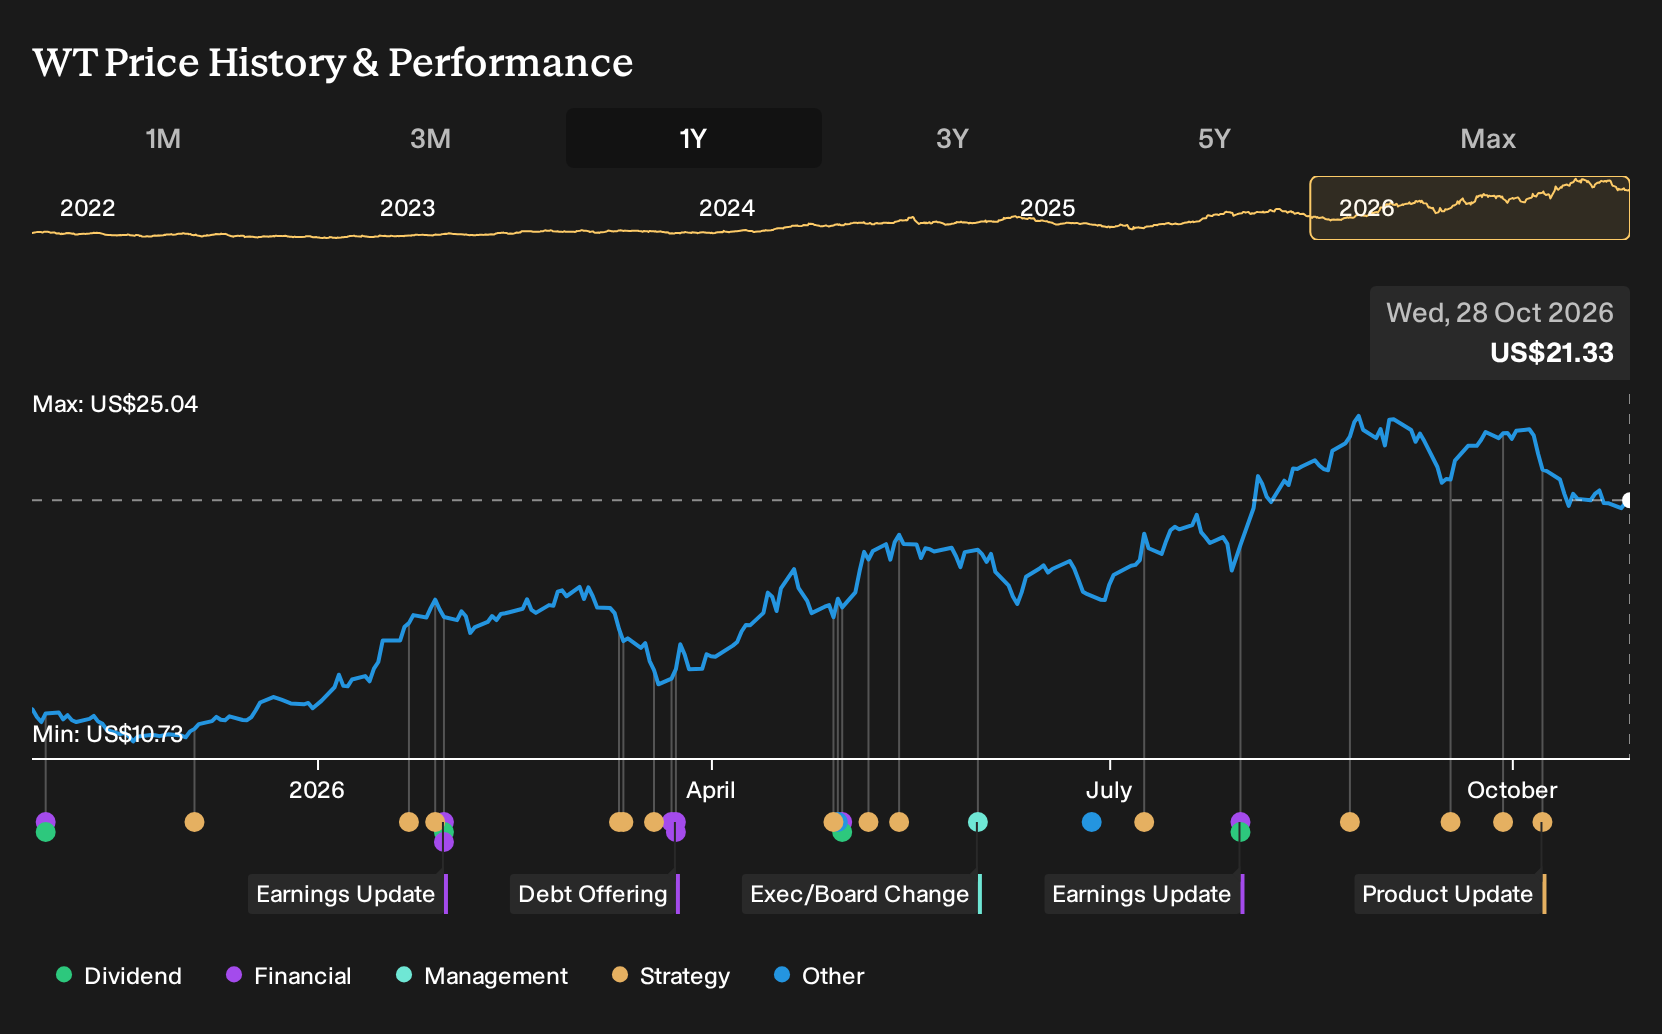
- Recent commentary has put WisdomTree in focus for its combination of strong revenue growth and continuing share repurchases, framing the asset manager as one of a small group of financial stocks that analysts expect to meet or beat their forecasts.
- The emphasis on buybacks highlights how WisdomTree is using its balance sheet and cash generation to recalibrate its equity base. This choice can reshape per share economics even before any change in assets under management or fee rates.
- We will now explore how WisdomTree's investment narrative might be affected by analysts highlighting its revenue momentum alongside an active share repurchase program.
Scan how WisdomTree's mix of revenue momentum and buybacks compares by lining up peers in the 26 high quality undervalued stocks that may be priced more conservatively for similar themes.
WisdomTree Investment Narrative Recap
To own WisdomTree, you need to be comfortable with an asset manager leaning into higher fee segments such as ETFs, alternatives, tokenized assets, and model portfolios, while also running an active buyback program. The short term swing factor is whether current revenue momentum holds up as new products in areas like farmland and digital assets scale.
The biggest risk right now sits around execution on that spending ramp. Discretionary costs in 2026 are guided higher to US$80 million to US$86 million, so if those marketing, distribution and Ceres related investments do not translate into fresh assets, operating margins and earnings could come under pressure.
The recent focus on WisdomTree’s share repurchases makes its earlier Ceres Partners acquisition especially relevant. That deal is about pushing deeper into private markets such as U.S. farmland, where committed capital can support fee rich strategies that complement traditional ETFs and digital products tied to tokenization and model portfolios.
If Ceres funds are drawn and deployed effectively, they can reinforce revenue from alternatives at the same time that tokenized assets and international ETFs expand the base. The operational watchpoints are AUM traction in these higher yielding lines and how well management balances elevated spending, buybacks, and debt levels that are not fully covered by operating cash flow.
WisdomTree's current analyst storyline links US$913.0 million in revenue and US$317.7 million in earnings by 2029 to an assumed 14.4% yearly revenue growth rate and an earnings step up of about 4x from US$80.2 million today.
Uncover why WisdomTree's fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans hard into WisdomTree’s cost risk rather than its revenue story. The most optimistic analysts were penciling in about US$958.4 million of 2029 revenue and US$320.3 million of earnings before this news, yet still flagged that lifting discretionary spend to a range of US$80 million to US$86 million could quickly reshape that picture. You can treat this as a reminder that even bullish forecasts can shift and that it helps to weigh several narratives before deciding what the latest headlines might mean for you.
Explore 2 other WisdomTree fair value estimates, including one that suggests as much as 23% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your WisdomTree research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for WisdomTree. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WisdomTree's overall financial health at a glance.
Looking for more WisdomTree investment ideas?
If WisdomTree has sharpened your focus on where capital is working hardest, it can help to widen the lens and compare it with other stocks that share similar traits or offer different risk and income profiles.
- For investors who want potential mispricing plus quality, scan a curated 26 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into the price.
- If resilience and balance sheet strength sit higher on your checklist than rapid expansion, filter for companies with cleaner finances using the list of solid balance sheet and fundamentals (24 results) to see which ones merit a closer look.
- Those who prioritize income alongside capital appreciation can review a focused 6 dividend fortresses that aim to pair higher yields with a sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com