
Cash Flow Guidance Raise Altering The Investment Case For Galp Energia Stock (ENXTLS:GALP)?
- Galp Energia reported nine month 2026 revenue of €20,063 million and net income of €852 million, supported by solid Q3 cash generation and the Bacalhau FPSO ramp up in Brazil.
- The raised full year guidance, built on stronger operating cash flow, suggests Galp Energia is leaning on upstream efficiency rather than headline earnings to support its business plan.
- We will now assess how Galp Energia's investment narrative evolves in light of stronger cash generation supported by the Bacalhau FPSO ramp up.
Galp Energia SGPS Investment Narrative Recap
To own Galp Energia SGPS, you need to be comfortable with a cash-centric story anchored in large offshore projects. The central idea is that assets like Bacalhau can keep generating strong operating cash flow even when reported earnings move around. The latest nine-month results, with higher revenue but softer net income, fit that theme and do not fundamentally change it.
The key near-term swing factor remains execution on the Bacalhau ramp-up and related upstream operations, which underpin the upgraded cash flow guidance. The main risk is still concentration in a handful of large, complex projects where any delay, tax dispute or regulatory issue could quickly show up in free cash flow and limit capital flexibility.
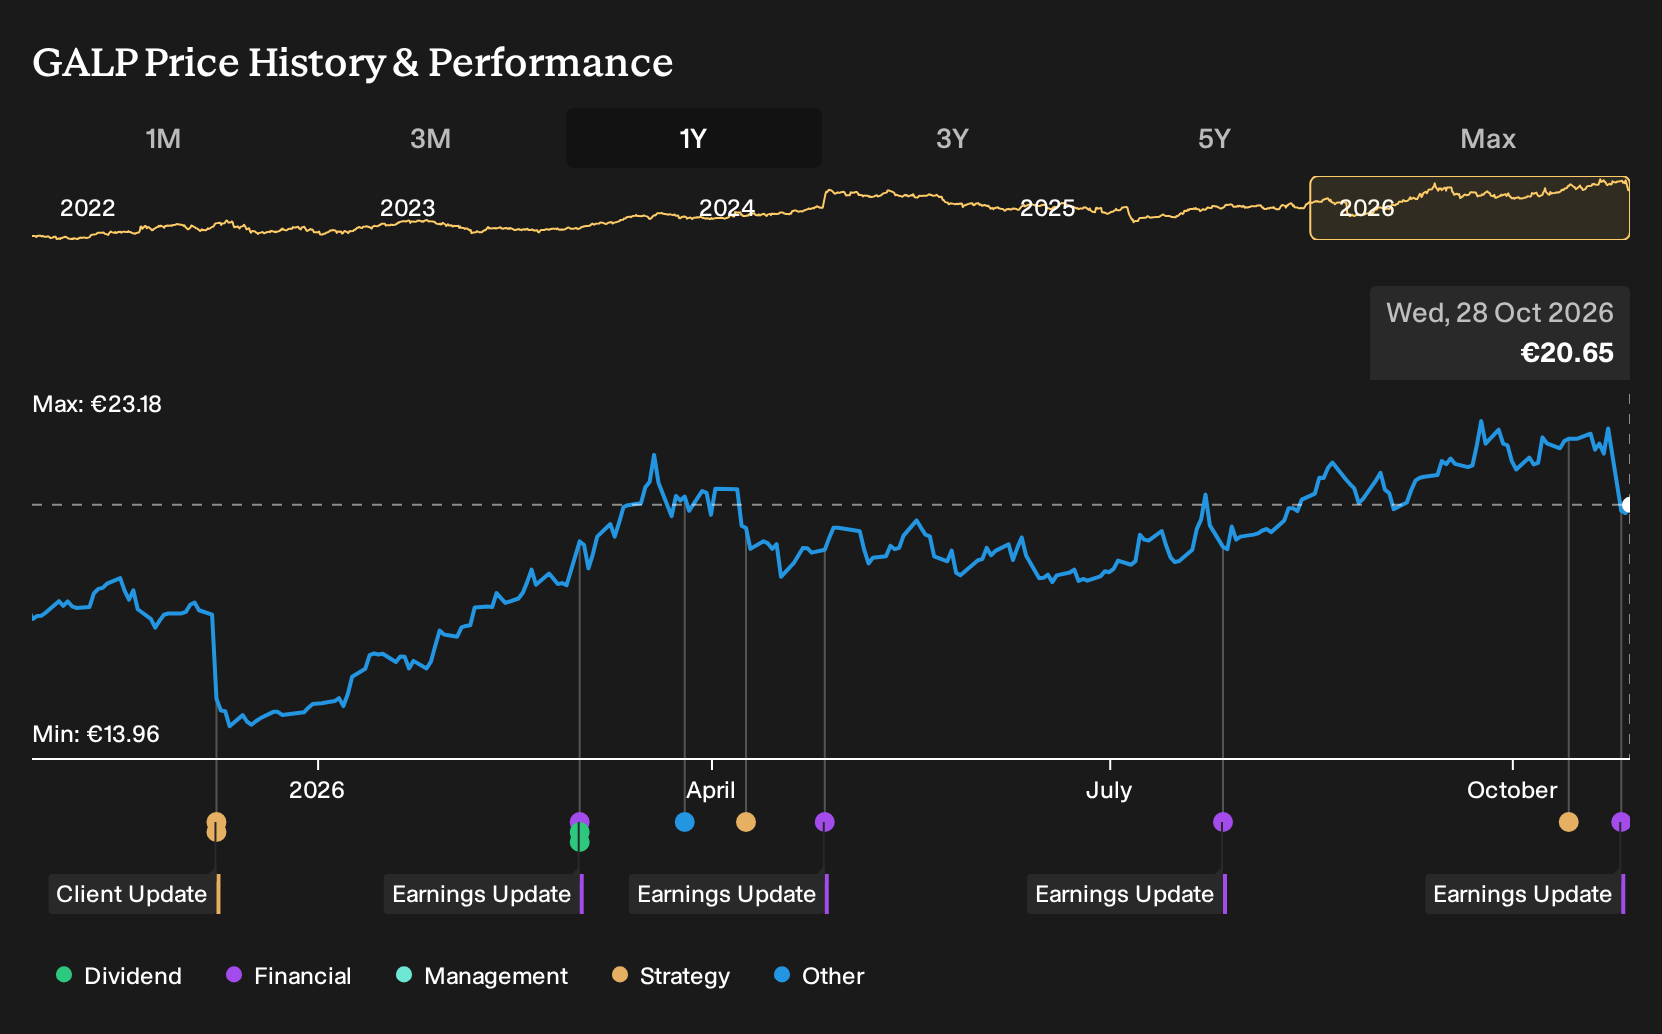
The most recent data point is the nine-month 2026 earnings release. Galp Energia SGPS reported €20,063 million of revenue and €852 million of net income, alongside basic EPS of €1.17, which indicates that solid Q3 cash generation is supported by higher top-line activity.
For potential catalysts, that report ties directly to the Bacalhau FPSO ramp-up that management credits for stronger operating cash flow and the raised full-year guidance. The same disclosure also highlights the risk side, with large offshore exposure and items like the Mozambique tax dispute showing that execution, contract terms and regulatory outcomes can still move the story quickly.
Galp Energia SGPS' current narrative is built around analyst assumptions that revenue grows at 2.0% per year and that earnings stay at roughly €1.1b through the forecast period, with consensus pointing to about €22.8b of revenue and €1.1b of earnings by 2029, which implies flat earnings compared with today.
Uncover why Galp Energia SGPS' fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view fixates on merger risk. Before this earnings release and the Moeve deal falling through, the most cautious analysts were building in revenue of about €15.6b and earnings near €956.0 million by 2029 for Galp Energia. That is a far more pessimistic script. It shows how sharply opinions can differ and invites you to compare these older assumptions with your own read of the new information.
Explore 3 other Galp Energia SGPS fair value estimates, including one that suggests it could be worth just €23.51.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Galp Energia SGPS research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Galp Energia SGPS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Galp Energia SGPS' overall financial health at a glance.
Looking For More Investment Ideas Beyond Galp Energia SGPS?
Once you have a handle on Galp Energia SGPS, it can help to compare its risk and return profile with other opportunities that share similar qualities. The Simply Wall St Screener lets you filter for themes, balance sheet strength, and income profiles so you can see where Galp Energia SGPS fits within a broader watchlist.
- For investors who want income that can potentially smooth out volatility, you might consider a set of higher yielding payers using 226 dividend fortresses as a starting universe.
- If resilience is your priority, look for companies with steadier fundamentals and lower overall risk scores by screening through 228 resilient stocks with low risk scores.
- If you are hunting for under-the-radar opportunities with solid fundamentals, you can build a watchlist sourced from 609 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com