
Earnings Beat Could Reframe The Case For Rush Enterprises Stock (RUSH.A)
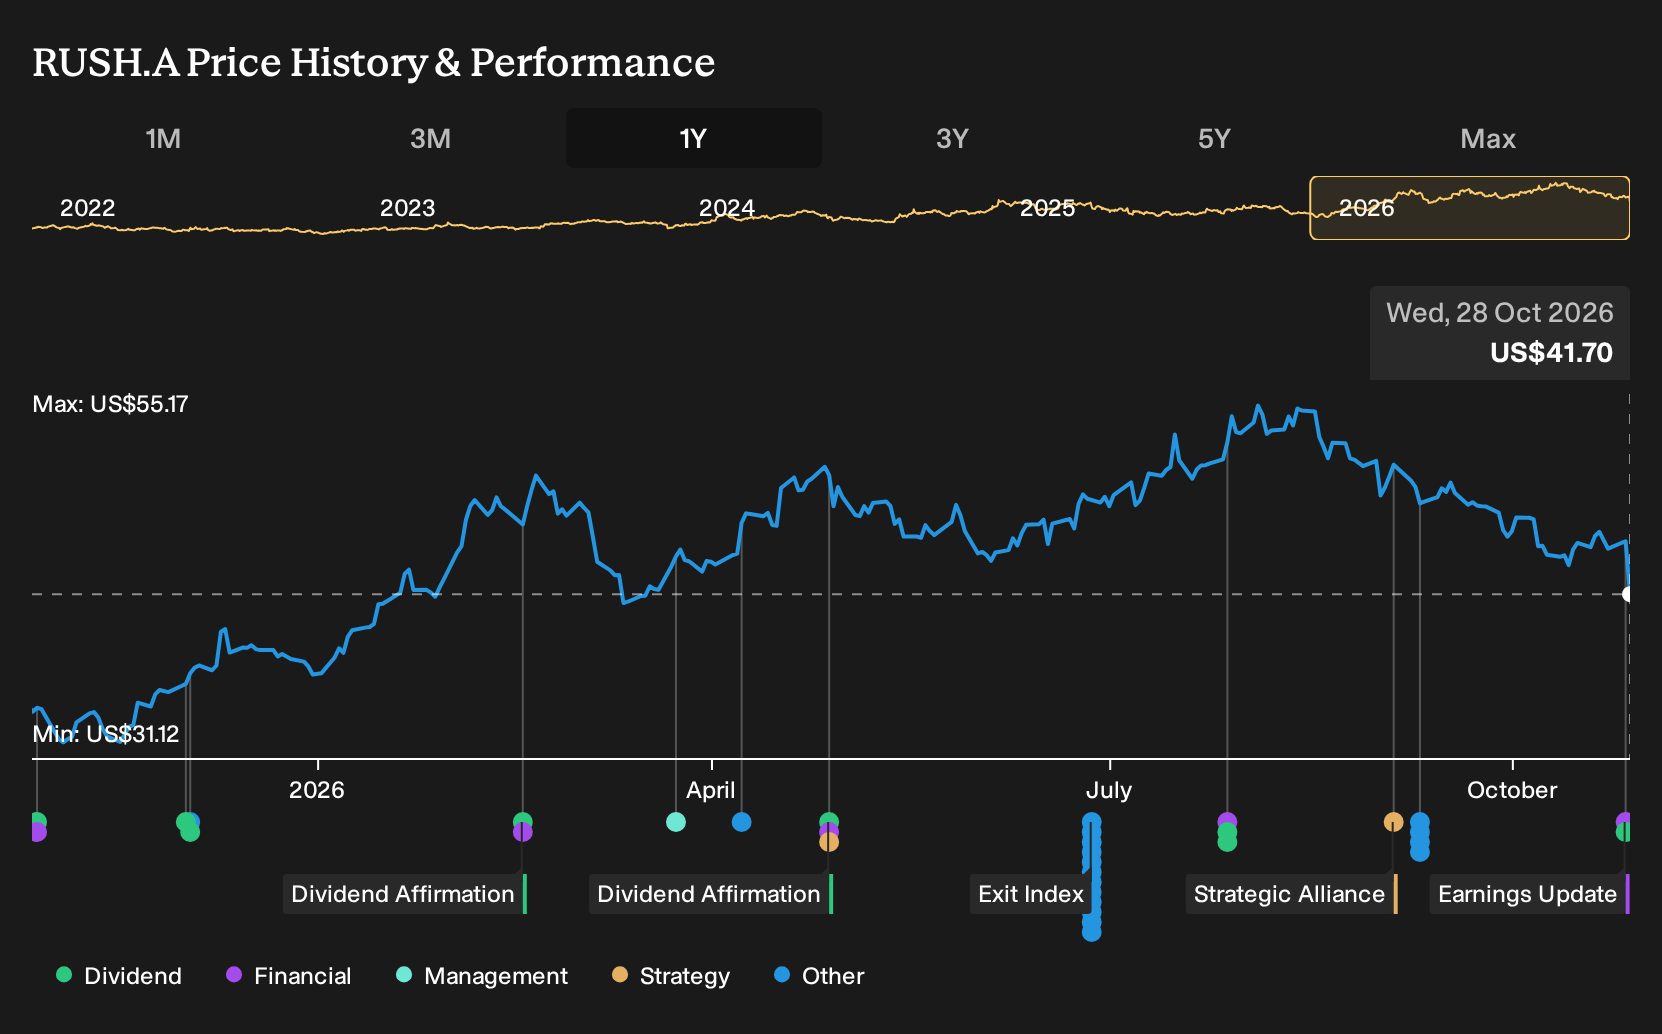
- Rush Enterprises reported Q3 2026 revenue of US$2.11b, net income of US$78.04 million and higher earnings per share compared with a year earlier, alongside a quarterly dividend of US$0.14 and continued buybacks.
- The joint venture entry into refrigerated transport and market share gains in new Class 8 truck sales point to Rush Enterprises using its wider dealership footprint to support both vehicle and aftermarket activity.
- We will now look at how Rush Enterprises' third quarter performance might influence its investment narrative for long term investors.
Scan for other transport and industrial dealers that demonstrate similar earnings resilience and capital returns by reviewing our hand picked list of solid balance sheet and fundamentals (24 results)
Rush Enterprises Investment Narrative Recap
For Rush Enterprises, the core belief is that a broad dealership network and higher margin aftermarket and leasing operations can keep cash generation relatively steady through trucking cycles. The latest quarter fits that view. Revenue of US$2.11b and net income of US$78.04 million point to a business still moving trucks and servicing older fleets despite mixed freight conditions.
The near term swing factor remains how quickly fleets commit to new vehicles once emissions rules and build schedules are clearer. The biggest risk is that regulatory uncertainty and weak medium duty demand keep customers deferring orders. On that front, the recent update does not radically change the immediate risk reward balance.
The quarterly dividend of US$0.14 per share is the announcement that most directly ties back to the current Rush Enterprises story. Regular cash returns ask you to judge whether earnings and the balance sheet can support both shareholder payouts and the capital needed for acquisitions, the refrigerated transport joint venture and ongoing facility investments.
If freight demand stays uneven or medium duty pressure lingers, fixed dividend commitments narrow management’s flexibility just as emissions driven replacement cycles and dealer consolidation create openings. For you as a long term holder, the payout becomes one more lens to monitor execution quality, aftermarket resilience and how quickly deferred Class 8 and other truck purchases convert into deliveries.
What the Analyst Scenario Implies for Rush Enterprises
Rush Enterprises' narrative projects US$9.8b revenue and US$386.5 million earnings by 2029. This assumes 10.6% yearly revenue growth and an earnings increase of about US$121 million from US$265.2 million today.
Uncover why Rush Enterprises' fair value indicates a 36% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Rush Enterprises analysts focus on aftermarket strength as a key catalyst, arguing that US$642.7 million of quarterly parts, service and collision revenue and 63% of gross profit can underpin steadier earnings. Those forecasts, built before this Q3 2026 update, assume revenue climbing toward about US$10.6b and earnings of roughly US$377.2 million by 2029. You can treat today’s dividend, buyback progress and latest US$2.11b quarterly revenue as fresh evidence and decide whether that upbeat path still feels realistic, or whether your view sits closer to the more cautious consensus.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Rush Enterprises research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rush Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Rush Enterprises' overall financial health at a glance.
Looking for more investment ideas beyond Rush Enterprises?
Once you have a view on Rush Enterprises, it can help to widen the lens and compare it with other businesses that show different mixes of quality, income and balance sheet strength. The Simply Wall St Screener gives you a straightforward way to filter for those traits without getting lost in raw data.
- If capital preservation sits high on your priority list, you could start with companies that pair resilient operations with lower risk scores by using the 32 resilient stocks with low risk scores.
- Income focused investors can scan for businesses offering higher yields while still aiming to sustain payouts over time by using the 6 dividend fortresses.
- For those hunting for underfollowed opportunities with solid fundamentals, you can broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com