
Why Lenovo Stock Is In Focus After AI Expansion And TIME Recognition
- Lenovo Group was recently included in TIME's World's Best Companies 2026 list and, around the same time, expanded its Lenovo AI Library and partnerships, including deeper SentinelOne integration and the Rafay Systems collaboration around hybrid AI orchestration.
- The cluster of AI focused launches, ranging from computer vision for retail and manufacturing to governance tools and productivity agents, points to Lenovo Group pushing harder into higher value infrastructure, software and services rather than relying mainly on traditional hardware cycles.
- We will look at how Lenovo Group's expanded AI Library and solutions portfolio could reshape the investment narrative around its AI ambitions.
Lenovo Group Investment Narrative Recap
To own Lenovo Group, you need to believe the pivot toward AI infrastructure, software and services turns its broad hardware footprint into a higher value platform. The short term swing factor is still how quickly that reported US$54b AI server pipeline converts into recognized revenue, while keeping profitability intact despite tight memory supply and higher DRAM costs in PCs and smartphones.
The fresh AI Library launches and ecosystem deals signal execution progress on that mix shift but do not, by themselves, resolve the main risk. If customers delay or shrink AI rollouts, heavy AI infrastructure and R&D spend could weigh on net income margins and leave the current P/E multiple exposed to sentiment swings.
The Lenovo AI Library expansion looks most relevant for understanding current catalysts. Management is packaging proven AI deployments into repeatable offerings, from computer vision in retail branches and factories to productivity agents and IT operations tools. That approach pushes more of Lenovo Group’s opportunity into software, services and TruScale style models that can sit on top of existing hardware relationships.
Execution quality around these use cases now matters as much as box shipments. Faster time to value and measurable productivity gains, such as the internal Knowledge Super Agent outcomes, support the thesis that Lenovo Group can deepen its Solutions and Services and Infrastructure Solutions revenue mix. If enterprises pull back on AI experimentation or struggle with governance and compliance, adoption of these Library use cases could slow and soften that catalyst.
Lenovo Group Consensus AI Build Out Assumptions
Lenovo Group's narrative projects $142.3 billion revenue and $6.2 billion earnings by 2029. This implies 16.0% yearly revenue growth and roughly a 7.8x earnings increase from $798.0 million today.
Analysts are effectively treating the AI infrastructure, software and services push as a multi year remix of the income statement rather than a quick trading story. Forecasts bake in 16.0% annual top line expansion over the next three years and a move in profit margins from 0.9% today to 4.4% by around 2029. That margin step up is what takes earnings from US$798.0 million today to a consensus US$6.2b in the same year, even before considering the more optimistic US$11.2b or the more cautious US$5.1b scenarios.
The implied P/E reset is just as important as the growth arithmetic. To line up with the analyst price targets, Lenovo Group would need to trade around 15.2x those 2029 earnings, compared with 43.1x today and the wider Hong Kong tech sector closer to 26.3x. That means the story in these models is not about the multiple stretching. It is about earnings doing most of the heavy lifting while the valuation multiple compresses toward something closer to sector norms.
Revenue expectations in these numbers are sizable. The consensus framework assumes Lenovo Group reaches roughly US$142.3b in sales by 2029 and turns that into US$6.2b of profit while holding share count broadly flat. For you as an investor, that links the AI Library, TruScale contracts and infrastructure wins directly to concrete targets that extend beyond short term demand swings in PCs and smartphones.
Uncover how Lenovo Group's fair value indicates a 94% potential upside to its current price that may not last much longer.
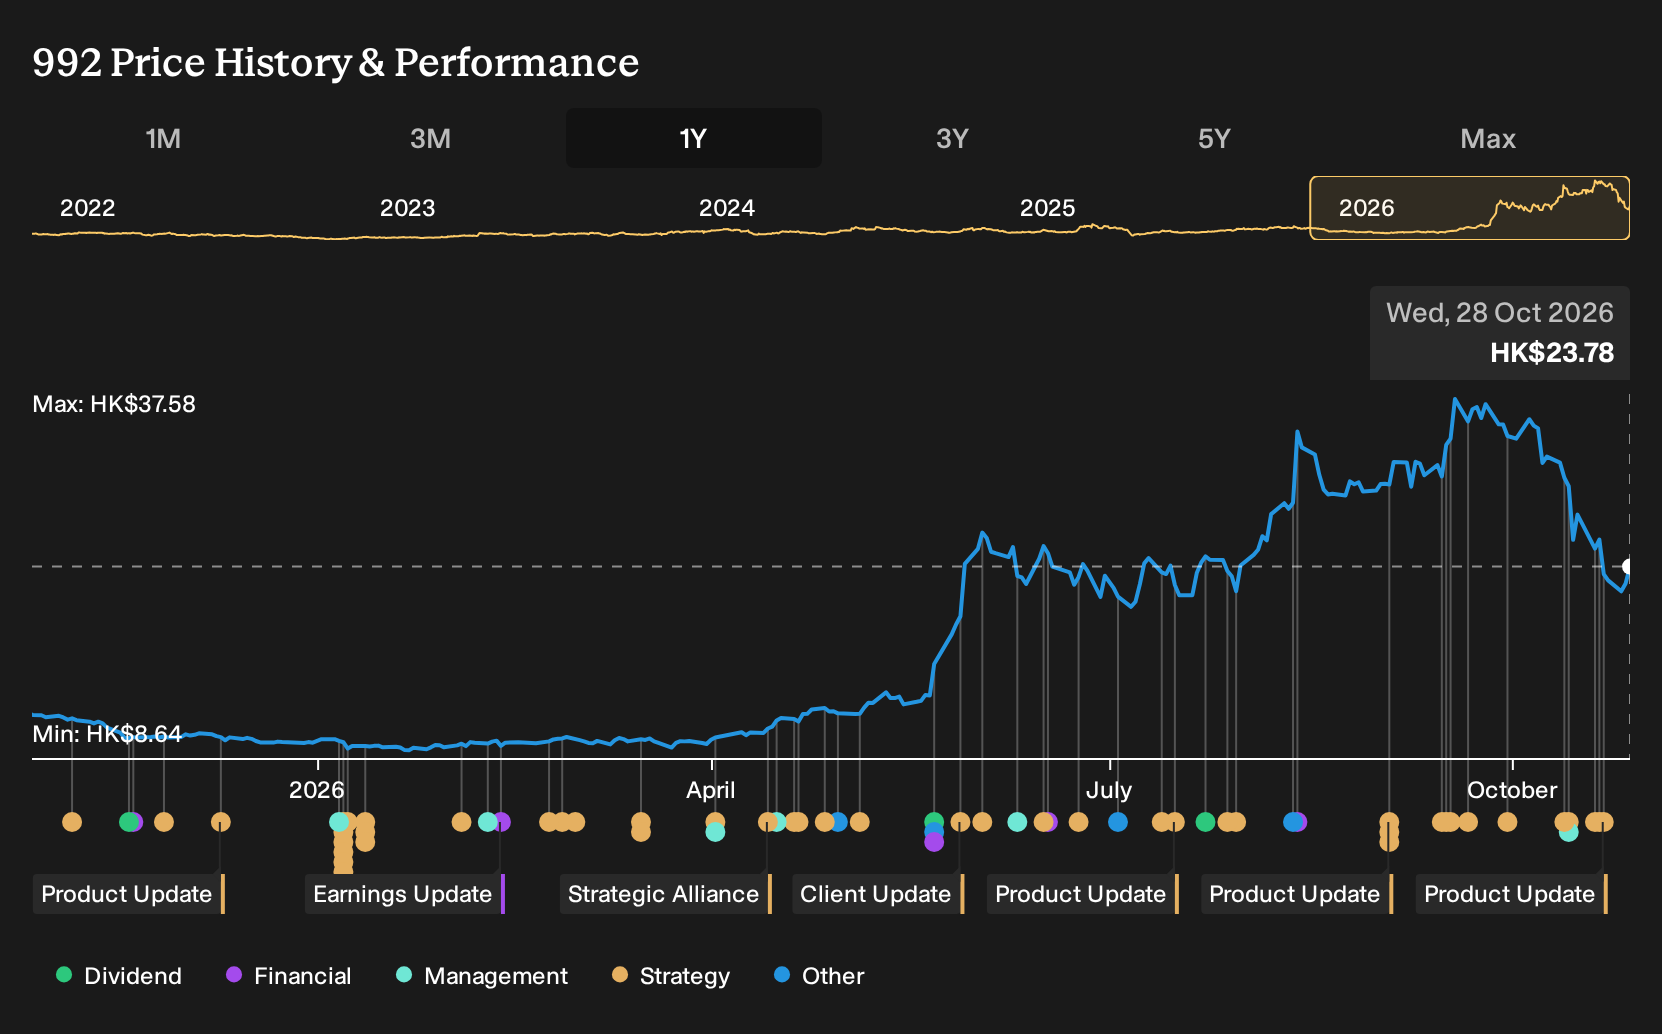
Exploring Other Perspectives
Some of the most optimistic analysts already saw Lenovo Group’s AI push as a margin story, not just a sales story, projecting revenue of about US$181.4b and US$10.3b in earnings by 2029 before this news. You can now ask whether faster AI Library use case adoption could justify those higher figures or prompt fresh scenarios altogether.
Explore 5 other Lenovo Group fair value estimates, including one that suggests potential upside of up to 178% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lenovo Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lenovo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lenovo Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lenovo Group?
If Lenovo Group's AI story has sharpened your interest in where capital might work hardest, it can help to widen the lens and scan other companies with different risk and income profiles using the Simply Wall St Screener.
- For investors hunting for quality at a reasonable price, review companies that screen as attractively priced with solid fundamentals through the 191 high quality undervalued stocks.
- If capital protection and resilience matter most to you, filter for businesses that carry stronger financial footing and lower risk scores with the 228 resilient stocks with low risk scores.
- When you want balance sheet strength to sit alongside earnings power, focus on companies with sturdy finances and consistent fundamentals using the list of solid balance sheet and fundamentals (203 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com