
Asian Market Value Picks: 3 Stocks Estimated Below Intrinsic Value
Amidst the backdrop of rising oil prices and geopolitical tensions, Asian markets have experienced a wave of volatility, with technology stocks particularly under pressure due to concerns over AI investment and financing. In such an environment, identifying stocks that are estimated to be trading below their intrinsic value can offer potential opportunities for investors looking to capitalize on market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zhejiang Hisun Pharmaceutical (SHSE:600267) | CN¥13.40 | CN¥26.30 | 49% |
| Xiamen King Long Motor Group (SHSE:600686) | CN¥9.37 | CN¥18.52 | 49.4% |
| Wus Printed Circuit (Kunshan) (SZSE:002463) | CN¥104.57 | CN¥206.72 | 49.4% |
| Shizuki Electric (TSE:6994) | ¥1192.00 | ¥2356.40 | 49.4% |
| P&H Tech (KOSDAQ:A239890) | ₩3120.00 | ₩6201.00 | 49.7% |
| PAL GROUP Holdings (TSE:2726) | ¥1467.00 | ¥2902.59 | 49.5% |
| Nissui (TSE:1332) | ¥1084.00 | ¥2163.05 | 49.9% |
| Morinaga Milk Industry (TSE:2264) | ¥1077.00 | ¥2134.38 | 49.5% |
| Kumagai GumiLtd (TSE:1861) | ¥1235.00 | ¥2437.97 | 49.3% |
| KB Financial Group (KOSE:A105560) | ₩154000.00 | ₩304406.46 | 49.4% |
Here we highlight a subset of our preferred stocks from the screener.
Ingenic Semiconductor (SZSE:300223)
Overview: Ingenic Semiconductor Co., Ltd. designs, develops, and sells system-on-a-chip (SoC) products for various electronic devices worldwide, with a market capitalization of approximately CN¥56.27 billion.
Operations: Ingenic Semiconductor generates revenue through the design, development, and sale of system-on-a-chip (SoC) products for a range of electronic devices on a global scale.
Estimated Discount To Fair Value: 38.5%
Ingenic Semiconductor is trading at 38.5% below its estimated fair value and significantly below its future cash flow value, indicating it may be undervalued based on cash flows. Recent earnings showed substantial growth, with net income reaching CN¥2.62 billion for the nine months ended September 30, 2026, up from CN¥255.74 million a year ago. Despite high share price volatility recently, the company's earnings and revenue are forecast to grow faster than the market average in China.
- The growth report we've compiled suggests that Ingenic Semiconductor's future prospects could be on the up.
- Dive into the specifics of Ingenic Semiconductor here with our thorough financial health report.
Shenzhen New Industries Biomedical Engineering (SZSE:300832)
Overview: Shenzhen New Industries Biomedical Engineering Co., Ltd. focuses on the research, development, production, and sale of clinical laboratory instruments and in vitro diagnostic reagents for hospitals both in China and internationally, with a market cap of CN¥45.75 billion.
Operations: The company's revenue primarily comes from its in vitro diagnostic segment, which generated CN¥4.84 billion.
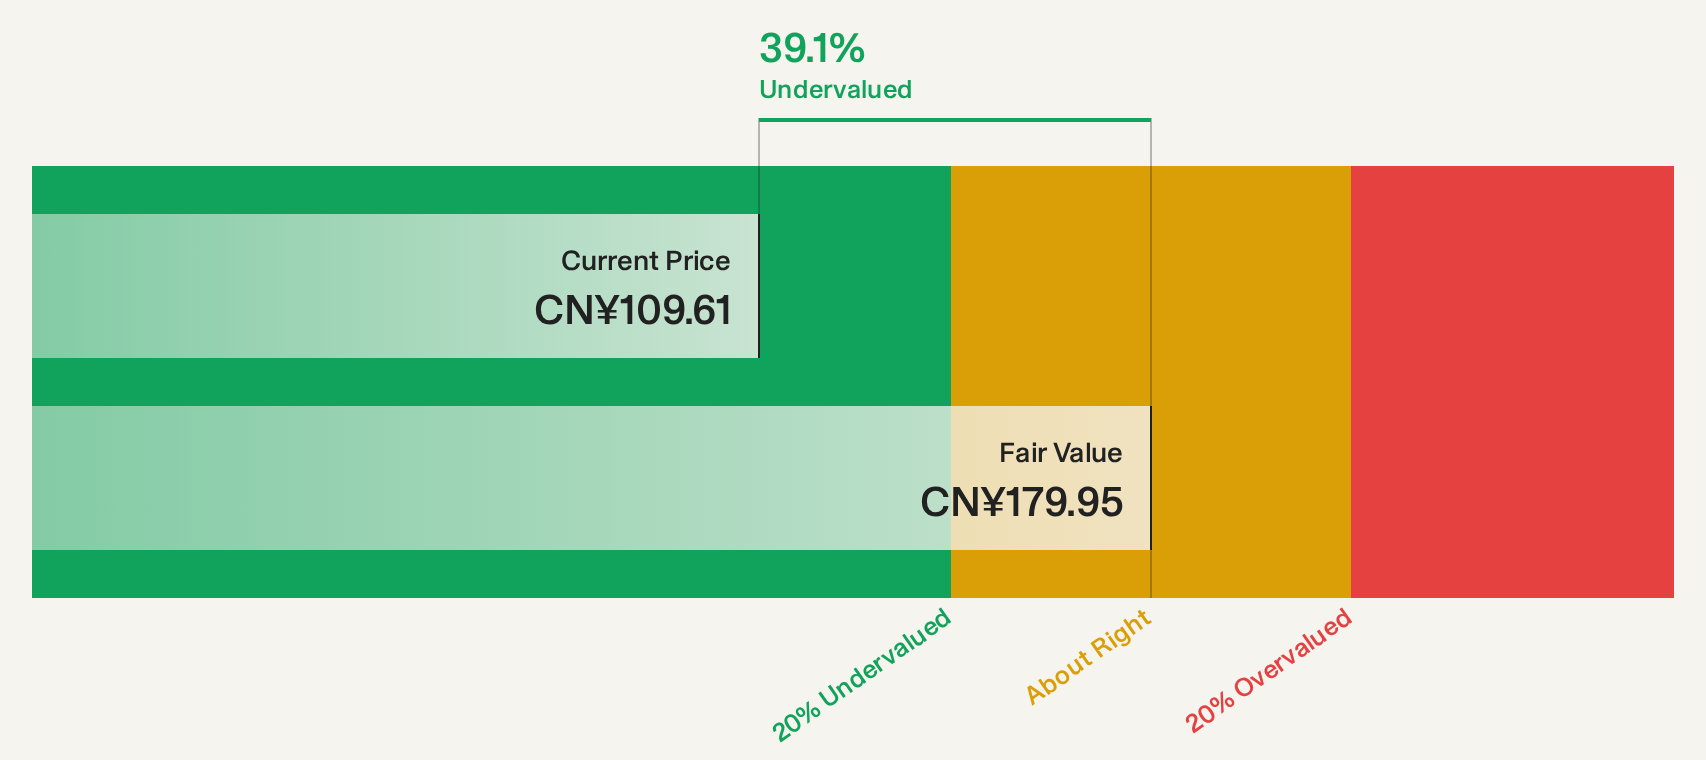
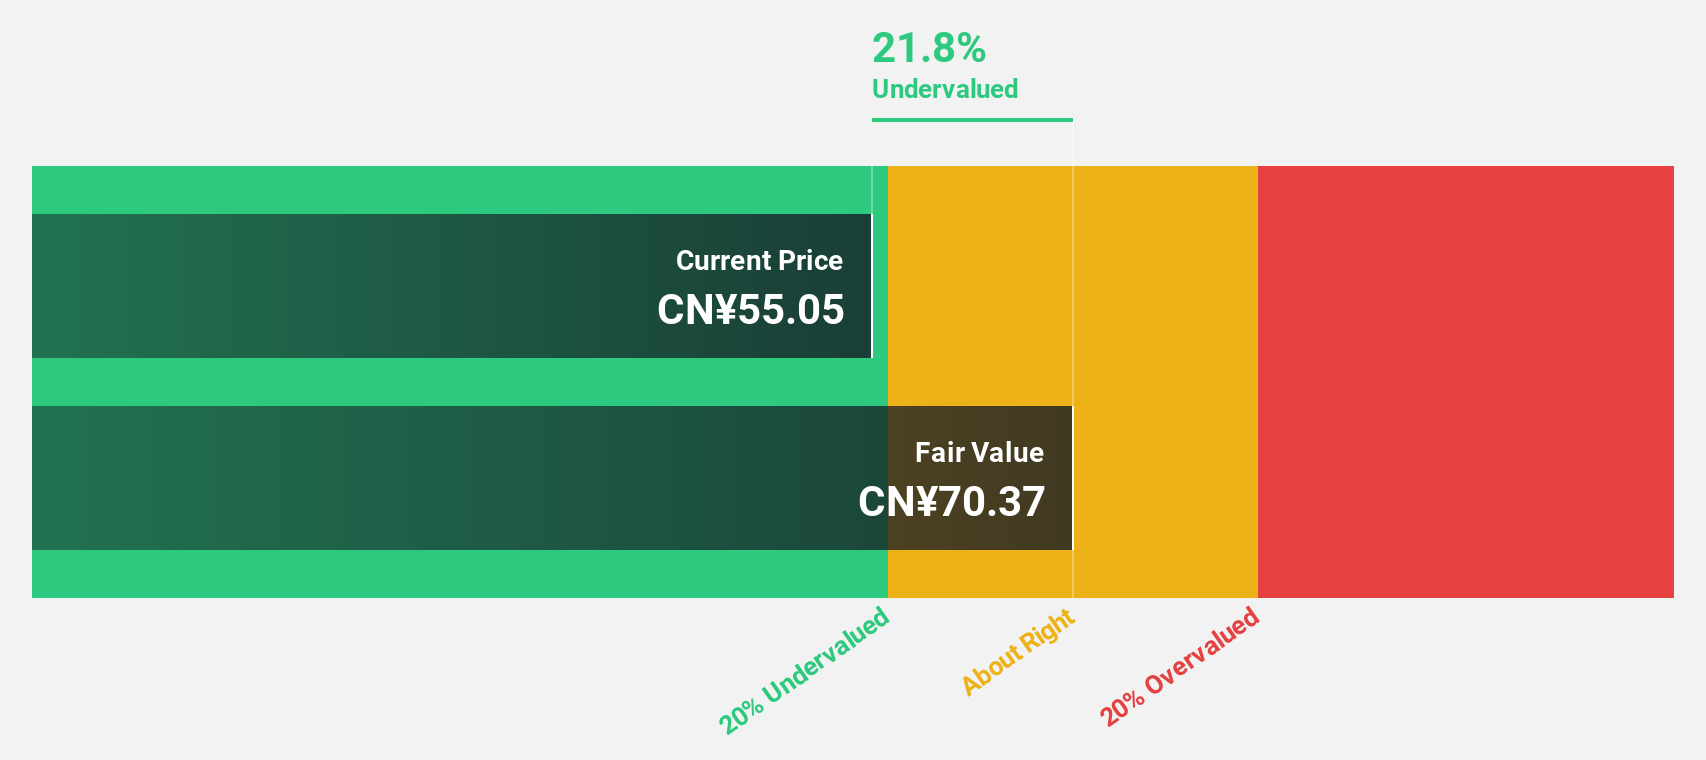
Estimated Discount To Fair Value: 40.8%
Shenzhen New Industries Biomedical Engineering is trading 40.8% below its estimated fair value and significantly under its future cash flow value, suggesting undervaluation based on cash flows. Recent earnings reports show net income of CNY 1,390.59 million for the nine months ended September 30, 2026, up from CNY 1,204.8 million a year ago. However, earnings and revenue growth forecasts are slower than China's market average despite current good relative value compared to peers.
- In light of our recent growth report, it seems possible that Shenzhen New Industries Biomedical Engineering's financial performance will exceed current levels.
- Click to explore a detailed breakdown of our findings in Shenzhen New Industries Biomedical Engineering's balance sheet health report.
Taiwan Semiconductor Manufacturing (TWSE:2330)
Overview: Taiwan Semiconductor Manufacturing Company Limited, along with its subsidiaries, is involved in the manufacturing, packaging, testing, and selling of integrated circuits and other semiconductor devices across various global markets; it has a market cap of NT$62.89 trillion.
Operations: The company's revenue primarily comes from its Foundry segment, which generated NT$4.94 billion.
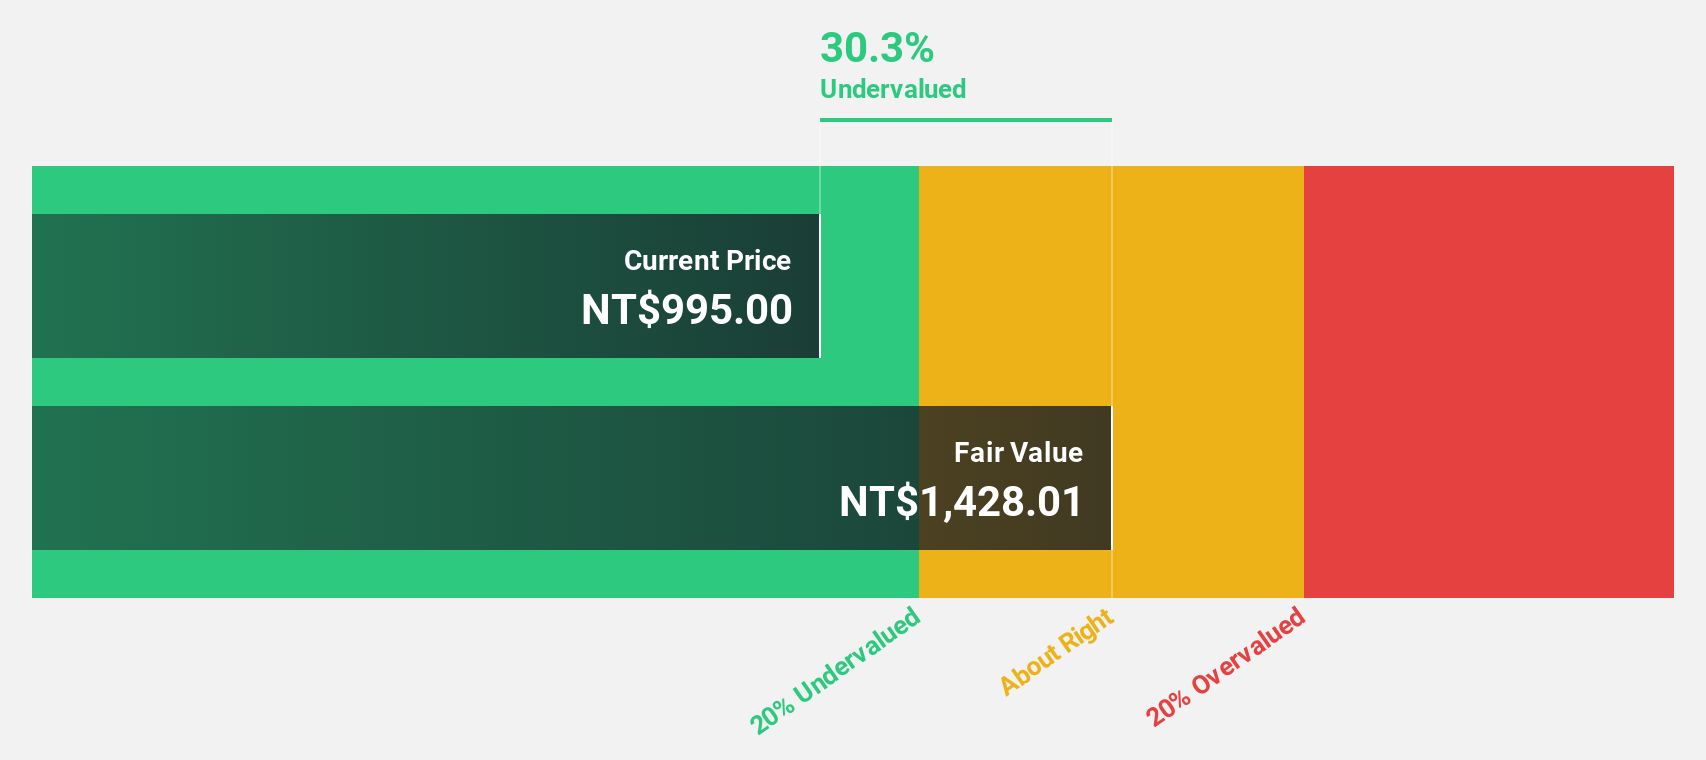
Estimated Discount To Fair Value: 10.4%
Taiwan Semiconductor Manufacturing is trading 10.4% below its fair value estimate, reflecting potential undervaluation based on cash flows. Recent earnings showed substantial growth, with net income rising to TWD 763.06 billion for Q3 2026 from TWD 452.30 billion a year ago. Despite slower expected profit growth compared to the Taiwan market, revenue forecasts remain robust, outpacing market averages. Strategic alliances and technological advancements further bolster its competitive positioning in the semiconductor industry.
- Our comprehensive growth report raises the possibility that Taiwan Semiconductor Manufacturing is poised for substantial financial growth.
- Click here and access our complete balance sheet health report to understand the dynamics of Taiwan Semiconductor Manufacturing.
Seize The Opportunity
- Investigate our full lineup of 176 Undervalued Asian Stocks Based On Cash Flows right here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com