
Earnings Surprise Setup Might Change The Case For Investing In Alkermes Stock
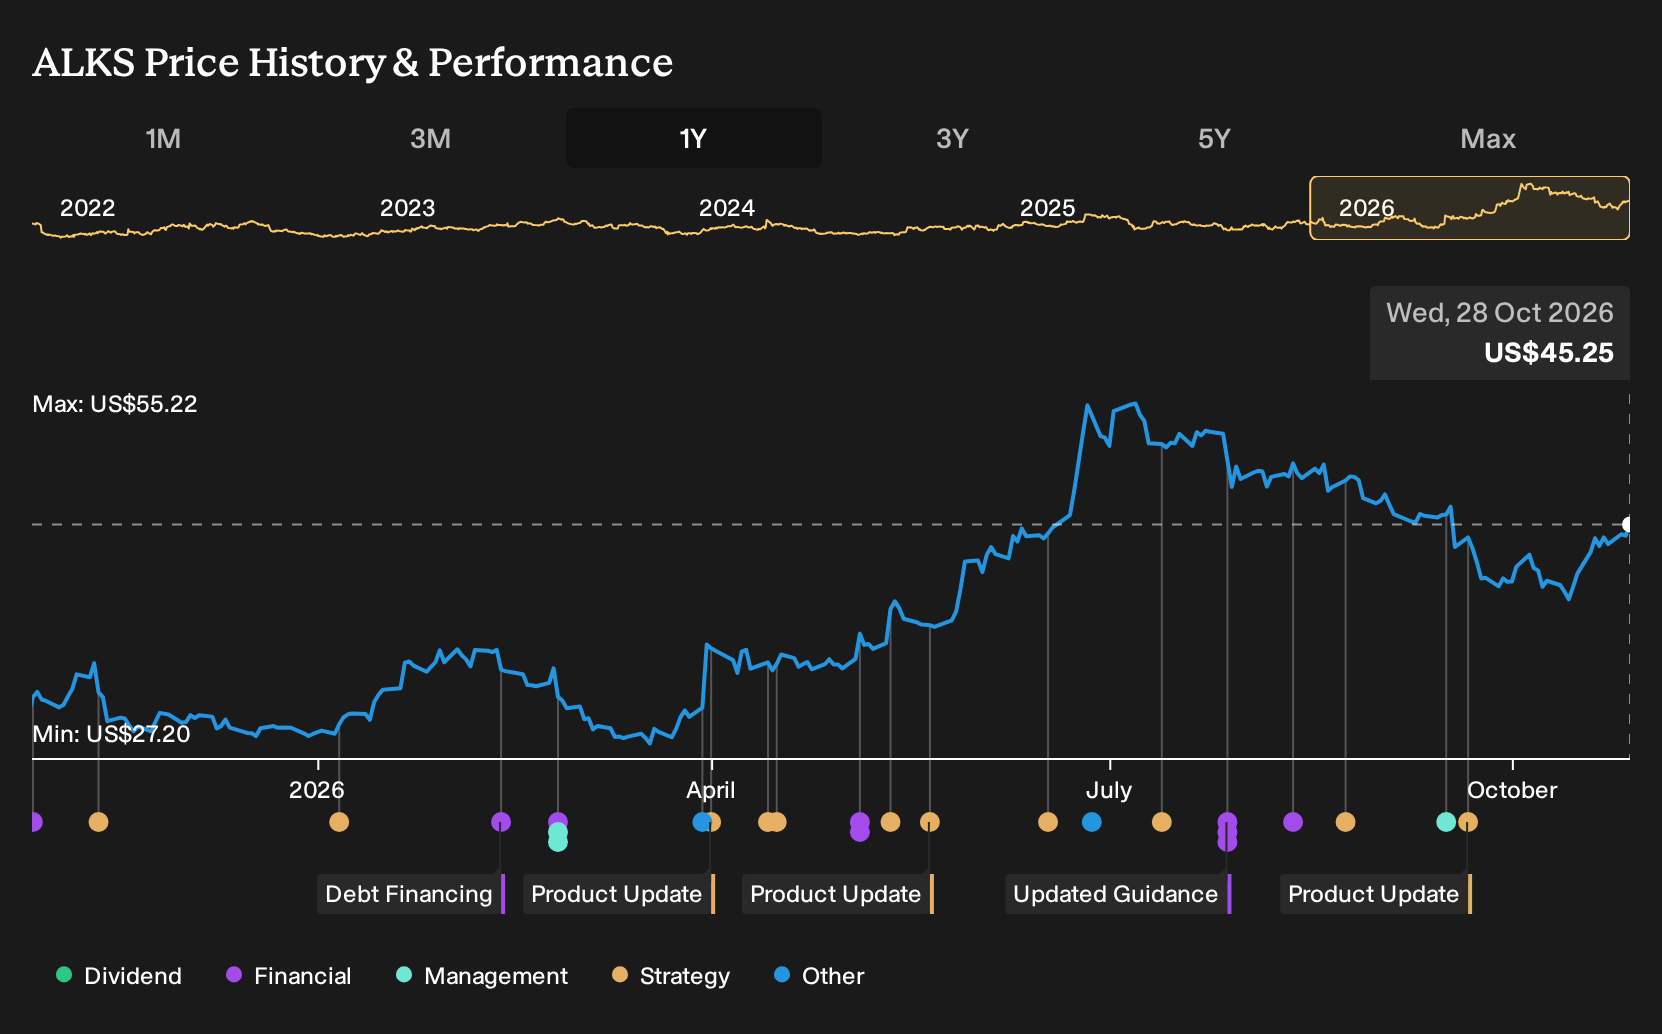
- Alkermes recently entered its September 2026 earnings season with the market expecting a quarterly loss and higher revenue than the prior year, alongside a positive Earnings ESP of 50% and a Zacks Rank of 4.
- The more interesting angle is how this setup tests Alkermes' ability to fund heavy orexin and LUMRYZ investment while still surprising on earnings after four straight EPS beats.
- We will look at how Alkermes' investment narrative is shaped by expectations of another potential earnings surprise ahead of its quarterly report.
Alkermes Investment Narrative Recap
To be comfortable owning Alkermes, you need to believe its psychiatry and addiction franchise can keep funding heavy orexin and LUMRYZ spending while the pipeline matures. The latest expectation of a quarterly loss with higher revenue keeps that tradeoff front and center. It highlights an operating model that leans on positive EBITDA while accepting GAAP losses in 2026.
The short term catalyst still sits in orexin and LUMRYZ execution, including late stage studies and the planned LUMRYZ label expansion work. The biggest risk is that elevated R&D and integration costs persist without matching new product contribution. This earnings setup draws a sharper line under that risk reward balance but does not fundamentally change it.
The most relevant recent development for this setup is Alkermes guidance for a GAAP net loss of US$95 million to US$115 million in 2026, alongside positive EBITDA of US$75 million to US$95 million. That framing matters as you weigh an expected quarterly loss against ongoing investment in orexin studies, fatigue programs and LUMRYZ integration.
That same guidance, paired with rising R&D, keeps clinical milestones like Brilliance, Vibrance 3 and the ALKS 7290 Phase 2 readout as the key operational catalysts to watch. Until those data arrive, the business is effectively asking investors to accept compressed margins and higher spending today in exchange for potential future revenue streams tied to sleep and psychiatric disorders.
Alkermes' analyst narrative points to revenue of US$2.3b and earnings of US$363.0 million by 2029, based on an assumed 10.6% annual revenue growth rate and an earnings increase of about US$297.0 million from US$66.1 million today.
Uncover why Alkermes' fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Alkermes, the bullish twist is earnings power. The most optimistic analysts were penciling in US$2.9b of revenue and US$1.0b of earnings by 2029, compared with the consensus US$2.3b and US$363.0 million. That is a very different storyline. Treat this quarterly loss and revenue setup as a trigger to recheck which version you find more convincing, since both views were formed before this latest update and may shift from here.
Explore 4 other Alkermes fair value estimates, including one that suggests as much as 108% above the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alkermes research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Alkermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alkermes' overall financial health at a glance.
Looking for more Alkermes investment ideas and comparables?
If the Alkermes story has sharpened your thinking about risk, balance sheets and future cash generation, it can help to put that view alongside other stocks with very different profiles. Use the Simply Wall St Screener to scan wider, pressure test your thesis and build a watchlist that matches how you like to take risk.
- For investors who want quality with a margin of safety, compare Alkermes with companies flagged in our 26 high quality undervalued stocks and see how their fundamentals stack up.
- If capital preservation sits high on your priority list, balance your Alkermes view by screening for 32 resilient stocks with low risk scores that score well on financial strength and volatility.
- When you are ready to broaden the opportunity set beyond the usual tickers, scan for 19 high quality undiscovered gems that pair solid financials with under-the-radar profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com